Contrast Media Market Size, Share, Growth Opportunity Analysis Report by Type of Contrast Media (Iodinated, Gadolinium-based, Barium-sulfate, Microbubble, Manganese-based, Iron-based, Others), Modality, Route of Administration, End Users, Imaging Frequency, Distribution Channel, Patient Demographics, and Geography (North America, Europe, Asia Pacific, Middle East, Africa, and South America) – Global Industry Data, Trends, and Forecasts, 2025–2035
Market Overview:
As per MarketGenics, the global Contrast Media Market is experiencing significant growth, valued at USD 6.6 billion in 2025 and projected to reach USD 14.1 billion by 2035, registering a CAGR of 7.2% during the forecast period.
|
Market Structure & Evolution |
|
|
Segmental Data Insights |
|
|
Demand Trends |
|
|
Competitive Landscape |
|
|
Strategic Development |
|
|
Future Outlook & Opportunities |
|
Contrast Media Market Size, Share, and Growth
The market for contrast media continues to expand rapidly, primarily due to the increase in global imaging procedures, based on a growing patient need for rapid and accurate diagnosis of diseases (such as cancer, cardiovascular diseases, and neurological diseases).
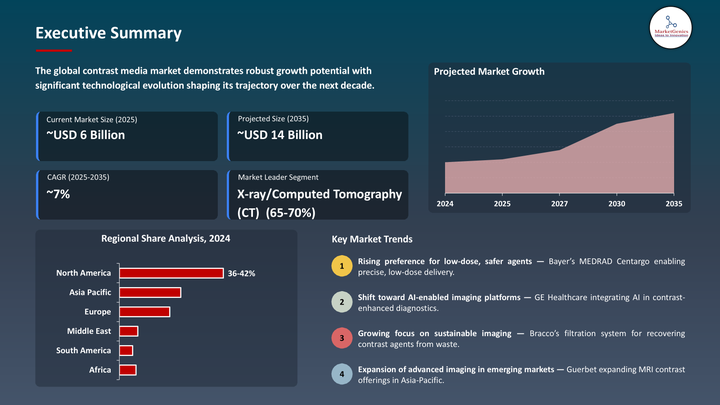
The contrast media market has made great strides in the recent times, with the rollout of next-generation agents featuring greater imaging clarity, more tolerable side effects, and more patient-safe approaches. Companies such as GE HealthCare and Bracco Imaging released improved iodinated and gadolinium formulations that were better tolerated with lower toxicity, and were more specific to types of patients with cardiovascular concerns or concern regarding contrast sensitivity. These newer agents resulted in quicker scans, lower doses, and improved diagnostic accuracy in CT and MRI, respectively.
The expanding dependence on imaging technologies (such as MRI and CT scan), provoke demand for safer, more successful contrast media. As a result, companies are producing formulations of contrast media that are low-toxicity, high-clarity, and reduce the risk of adverse reactions for patients with renal insufficiency or other allergy-based criteria. Patients experience clearer images (with side effects minimized) and have decreased wait for results.
Further, the emergence of low-cost alternatives for contrast agents in low- and middle-income nations has ensured that such patients can access the most critical of diagnostic services. However, there are concerns about over-exposure and adverse reactions within vulnerable populations. Healthcare providers are also working to improve scanning protocols and develop patient-specific directives for administration of contrast media (particularly for the children and elderly).
Moreover, between these changes, and the emergence of reliable, safe and effective contrast media technologies worldwide are supporting these agents to become more accessible and valuable to value-based diagnostic care practice.
Contrast Media Market Dynamics and Trends
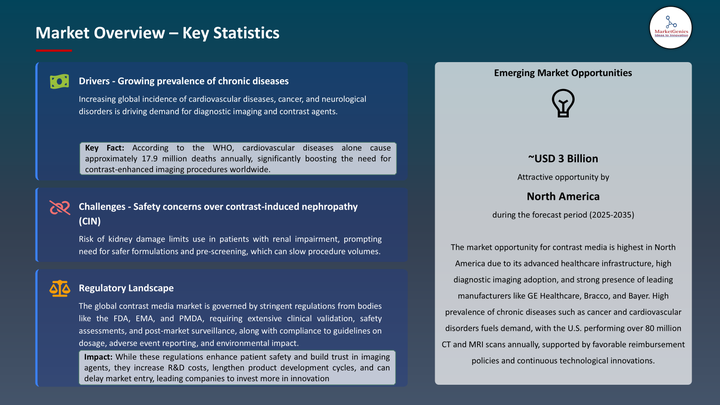
Market Drivers: Growing Need for Accurate Imaging, Safer Formulations, and Wider Access Boosting Contrast Media Demand
-
The usage of contrast media is on the rise as hospitals and diagnostic facilities increasingly utilize imaging modalities like CT scans, MRIs, and ultrasounds, as they desire faster, more accurate, and earlier identification of ailments. While there appears to be a general rise in the number of patients receiving diagnosis of cancer, heart disease, and neurological conditions, the clarity of images is a necessity for fast and accurate diagnosis.
- Consequently, newer formulations of contrast agents are being developed for patient safety, especially for patients with kidney impairment, or allergy to imaging agents. These formulations result in fewer side effects and increased patient comfort during the scan. Furthermore, a number of developing countries are improving access to diagnostic imaging.
- Thus, resulting in an increased demand for affordable contrast media. In light of the apparent desire for early diagnosis and safer healthcare, the market continues to grow steadily, even in regions with both higher and lower incomes.
Market Restraints: Cost Pressures, Safety Concerns, and Strict Regulations Limiting Growth of Contrast Media Market
-
The contrast media market is growing, but it is still facing numerous serious challenges. The cost of developing and producing advanced contrast agents that are safe and effective, particularly for patients with kidney problems, or those with allergies, is high. This cost is often pushed down to hospitals and patients which makes it very difficult for healthcare systems to take up the latest imaging and solutions.
- Furthermore, due to safety issues with certain ingredients, most notably gadolinium in MRI contrast, there are tight controls, hesitancy, and concerns amongst physicians and patients. Regulatory bodies require extensive safety and performance evidence prior to approval of new agents, which hinders new technology and extends the timelines for agent development. Collectively, these regulatory challenges and safety issues mean that new products are constantly under delay and if they are in a lower income lower-cost area the funding of new technologies is limited.
Opportunity: Rising Demand for Personalized Imaging and Safer, Cost-Effective Contrast Solutions Creating Growth Opportunities
-
The contrast media market is unlocking new opportunities as the global demand for imaging, which is more personalized and accurate, increases. With the increase in chronic diseases such as cancer, cardiovascular diseases, and neurological diseases, as it relates to quality diagnostic imaging that is safe and efficient, transforming technology will develop in the areas of low-dose, organ-system contrast media, or AI integrated solutions by GE HealthCare and Guerbet in 2024 and into 2025. This is all about pushing scan precision with minimal patient risk.
- Interestingly, there is also a lot of energy around cost-effective agents that can be manufactured in emerging markets where healthcare is accessing care of untold proportions. Integrated innovations such as smart contrast injectors and AI-imaging platforms in radiology workflows have the potential to shift the path of transformational adoption and personalized patient care. Each of these developments will position the contrast media market to respond to clinical need in an increasing manner while enhancing patient safety, comfort, and affordable access.
Key Trend: Increasing Shift toward Low-Dose, Affordable Contrast Agents for Safer Diagnostic Imaging
-
The global contrast media market has expanded recently with a notable trend towards low-dose and cost-effective agents that can achieve results that are clear and crisp while also being safer for the patient. There is greater awareness of the possible side effects for everyone, but especially for those people with kidney problems, and cariologists, and healthcare organizations have looked for alternatives. There are major companies developing new formulations that require a dose volume of contrast reduction while still producing good quality imaging results.
- Further, this development is especially pertinent in emerging markets where cost is a barrier to access. The growth in demand for diagnostic imaging from rising rates of cancer, cardiovascular conditions, and neurological disease means that hospitals and diagnostic centres are more likely to use safe, lower cost, and patient-friendly solutions for contrast media. Use of these contrast solutions that are lower cost, and lower dose, should allow more patients to access timely, accurate diagnostic information.
Contrast Media Market Analysis and Segmental Data
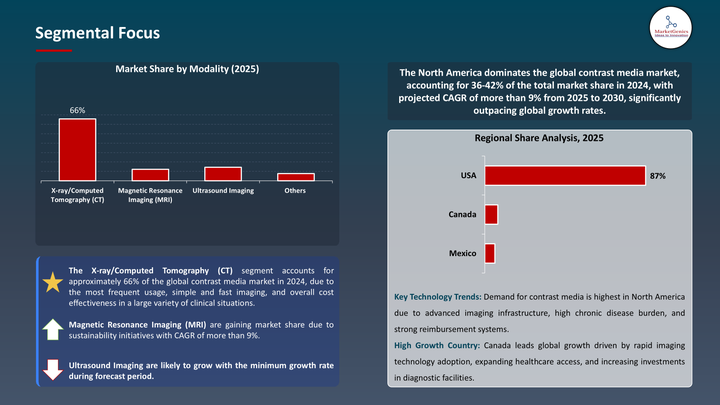
Based on Modality, X-ray/Computed Tomography (CT) holds the largest share
-
X-ray/CT accounts for the largest share in the contrast media market due to the most frequent usage, simple and fast imaging, and overall cost effectiveness in a large variety of clinical situations. CT is the most heavily used in emergency medicine, oncology, cardiac imaging, and trauma as these investigations require relatively rapid imaging of internal cross-sectional anatomy, where CT can produce detailed, cross-sectional images of body organs quickly.
- Many of these procedures require certain iodinated contrast agents for imaging, which are commercially available and have excellent safety long-term safety profiles. In conjunction with new technology like low-dose CT and newer formulations of contrast agents, CT can be done with much greater patient safety, and image quality.
- Overall, CT is favored over MRI and ultrasound in both developed and developing nations, making it an easier option for hospitals or diagnostics centers to implement. Due to CT being the most frequently used imaging modality for routine diagnostic and follow-up care, there will be persistent demand for contrast media, in CT. Therefore, CT will maintain the largest share of the market in the future.
North America Dominates Global Contrast Media Market in 2025 and Beyond
North America leads the world in the contrast media market throughout 2025 because of its strong healthcare system, high adoption of advanced imaging technologies, and increased spending on diagnostic services. North America has a large number of hospitals, diagnostic centers, and highly trained radiologists using contrast agents in CT scans, MRIs, and other procedures to diagnose and detect disease reliably and early. Moreover, the U.S. and Canada have established reimbursement systems, have an ample supply of advanced diagnostic tools, and are governed by professional organizations with regulatory oversight. Continued research and development from leading North American companies, such as GE HealthCare and Bracco Diagnostics, play an important role in changing introduced contrast agents that are safer for patients, more effective, and easier to administer.
The rapid increase in chronic diseases such as cancer and cardiovascular disorders increases demand for diagnostic imaging. Ongoing adjustments to the regulatory landscape, the existence of effective procedures for early diagnosis, and innovation will ensure that North America continues to dominate the contrast media landscape for several years to come beyond 2024.
Contrast Media Market Ecosystem
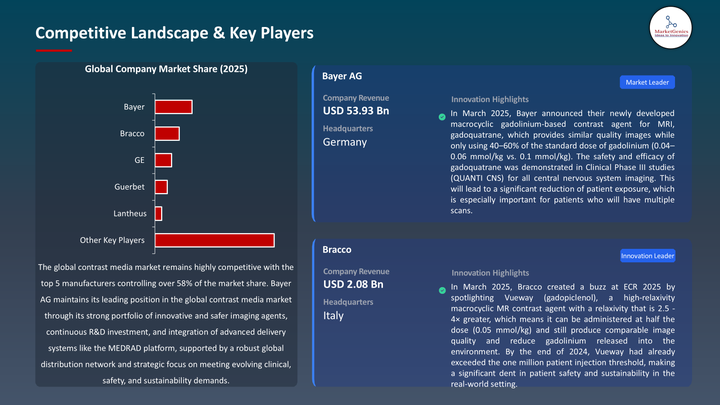
Key players in the global contrast media market include prominent companies such as Bayer AG, Bracco Imaging S.p.A, GE Healthcare, Guerbet Group, Lantheus Holdings, Inc. and Other Key Players.
The global contrast media market exhibits a moderately consolidated structure, with a medium-to-high level of market concentration. Tier 1 players such as GE HealthCare, Bayer AG, and Guerbet Group dominate due to expansive product portfolios, R&D capabilities, and strong distribution networks. Tier 2 includes regional and specialized firms like Lantheus Holdings and Bracco Imaging, while Tier 3 encompasses niche or emerging firms such as Subhra Pharma and Magnetic Insight. Buyer power is moderate, driven by hospital consolidation and group purchasing organizations, which exert pricing pressure. Supplier power is high due to the limited number of manufacturers of advanced imaging agents and proprietary production processes.
Recent Development and Strategic Overview:
-
In March 2025, Bayer has introduced its MEDRAD Centargo Cardio CT injection system, a connected platform that ensures accurate delivery of contrast while also improving efficiencies in workflow within busy hospitals. It addresses the demand for safe, low-dose contrast agents and AI-enabled delivery systems, to help radiology teams deliver personal and efficient diagnostic imaging.
- In May 2025, Bracco introduced Vueway (gadopiclenol) a gadolinium agent with high-relaxivity, requiring lower dosing, and announced a hospital filtration system designed to trap and recover contrast agents from patient waste. These developments reflect an emerging demand for environmentally responsible imaging solutions, relevant for a shifting medical community that desires better diagnostic accuracy, enhanced safety, and a commitment to sustainable environmental practices.
These advancements signal a broader convergence between contrast delivery systems and the AI in Diagnostics, where algorithm-driven dose optimization and workflow intelligence are becoming standard across radiology departments.
Report Scope
|
Detail |
|
|
Market Size in 2025 |
USD 6.6 Bn |
|
Market Forecast Value in 2035 |
USD 14.1 Bn |
|
Growth Rate (CAGR) |
7.2% |
|
Forecast Period |
2025 – 2035 |
|
Historical Data Available for |
2021 – 2024 |
|
Market Size Units |
US$ Billion for Value |
|
Report Format |
Electronic (PDF) + Excel |
|
North America |
Europe |
Asia Pacific |
Middle East |
Africa |
South America |
|
|
|
|
|
|
|
Companies Covered |
|||||
|
|
|
|
|
|
Contrast media Market Segmentation and Highlights
|
Segment |
Sub-segment |
|
By Type of Contrast Media |
|
|
By Modality |
|
|
By Route of Administration |
|
|
By End-users |
|
|
By Imaging Frequency |
|
|
By Distribution Channel |
|
|
By Patient Demographics |
|
Frequently Asked Questions
-
Table of Contents
- Research Methodology and Assumptions
- 1. Definitions
- 2. Research Design and Approach
- 3. Data Collection Methods
- 4. Base Estimates and Calculations
- 5. Forecasting Models
- 5.1. Key Forecast Factors & Impact Analysis
- 6. Secondary Research
- 6.1. Open Sources
- 6.2. Paid Databases
- 6.3. Associations
- 7. Primary Research
- 7.1. Primary Sources
- 7.2. Primary Interviews with Stakeholders across Ecosystem
- Executive Summary
- Contrast Media Market Outlook
- Contrast Media Market Size (Value - US$ Billion), and Forecasts, 2021-2035
- Compounded Annual Growth Rate Analysis
- Growth Opportunity Analysis
- Segmental Share Analysis
- Geographical Share Analysis
- Market Analysis and Facts
- Supply-Demand Analysis
- Competitive Benchmarking
- Go-to- Market Strategy
- Customer/ End-use Industry Assessment
- Growth Opportunity Data, 2025-2035
- Regional Data
- Country Data
- Segmental Data
- Identification of Potential Market Spaces
- GAP Analysis
- Potential Attractive Price Points
- Prevailing Market Risks & Challenges
- Preferred Sales & Marketing Strategies
- Key Recommendations and Analysis
- A Way Forward
- Contrast Media Market Outlook
- Industry Data and Premium Insights
- Contrast Media Industry Overview, 2024
- Healthcare & Pharmaceutical Industry Ecosystem Analysis
- Key Trends for Healthcare & Pharmaceutical Industry
- Regional Distribution for Healthcare & Pharmaceutical Industry
- Supplier Customer Data
- Source Roadmap and Developments
- Trade Analysis
- Import & Export Analysis, 2024
- Top Importing Countries
- Top Exporting Countries
- Trump Tariff Impact Analysis
- Manufacturer
- Supply Chain
- End Consumer
- Raw Material Analysis
- Contrast Media Industry Overview, 2024
Note* - This is just tentative list of players. While providing the report, we will cover more number of players based on their revenue and share for each geography
- Market Overview
- Market Dynamics
- Drivers
- Growing Need for Accurate Imaging, Safer Formulations, and Wider Access Boosting Contrast Media Demand
- Restraints
- Cost Pressures, Safety Concerns, and Strict Regulations Limiting Growth of Contrast Media Market
- Drivers
- Key Trend Analysis
- Regulatory Framework
- Key Regulations, Norms, and Subsidies, by Key Countries
- Tariffs and Standards
- Impact Analysis of Regulations on the Market
- Value Chain Analysis
- Raw Material Sourcing
- Manufacturing and Processing
- Wholesalers/ E-commerce Platform
- End-use/ Customers
- Cost Structure Analysis
- Parameter’s Share for Cost Associated
- COGP vs COGS
- Profit Margin Analysis
- Pricing Analysis
- Regional Pricing Analysis
- Segmental Pricing Trends
- Factors Influencing Pricing
- Porter’s Five Forces Analysis
- PESTEL Analysis
- Contrast Media Market Demand
- Historical Market Size - Value (US$ Billion), 2021-2024
- Current and Future Market Size - Value (US$ Billion), 2025–2035
- Y-o-Y Growth Trends
- Absolute $ Opportunity Assessment
- Market Dynamics
- Competition Landscape
- Competition structure
- Fragmented v/s consolidated
- Company Share Analysis, 2024
- Global Company Market Share
- By Region
- North America
- Europe
- Asia Pacific
- Middle East
- Africa
- South America
- Product Comparison Matrix
- Specifications
- Market Positioning
- Pricing
- Competition structure
- Contrast Media Market Analysis, by Type of Contrast Media
- Key Segment Analysis
- Contrast Media Market Size (Value - US$ Billion), Analysis, and Forecasts, by Type of Contrast Media, 2021-2035
- Iodinated
- Gadolinium-based
- Barium-sulfate
- Microbubble
- Manganese-based
- Iron-based
- Others
- Contrast Media Market Analysis, by Modality
- Key Segment Analysis
- Contrast Media Market Size (Value - US$ Billion), Analysis, and Forecasts, by Modality, 2021-2035
- X-ray/Computed Tomography (CT)
- Magnetic Resonance Imaging (MRI)
- Ultrasound Imaging
- Others (Fluoroscopy, Interventional Radiology, etc.)
- Contrast Media Market Analysis, by Route of Administration
- Key Segment Analysis
- Contrast Media Market Size (Value - US$ Billion), Analysis, and Forecasts, by Route of Administration, 2021-2035
- Intravenous (IV)
- Oral
- Rectal
- Intra-arterial
- Others
- Contrast Media Market Analysis, by End-users
- Key Segment Analysis
- Contrast Media Market Size (Value - US$ Billion), Analysis, and Forecasts, by End-users, 2021-2035
- Hospitals
- Diagnostic Imaging Centers
- Ambulatory Surgical Centers (ASCs)
- Specialty Clinics
- Research and Academic Institutions
- Others
- Contrast Media Market Analysis and Forecasts, by Imaging Frequency
- Key Findings
- Contrast Media Market Size (Value - US$ Billion), Analysis, and Forecasts, by Imaging Frequency, 2021-2035
- Single-use imaging
- Routine/repetitive use
- Emergency imaging
- Contrast Media Market Analysis and Forecasts, by Distribution Channel
- Key Findings
- Contrast Media Market Size (Value - US$ Billion), Analysis, and Forecasts, by Distribution Channel, 2021-2035
- Hospital Pharmacies
- Retail Pharmacies
- Online Pharmacies
- Direct Sales
- Contrast Media Market Analysis and Forecasts, by Patient Demographics
- Key Findings
- Contrast Media Market Size (Value - US$ Billion), Analysis, and Forecasts, by Patient Demographics, 2021-2035
- Adult
- Pediatric
- Geriatric
- Pregnant Women
- Renally Compromised Patients
- Oncology Patients
- Others
- Contrast Media Market Analysis and Forecasts, by Region
- Key Findings
- Contrast Media Market Size (Value - US$ Billion), Analysis, and Forecasts, by Region, 2021-2035
- North America
- Europe
- Asia Pacific
- Middle East
- Africa
- South America
- North America Contrast Media Market Analysis
- Key Segment Analysis
- Regional Snapshot
- North America Contrast Media Market Size (Value - US$ Billion), Analysis, and Forecasts, 2021-2035
- Type of Contrast Media
- Modality
- Route of Administration
- End-users
- Imaging Frequency
- Distribution Channel
- Patient Demographics
- Country
- USA
- Canada
- Mexico
- USA Contrast Media Market
- Country Segmental Analysis
- Type of Contrast Media
- Modality
- Route of Administration
- End-users
- Imaging Frequency
- Distribution Channel
- Patient Demographics
- Canada Contrast Media Market
- Country Segmental Analysis
- Type of Contrast Media
- Modality
- Route of Administration
- End-users
- Imaging Frequency
- Distribution Channel
- Patient Demographics
- Mexico Contrast Media Market
- Country Segmental Analysis
- Type of Contrast Media
- Modality
- Route of Administration
- End-users
- Imaging Frequency
- Distribution Channel
- Patient Demographics
- Europe Contrast Media Market Analysis
- Key Segment Analysis
- Regional Snapshot
- Europe Contrast Media Market Size (Value - US$ Billion), Analysis, and Forecasts, 2021-2035
- Type of Contrast Media
- Modality
- Route of Administration
- End-users
- Imaging Frequency
- Distribution Channel
- Patient Demographics
- Country
- Germany
- United Kingdom
- France
- Italy
- Spain
- Netherlands
- Nordic Countries
- Poland
- Russia & CIS
- Rest of Europe
- Germany Contrast Media Market
- Country Segmental Analysis
- Type of Contrast Media
- Modality
- Route of Administration
- End-users
- Imaging Frequency
- Distribution Channel
- Patient Demographics
- United Kingdom Contrast Media Market
- Country Segmental Analysis
- Type of Contrast Media
- Modality
- Route of Administration
- End-users
- Imaging Frequency
- Distribution Channel
- Patient Demographics
- France Contrast Media Market
- Country Segmental Analysis
- Type of Contrast Media
- Modality
- Route of Administration
- End-users
- Imaging Frequency
- Distribution Channel
- Patient Demographics
- Italy Contrast Media Market
- Country Segmental Analysis
- Type of Contrast Media
- Modality
- Route of Administration
- End-users
- Imaging Frequency
- Distribution Channel
- Patient Demographics
- Spain Contrast Media Market
- Country Segmental Analysis
- Type of Contrast Media
- Modality
- Route of Administration
- End-users
- Imaging Frequency
- Distribution Channel
- Patient Demographics
- Netherlands Contrast Media Market
- Country Segmental Analysis
- Type of Contrast Media
- Modality
- Route of Administration
- End-users
- Imaging Frequency
- Distribution Channel
- Patient Demographics
- Nordic Countries Contrast Media Market
- Country Segmental Analysis
- Type of Contrast Media
- Modality
- Route of Administration
- End-users
- Imaging Frequency
- Distribution Channel
- Patient Demographics
- Poland Contrast Media Market
- Country Segmental Analysis
- Type of Contrast Media
- Modality
- Route of Administration
- End-users
- Imaging Frequency
- Distribution Channel
- Patient Demographics
- Russia & CIS Contrast Media Market
- Country Segmental Analysis
- Type of Contrast Media
- Modality
- Route of Administration
- End-users
- Imaging Frequency
- Distribution Channel
- Patient Demographics
- Rest of Europe Contrast Media Market
- Country Segmental Analysis
- Type of Contrast Media
- Modality
- Route of Administration
- End-users
- Imaging Frequency
- Distribution Channel
- Patient Demographics
- Asia Pacific Contrast Media Market Analysis
- Key Segment Analysis
- Regional Snapshot
- East Asia Contrast Media Market Size (Value - US$ Billion), Analysis, and Forecasts, 2021-2035
- Type of Contrast Media
- Modality
- Route of Administration
- End-users
- Imaging Frequency
- Distribution Channel
- Patient Demographics
- Country
- China
- India
- Japan
- South Korea
- Australia and New Zealand
- Indonesia
- Malaysia
- Thailand
- Vietnam
- Rest of Asia-Pacific
- China Contrast Media Market
- Country Segmental Analysis
- Type of Contrast Media
- Modality
- Route of Administration
- End-users
- Imaging Frequency
- Distribution Channel
- Patient Demographics
- India Contrast Media Market
- Country Segmental Analysis
- Type of Contrast Media
- Modality
- Route of Administration
- End-users
- Imaging Frequency
- Distribution Channel
- Patient Demographics
- Japan Contrast Media Market
- Country Segmental Analysis
- Type of Contrast Media
- Modality
- Route of Administration
- End-users
- Imaging Frequency
- Distribution Channel
- Patient Demographics
- South Korea Contrast Media Market
- Country Segmental Analysis
- Type of Contrast Media
- Modality
- Route of Administration
- End-users
- Imaging Frequency
- Distribution Channel
- Patient Demographics
- Australia and New Zealand Contrast Media Market
- Country Segmental Analysis
- Type of Contrast Media
- Modality
- Route of Administration
- End-users
- Imaging Frequency
- Distribution Channel
- Patient Demographics
- Indonesia Contrast Media Market
- Country Segmental Analysis
- Type of Contrast Media
- Modality
- Route of Administration
- End-users
- Imaging Frequency
- Distribution Channel
- Patient Demographics
- Malaysia Contrast Media Market
- Country Segmental Analysis
- Type of Contrast Media
- Modality
- Route of Administration
- End-users
- Imaging Frequency
- Distribution Channel
- Patient Demographics
- Thailand Contrast Media Market
- Country Segmental Analysis
- Type of Contrast Media
- Modality
- Route of Administration
- End-users
- Imaging Frequency
- Distribution Channel
- Patient Demographics
- Vietnam Contrast Media Market
- Country Segmental Analysis
- Type of Contrast Media
- Modality
- Route of Administration
- End-users
- Imaging Frequency
- Distribution Channel
- Patient Demographics
- Rest of Asia Pacific Contrast Media Market
- Country Segmental Analysis
- Type of Contrast Media
- Modality
- Route of Administration
- End-users
- Imaging Frequency
- Distribution Channel
- Patient Demographics
- Middle East Contrast Media Market Analysis
- Key Segment Analysis
- Regional Snapshot
- Middle East Contrast Media Market Size (Value - US$ Billion), Analysis, and Forecasts, 2021-2035
- Type of Contrast Media
- Modality
- Route of Administration
- End-users
- Imaging Frequency
- Distribution Channel
- Patient Demographics
- Country
- Turkey
- UAE
- Saudi Arabia
- Israel
- Rest of Middle East
- Turkey Contrast Media Market
- Country Segmental Analysis
- Type of Contrast Media
- Modality
- Route of Administration
- End-users
- Imaging Frequency
- Distribution Channel
- Patient Demographics
- UAE Contrast Media Market
- Country Segmental Analysis
- Type of Contrast Media
- Modality
- Route of Administration
- End-users
- Imaging Frequency
- Distribution Channel
- Patient Demographics
- Saudi Arabia Contrast Media Market
- Country Segmental Analysis
- Type of Contrast Media
- Modality
- Route of Administration
- End-users
- Imaging Frequency
- Distribution Channel
- Patient Demographics
- Israel Contrast Media Market
- Country Segmental Analysis
- Type of Contrast Media
- Modality
- Route of Administration
- End-users
- Imaging Frequency
- Distribution Channel
- Patient Demographics
- Rest of Middle East Contrast Media Market
- Country Segmental Analysis
- Type of Contrast Media
- Modality
- Route of Administration
- End-users
- Imaging Frequency
- Distribution Channel
- Patient Demographics
- Africa Contrast Media Market Analysis
- Key Segment Analysis
- Regional Snapshot
- Africa Contrast Media Market Size (Value - US$ Billion), Analysis, and Forecasts, 2021-2035
- Type of Contrast Media
- Modality
- Route of Administration
- End-users
- Imaging Frequency
- Distribution Channel
- Patient Demographics
- Country
- South Africa
- Egypt
- Nigeria
- Algeria
- Rest of Africa
- South Africa Contrast Media Market
- Country Segmental Analysis
- Type of Contrast Media
- Modality
- Route of Administration
- End-users
- Imaging Frequency
- Distribution Channel
- Patient Demographics
- Egypt Contrast Media Market
- Country Segmental Analysis
- Type of Contrast Media
- Modality
- Route of Administration
- End-users
- Imaging Frequency
- Distribution Channel
- Patient Demographics
- Nigeria Contrast Media Market
- Country Segmental Analysis
- Type of Contrast Media
- Modality
- Route of Administration
- End-users
- Imaging Frequency
- Distribution Channel
- Patient Demographics
- Algeria Contrast Media Market
- Country Segmental Analysis
- Type of Contrast Media
- Modality
- Route of Administration
- End-users
- Imaging Frequency
- Distribution Channel
- Patient Demographics
- Rest of Africa Contrast Media Market
- Country Segmental Analysis
- Type of Contrast Media
- Modality
- Route of Administration
- End-users
- Imaging Frequency
- Distribution Channel
- Patient Demographics
- South America Contrast Media Market Analysis
- Key Segment Analysis
- Regional Snapshot
- Central and South Africa Contrast Media Market Size (Value - US$ Billion), Analysis, and Forecasts, 2021-2035
- Type of Contrast Media
- Modality
- Route of Administration
- End-users
- Imaging Frequency
- Distribution Channel
- Patient Demographics
- Country
- Brazil
- Argentina
- Rest of South America
- Brazil Contrast Media Market
- Country Segmental Analysis
- Type of Contrast Media
- Modality
- Route of Administration
- End-users
- Imaging Frequency
- Distribution Channel
- Patient Demographics
- Argentina Contrast Media Market
- Country Segmental Analysis
- Type of Contrast Media
- Modality
- Route of Administration
- End-users
- Imaging Frequency
- Distribution Channel
- Patient Demographics
- Rest of South America Contrast Media Market
- Country Segmental Analysis
- Type of Contrast Media
- Modality
- Route of Administration
- End-users
- Imaging Frequency
- Distribution Channel
- Patient Demographics
- Key Players/ Company Profile
- Bayer AG
- Company Details/ Overview
- Company Financials
- Key Customers and Competitors
- Business/ Industry Portfolio
- Product Portfolio/ Specification Details
- Pricing Data
- Strategic Overview
- Recent Developments
- Bracco Imaging S.p.A.
- CMR Naviscan Corporation
- Curium Pharma
- Daiichi Sankyo Company, Limited
- GE HealthCare
- Guerbet Group
- ImaginAb Inc.
- Jodas Expoim Pvt Ltd
- Jubilant Radiopharma
- Lantheus Holdings, Inc.
- Magnetic Insight, Inc.
- nanoPET Pharma GmbH
- Novalek Pharmaceuticals Pvt. Ltd.
- Sanochemia Pharmazeutika GmbH
- Spago Nanomedical AB
- Spectrum Dynamics Medical
- Subhra Pharma
- Taejoon Pharm Co., Ltd.
- Trivitron Healthcare
- Unijules Life Sciences Ltd.
- Zydus Lifesciences Ltd.
- Other Key Players
- Bayer AG
Research Design
Our research design integrates both demand-side and supply-side analysis through a balanced combination of primary and secondary research methodologies. By utilizing both bottom-up and top-down approaches alongside rigorous data triangulation methods, we deliver robust market intelligence that supports strategic decision-making.
MarketGenics' comprehensive research design framework ensures the delivery of accurate, reliable, and actionable market intelligence. Through the integration of multiple research approaches, rigorous validation processes, and expert analysis, we provide our clients with the insights needed to make informed strategic decisions and capitalize on market opportunities.
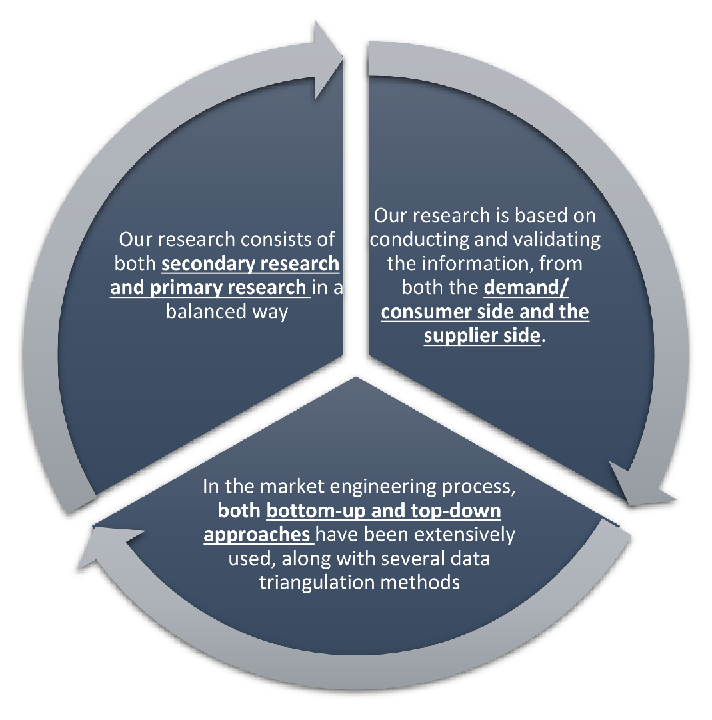
MarketGenics leverages a dedicated industry panel of experts and a comprehensive suite of paid databases to effectively collect, consolidate, and analyze market intelligence.
Our approach has consistently proven to be reliable and effective in generating accurate market insights, identifying key industry trends, and uncovering emerging business opportunities.
Through both primary and secondary research, we capture and analyze critical company-level data such as manufacturing footprints, including technical centers, R&D facilities, sales offices, and headquarters.
Our expert panel further enhances our ability to estimate market size for specific brands based on validated field-level intelligence.
Our data mining techniques incorporate both parametric and non-parametric methods, allowing for structured data collection, sorting, processing, and cleaning.
Demand projections are derived from large-scale data sets analyzed through proprietary algorithms, culminating in robust and reliable market sizing.
Research Approach
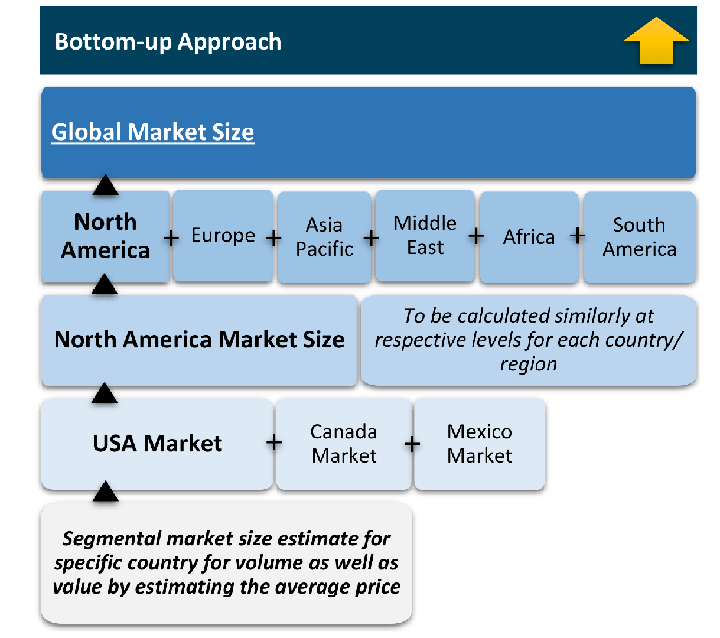
The bottom-up approach builds market estimates by starting with the smallest addressable market units and systematically aggregating them to create comprehensive market size projections.
This method begins with specific, granular data points and builds upward to create the complete market landscape.
Customer Analysis → Segmental Analysis → Geographical Analysis
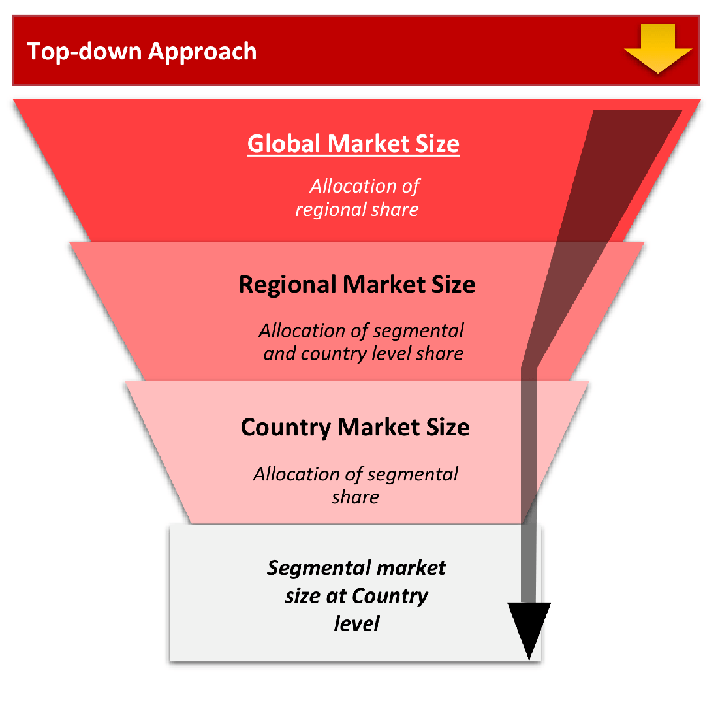
The top-down approach starts with the broadest possible market data and systematically narrows it down through a series of filters and assumptions to arrive at specific market segments or opportunities.
This method begins with the big picture and works downward to increasingly specific market slices.
TAM → SAM → SOM
Research Methods
Desk / Secondary Research
While analysing the market, we extensively study secondary sources, directories, and databases to identify and collect information useful for this technical, market-oriented, and commercial report. Secondary sources that we utilize are not only the public sources, but it is a combination of Open Source, Associations, Paid Databases, MG Repository & Knowledgebase, and others.
- Company websites, annual reports, financial reports, broker reports, and investor presentations
- National government documents, statistical databases and reports
- News articles, press releases and web-casts specific to the companies operating in the market, Magazines, reports, and others
- We gather information from commercial data sources for deriving company specific data such as segmental revenue, share for geography, product revenue, and others
- Internal and external proprietary databases (industry-specific), relevant patent, and regulatory databases
- Governing Bodies, Government Organizations
- Relevant Authorities, Country-specific Associations for Industries
We also employ the model mapping approach to estimate the product level market data through the players' product portfolio
Primary Research
Primary research/ interviews is vital in analyzing the market. Most of the cases involves paid primary interviews. Primary sources include primary interviews through e-mail interactions, telephonic interviews, surveys as well as face-to-face interviews with the different stakeholders across the value chain including several industry experts.
| Type of Respondents | Number of Primaries |
|---|---|
| Tier 2/3 Suppliers | ~20 |
| Tier 1 Suppliers | ~25 |
| End-users | ~25 |
| Industry Expert/ Panel/ Consultant | ~30 |
| Total | ~100 |
MG Knowledgebase
• Repository of industry blog, newsletter and case studies
• Online platform covering detailed market reports, and company profiles
Forecasting Factors and Models
Forecasting Factors
- Historical Trends – Past market patterns, cycles, and major events that shaped how markets behave over time. Understanding past trends helps predict future behavior.
- Industry Factors – Specific characteristics of the industry like structure, regulations, and innovation cycles that affect market dynamics.
- Macroeconomic Factors – Economic conditions like GDP growth, inflation, and employment rates that affect how much money people have to spend.
- Demographic Factors – Population characteristics like age, income, and location that determine who can buy your product.
- Technology Factors – How quickly people adopt new technology and how much technology infrastructure exists.
- Regulatory Factors – Government rules, laws, and policies that can help or restrict market growth.
- Competitive Factors – Analyzing competition structure such as degree of competition and bargaining power of buyers and suppliers.
Forecasting Models / Techniques
Multiple Regression Analysis
- Identify and quantify factors that drive market changes
- Statistical modeling to establish relationships between market drivers and outcomes
Time Series Analysis – Seasonal Patterns
- Understand regular cyclical patterns in market demand
- Advanced statistical techniques to separate trend, seasonal, and irregular components
Time Series Analysis – Trend Analysis
- Identify underlying market growth patterns and momentum
- Statistical analysis of historical data to project future trends
Expert Opinion – Expert Interviews
- Gather deep industry insights and contextual understanding
- In-depth interviews with key industry stakeholders
Multi-Scenario Development
- Prepare for uncertainty by modeling different possible futures
- Creating optimistic, pessimistic, and most likely scenarios
Time Series Analysis – Moving Averages
- Sophisticated forecasting for complex time series data
- Auto-regressive integrated moving average models with seasonal components
Econometric Models
- Apply economic theory to market forecasting
- Sophisticated economic models that account for market interactions
Expert Opinion – Delphi Method
- Harness collective wisdom of industry experts
- Structured, multi-round expert consultation process
Monte Carlo Simulation
- Quantify uncertainty and probability distributions
- Thousands of simulations with varying input parameters
Research Analysis
Our research framework is built upon the fundamental principle of validating market intelligence from both demand and supply perspectives. This dual-sided approach ensures comprehensive market understanding and reduces the risk of single-source bias.
Demand-Side Analysis: We understand end-user/application behavior, preferences, and market needs along with the penetration of the product for specific application.
Supply-Side Analysis: We estimate overall market revenue, analyze the segmental share along with industry capacity, competitive landscape, and market structure.
Validation & Evaluation
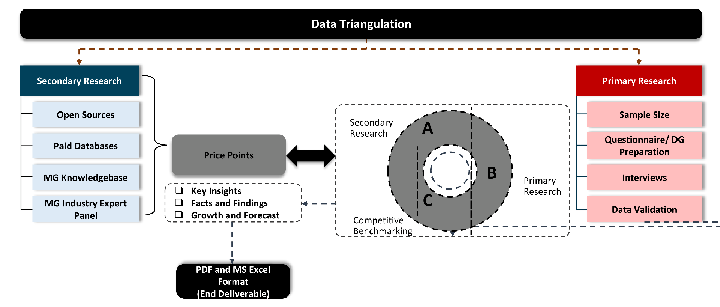
Data triangulation is a validation technique that uses multiple methods, sources, or perspectives to examine the same research question, thereby increasing the credibility and reliability of research findings. In market research, triangulation serves as a quality assurance mechanism that helps identify and minimize bias, validate assumptions, and ensure accuracy in market estimates.
- Data Source Triangulation – Using multiple data sources to examine the same phenomenon
- Methodological Triangulation – Using multiple research methods to study the same research question
- Investigator Triangulation – Using multiple researchers or analysts to examine the same data
- Theoretical Triangulation – Using multiple theoretical perspectives to interpret the same data
Custom Market Research Services
We will customise the research for you, in case the report listed above does not meet your requirements.
Get 10% Free Customisation