Home Diagnostics Market Size, Share & Trends Analysis Report by Product Type (Blood Glucose Monitoring Kits, Blood Pressure Monitoring Devices, Pregnancy & Fertility Test Kits, Infectious Disease Test Kits, Cholesterol Test Kits, Urinalysis Test Kits, Coagulation Monitoring Devices, Cardiac Marker Test Kits, Genetic Testing Kits, Drug Abuse Test Kits, Allergy Test Kits, Kidney Function Test Kits, Liver Function Test Kits, Thyroid Function Test Kits, Other Home Diagnostic Products), Technology, Sample Type, Connectivity, Application, End User, Distribution Channel and Geography (North America, Europe, Asia Pacific, Middle East, Africa, and South America) – Global Industry Data, Trends, and Forecasts, 2026–2035
|
|
|
Segmental Data Insights |
|
|
Demand Trends |
|
|
Competitive Landscape |
|
|
Strategic Development |
|
|
Future Outlook & Opportunities |
|
Home Diagnostics Market Size, Share, and Growth
The global home diagnostics market is witnessing strong growth, valued at USD 4.9 billion in 2025 and projected to reach USD 7.9 billion by 2035, expanding at a CAGR of 4.9% during the forecast period.
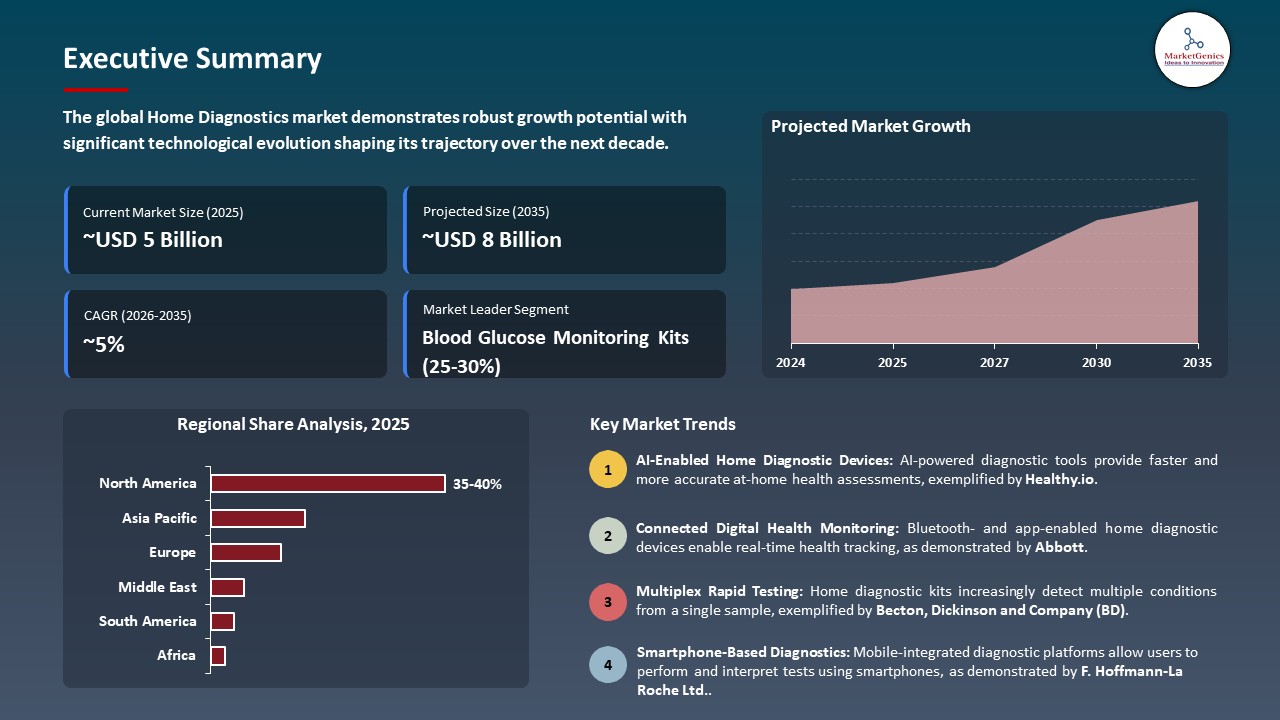
Nikos Pavlidis, worldwide president of BD Diagnostic Solutions, said, “This certification marks a meaningful advancement in our efforts to expand access to cervical cancer screening around the world, by enabling fully automated processing of self-collected samples, we're helping laboratories improve efficiency while making it easier for underscreened persons to participate in screening programs from the comfort of their homes”
Advanced blood-based diagnostics are driving adoption in healthcare systems, especially where early, accurate and minimally invasive detection is desired. With the growing aging population and the increasing prevalence of chronic neurological diseases, the demand for scalable diagnostic solutions is growing that do not require specialized imaging infrastructure and enable timely diagnosis and treatment. The diagnostic technologies based on blood analysis provide an affordable, accessible and clinically efficient alternative, paving the way for more widespread adoption of precision medicine and decentralized healthcare.
C2N Diagnostics also joined SouthGenetics in 2026 to roll out blood-based blood tests for Alzheimer's assessment to Latin America and the Caribbean to complement earlier diagnosis in areas without PET imaging or dementia specialists. Rising use of point-of-care blood diagnostics is broadening the scope of early detection and driving the shift towards decentralized diagnostics care.
Adjacent growth opportunities for the home diagnostics market include remote patient monitoring, digital therapeutics, telehealth platforms, wearable health monitoring devices, and AI-powered diagnostic software. These complementary markets strengthen decentralized healthcare by enabling continuous monitoring, personalized care, and seamless integration of home-generated health data with clinical decision-making.
Home Diagnostics Market Dynamics and Trends
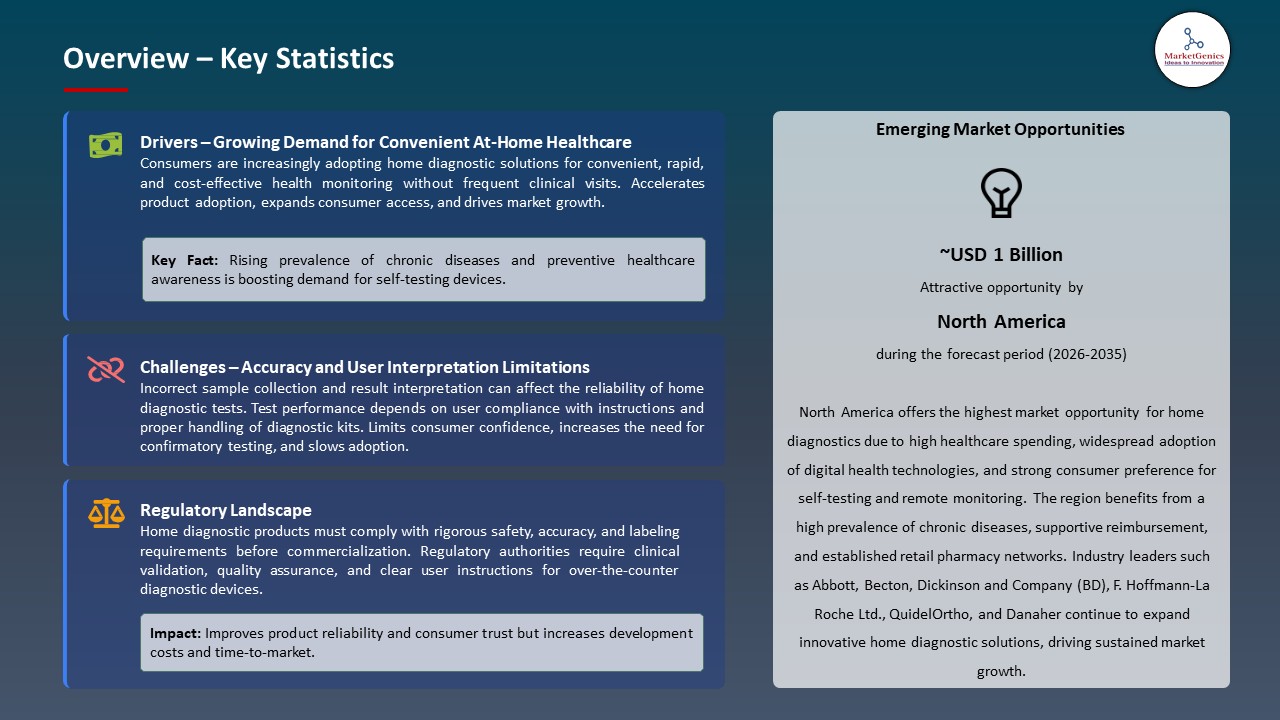
Driver: Rising Prevalence of Chronic Diseases Requiring Continuous Home Health Monitoring
- The prevalence of chronic health conditions like diabetes, cardiovascular diseases, hypertension, and chronic kidney disease is rising, creating a growing need for home diagnostic solutions which will allow the monitoring of health conditions from the convenience of the home.
- The role of home-based testing is growing in importance, as patients and healthcare providers embrace it for the benefits of early disease diagnosis, better treatment compliance, and fewer visits to the hospital due to regular health checks.
- The focus on prevention in healthcare and the development of connected diagnostic devices and digital health platforms are also driving the rapidly increasing use of reliable home monitoring tools for long-term disease management.
- The prevalence of chronic diseases is increasing, creating a growing need for affordable, wireless, and individual-focused home diagnostic technologies globally.
Restraint: Limited Reimbursement Coverage and Uneven Consumer Access Restrict Broader Market Penetration
- Limited reimbursement policies and inconsistent insurance coverage continue to hinder the adoption of home diagnostic products, particularly advanced molecular and connected testing solutions. In many markets, consumers are required to bear significant out-of-pocket expenses, limiting affordability and reducing adoption.
- Regional disparities in reimbursement frameworks, unequal access between urban and rural areas, and limited inclusion of premium home diagnostic kits within public healthcare systems further constrain market penetration. Continued reliance on laboratory-based diagnostics for standardized reimbursement pathways also slows the shift toward home-based testing.
- Reimbursement limitations and affordability challenges continue to restrain the widespread adoption of advanced home diagnostic solutions.
Opportunity: Rising Investment in At-Home Infectious Disease Diagnostics Expands Consumer Testing Access
- The increasing investment in novel diagnostic technologies for the home environment is opening up novel avenues for rapid, accessible and decentralized infectious disease testing.
- Digital health integration and the development of an easy-to-use testing platform are helping manufacturers to address sexual health, preventive care and remote patient management unmet needs.
- In June 2026, LotusDx launched a new R&D laboratory at ONE BioHub, aiming to expedite development of at home STI diagnostic kits for chlamydia and gonorrhea, while advancing clinical validation and commercialization efforts for solutions that are connected to an app.
- The growth of home-based infectious disease diagnostics is opening up new commercial possibilities and further dovetailing the decentralization and consumerization of health services.
Key Trend: AI-Enabled Decentralized Diagnostics and Integration of Home Diagnostics with Digital Health Platforms
- The home diagnostics market is becoming more decentralized with AI-powered home testing, a shift toward home testing that is embedded in the digital health platforms, telehealth, and connected care ecosystems.
- AI-powered analytics, automated scheduling, remote clinical support, and cloud-based results management are enhancing diagnostic reach, streamlining workflows, and promoting patient engagement, while also facilitating tailored and timely healthcare experiences.
- In 2026, Function Health merged with Getlabs to create a single digital health platform that combines AI-powered at-home diagnostics, remote blood collection and AI-scheduling for a more preventative care approach, thereby increasing access to decentralized diagnostics throughout the United States.
- The adoption of AI in home diagnostics is driving the shift towards connected, preventive, and patient-centric healthcare.
Home Diagnostics Market Analysis and Segmental Data
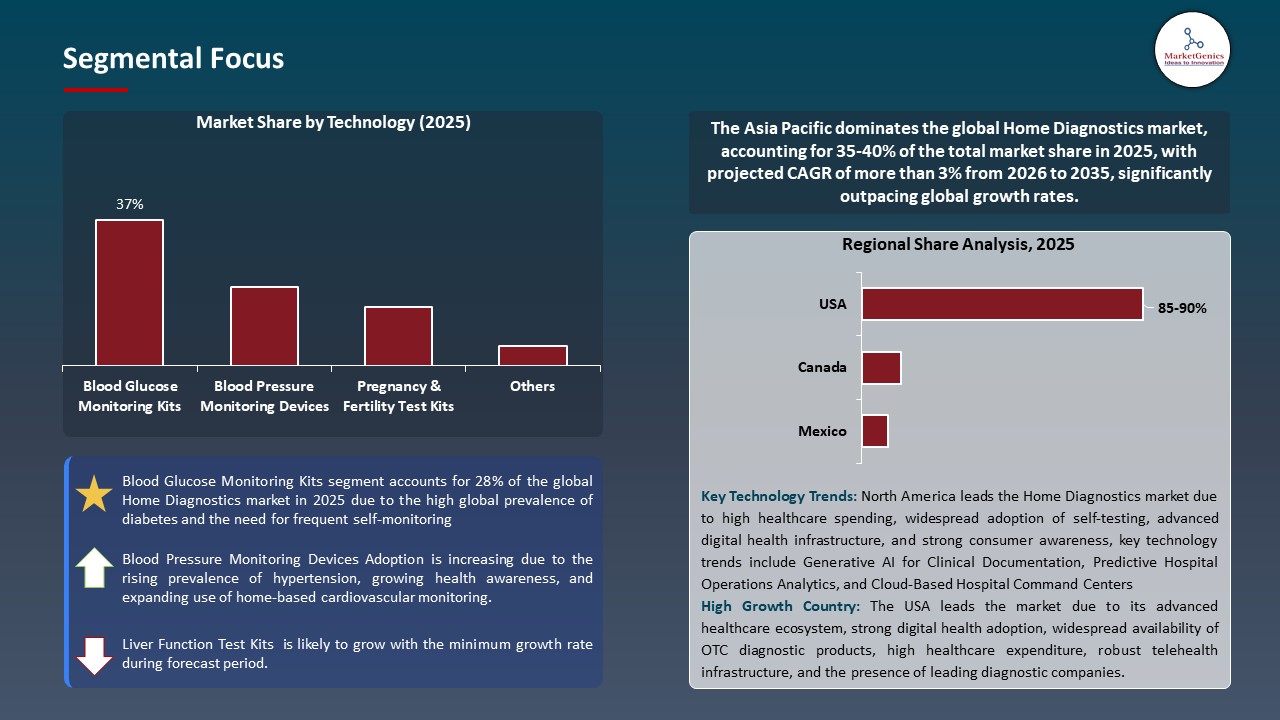
Blood Glucose Monitoring Kits Dominate Global Home Diagnostics Market
- The growing prevalence of diabetes worldwide and the need to monitor glucose levels at home has made blood glucose monitoring kits the largest part of the home diagnostics market. These technologies allow patients to easily monitor their glucose levels at home, which can aid in timely adjustments in treatment, better control of the disease, and less reliance on healthcare infrastructure.
- Robust technological developments such as connected glucose meters, continuous glucose monitoring (CGM) systems and smartphone-enabled application software are increasingly making the use of these devices more user-friendly, accurate and easy to operate in real-time, leading to their growing adoption in developed and emerging markets.
- Rising diabetes prevalence and innovation in connected glucose monitoring technologies continue to strengthen the leadership of this segment in the home diagnostics market.
North America Leads Global Home Diagnostics Market Demand
- Advanced healthcare infrastructure, high awareness and increasing self-testing and connected health technologies adoption in North America drive the market. Chronic diseases are prevalent in the region, and telehealth has been very well adopted, and there is a good regulatory environment for over-the-counter diagnostic products, which promotes home-based testing solutions.
- Additionally, the market holds the presence of leading diagnostics manufacturers, continuous product innovation, extensive retail pharmacy networks, and strong digital health ecosystems, further strengthening market growth. With the rising investments in preventive health care and RPT, home diagnostic devices are witnessing growing demand in the region.
- The healthcare market in North America remains a strong leader and is pushing digital diagnostics further with its quick adoption especially in the home diagnostics sector.
Home Diagnostics Market Ecosystem
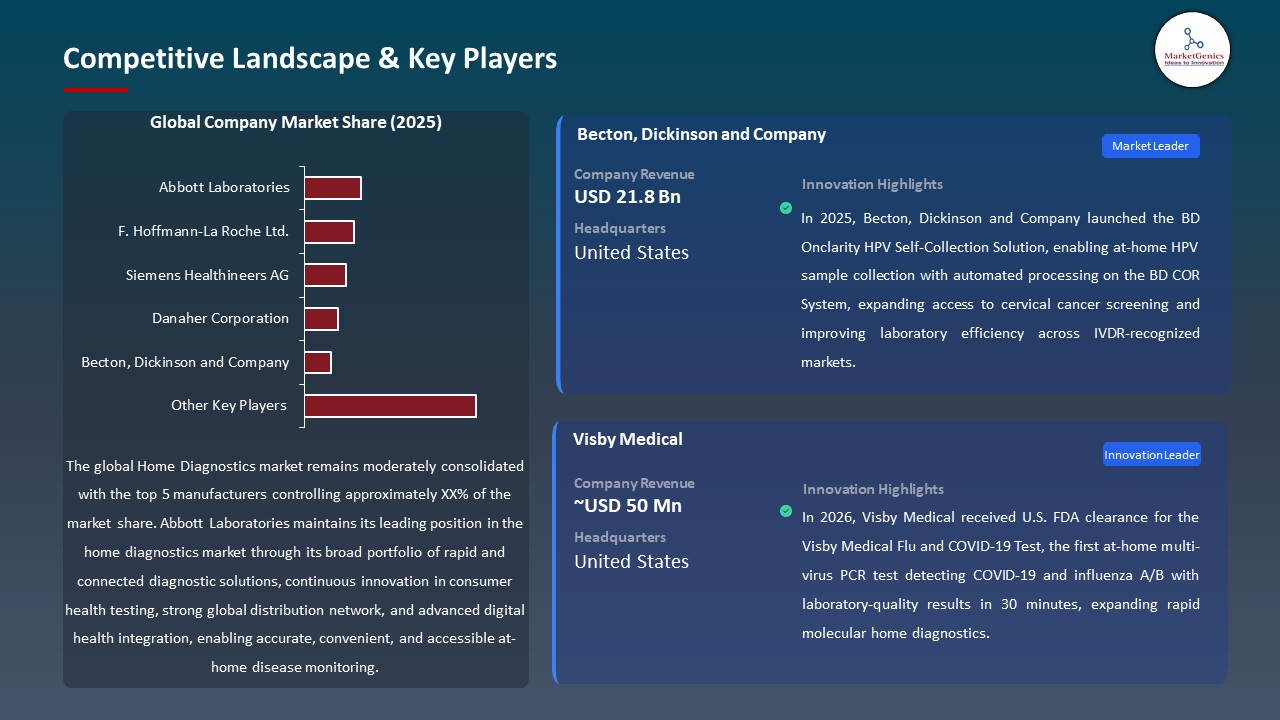
The global home diagnostics market is consolidated, led by Abbott Laboratories, F. Hoffmann-La Roche Ltd., Siemens Healthineers AG, Danaher Corporation, and Becton, Dickinson and Company. These companies maintain leadership through innovation in rapid diagnostics, molecular testing, continuous glucose monitoring, and connected home diagnostic solutions, supported by strong R&D capabilities, global distribution networks, and regulatory expertise.
The value chain includes raw materials, biosensors, reagents, assay development, device manufacturing, software integration, regulatory approvals, and distribution. Home diagnostics support chronic disease monitoring, infectious disease detection, pregnancy testing, and preventive health screening.
The market has moderate-to-high entry barriers due to stringent regulatory requirements, high R&D costs, diagnostic validation, and advanced manufacturing needs. Leading players sustain their position through proprietary technologies, strong brands, global reach, and continuous product innovation.
Recent Development and Strategic Overview
- In October 2025, Becton, Dickinson and Company launched the BD Onclarity HPV Self-Collection Solution, enabling at-home HPV sample collection with automated processing on the BD COR System, expanding access to cervical cancer screening and improving laboratory efficiency across IVDR-recognized market.
- In July 2026, Visby Medical received U.S. FDA clearance for the Visby Medical Flu and COVID-19 Test, the first at-home multi-virus PCR test detecting COVID-19 and influenza A/B with laboratory-quality results in 30 minutes, expanding rapid molecular home diagnostics.
Report Scope
|
Detail |
|
|
Market Size in 2025 |
USD 4.9 Bn |
|
Market Forecast Value in 2035 |
USD 7.9 Bn |
|
Growth Rate (CAGR) |
4.9% |
|
Forecast Period |
2026 – 2035 |
|
Historical Data Available for |
2021 – 2024 |
|
Market Size Units |
US$ Billion for Value |
|
Report Format |
Electronic (PDF) + Excel |
|
North America |
Europe |
Asia Pacific |
Middle East |
Africa |
South America |
|
|
|
|
|
|
|
Companies Covered |
|||||
|
|
|
||||
Home Diagnostics Market Segmentation and Highlights
|
Segment |
Sub-segment |
|
Home Diagnostics Market, By Product Type |
|
|
Home Diagnostics Market, By Technology |
|
|
Home Diagnostics Market, By Sample Type |
|
|
Home Diagnostics Market, By Connectivity |
|
|
Home Diagnostics Market, By Application |
|
|
Home Diagnostics Market, By End-user |
|
|
Home Diagnostics Market, By Distribution Channel |
|
Frequently Asked Questions
Table of Contents
- 1. Research Methodology and Assumptions
- 1.1. Definitions
- 1.2. Research Design and Approach
- 1.3. Data Collection Methods
- 1.4. Base Estimates and Calculations
- 1.5. Forecasting Models
- 1.5.1. Key Forecast Factors & Impact Analysis
- 1.6. Secondary Research
- 1.6.1. Open Sources
- 1.6.2. Paid Databases
- 1.6.3. Associations
- 1.7. Primary Research
- 1.7.1. Primary Sources
- 1.7.2. Primary Interviews with Stakeholders across Ecosystem
- 2. Executive Summary
- 2.1. Global Home Diagnostics Market Outlook
- 2.1.1. Home Diagnostics Market Size (Value - US$ Bn), and Forecasts, 2021-2035
- 2.1.2. Compounded Annual Growth Rate Analysis
- 2.1.3. Growth Opportunity Analysis
- 2.1.4. Segmental Share Analysis
- 2.1.5. Geographical Share Analysis
- 2.2. Market Analysis and Facts
- 2.3. Supply-Demand Analysis
- 2.4. Competitive Benchmarking
- 2.5. Go-to- Market Strategy
- 2.5.1. Customer/ End-use Industry Assessment
- 2.5.2. Growth Opportunity Data, 2026-2035
- 2.5.2.1. Regional Data
- 2.5.2.2. Country Data
- 2.5.2.3. Segmental Data
- 2.5.3. Identification of Potential Market Spaces
- 2.5.4. GAP Analysis
- 2.5.5. Potential Attractive Price Points
- 2.5.6. Prevailing Market Risks & Challenges
- 2.5.7. Preferred Sales & Marketing Strategies
- 2.5.8. Key Recommendations and Analysis
- 2.5.9. A Way Forward
- 2.1. Global Home Diagnostics Market Outlook
- 3. Industry Data and Premium Insights
- 3.1. Global Healthcare & Pharmaceutical Industry Overview, 2025
- 3.1.1. Healthcare & Pharmaceutical Ecosystem Analysis
- 3.1.2. Key Trends for Healthcare & Pharmaceutical Industry
- 3.1.3. Regional Distribution for Healthcare & Pharmaceutical Industry
- 3.2. Supplier Customer Data
- 3.3. Technology Roadmap and Developments
- 3.1. Global Healthcare & Pharmaceutical Industry Overview, 2025
- 4. Market Overview
- 4.1. Market Dynamics
- 4.1.1. Drivers
- 4.1.1.1. Rising prevalence of chronic diseases and need for continuous health monitoring
- 4.1.1.2. Growing consumer preference for convenient, rapid, and private at-home testing
- 4.1.1.3. Expansion of digital health, telehealth, and connected diagnostic devices.
- 4.1.2. Restraints
- 4.1.2.1. Accuracy and reliability concerns in self-administered testing
- 4.1.2.2. Regulatory complexities and stringent approval requirements for home-use diagnostic products
- 4.1.1. Drivers
- 4.2. Key Trend Analysis
- 4.3. Regulatory Framework
- 4.3.1. Key Regulations, Norms, and Subsidies, by Key Countries
- 4.3.2. Tariffs and Standards
- 4.3.3. Impact Analysis of Regulations on the Market
- 4.4. Ecosystem Analysis
- 4.5. Porter’s Five Forces Analysis
- 4.6. PESTEL Analysis
- 4.7. Global Home Diagnostics Market Demand
- 4.7.1. Historical Market Size – in Value (US$ Bn), 2020-2024
- 4.7.2. Current and Future Market Size – in Value (US$ Bn), 2026–2035
- 4.7.2.1. Y-o-Y Growth Trends
- 4.7.2.2. Absolute $ Opportunity Assessment
- 4.1. Market Dynamics
- 5. Competition Landscape
- 5.1. Competition structure
- 5.1.1. Fragmented v/s consolidated
- 5.2. Company Share Analysis, 2025
- 5.2.1. Global Company Market Share
- 5.2.2. By Region
- 5.2.2.1. North America
- 5.2.2.2. Europe
- 5.2.2.3. Asia Pacific
- 5.2.2.4. Middle East
- 5.2.2.5. Africa
- 5.2.2.6. South America
- 5.3. Product Comparison Matrix
- 5.3.1. Specifications
- 5.3.2. Market Positioning
- 5.3.3. Pricing
- 5.1. Competition structure
- 6. Global Home Diagnostics Market Analysis, by Product Type
- 6.1. Key Segment Analysis
- 6.2. Home Diagnostics Market Size (Value - US$ Bn), Analysis, and Forecasts, by Product Type, 2021-2035
- 6.2.1. Blood Glucose Monitoring Kits
- 6.2.2. Blood Pressure Monitoring Devices
- 6.2.3. Pregnancy & Fertility Test Kits
- 6.2.4. Infectious Disease Test Kits
- 6.2.5. Cholesterol Test Kits
- 6.2.6. Urinalysis Test Kits
- 6.2.7. Coagulation Monitoring Devices
- 6.2.8. Cardiac Marker Test Kits
- 6.2.9. Genetic Testing Kits
- 6.2.10. Drug Abuse Test Kits
- 6.2.11. Allergy Test Kits
- 6.2.12. Kidney Function Test Kits
- 6.2.13. Liver Function Test Kits
- 6.2.14. Thyroid Function Test Kits
- 6.2.15. Other Home Diagnostic Products
- 7. Global Home Diagnostics Market Analysis, by Technology
- 7.1. Key Segment Analysis
- 7.2. Home Diagnostics Market Size (Value - US$ Bn), Analysis, and Forecasts, by Technology, 2021-2035
- 7.2.1. Lateral Flow Assays
- 7.2.2. Immunoassays
- 7.2.3. Molecular Diagnostics
- 7.2.4. Biosensor Technology
- 7.2.5. Lab-on-a-Chip
- 7.2.6. Microfluidics
- 7.2.7. Electrochemical Diagnostics
- 7.2.8. AI-Enabled Diagnostics
- 7.2.9. Digital Health Platforms
- 7.2.10. Others
- 8. Global Home Diagnostics Market Analysis, by Sample Type
- 8.1. Key Segment Analysis
- 8.2. Home Diagnostics Market Size (Value - US$ Bn), Analysis, and Forecasts, by Sample Type, 2021-2035
- 8.2.1. Blood
- 8.2.2. Urine
- 8.2.3. Saliva
- 8.2.4. Nasal Swab
- 8.2.5. Stool
- 8.2.6. Breath
- 8.2.7. Buccal Swab
- 8.2.8. Other Biological Samples
- 9. Global Home Diagnostics Market Analysis, by Connectivity
- 9.1. Key Segment Analysis
- 9.2. Home Diagnostics Market Size (Value - US$ Bn), Analysis, and Forecasts, by Connectivity, 2021-2035
- 9.2.1. Standalone Devices
- 9.2.2. Bluetooth-Enabled Devices
- 9.2.3. Wi-Fi-Enabled Devices
- 9.2.4. Smartphone-Connected Devices
- 9.2.5. Cloud-Connected Devices
- 10. Global Home Diagnostics Market Analysis, by Application
- 10.1. Key Segment Analysis
- 10.2. Home Diagnostics Market Size (Value - US$ Bn), Analysis, and Forecasts, by Application, 2021-2035
- 10.2.1. Diabetes Management
- 10.2.2. Cardiovascular Disease Monitoring
- 10.2.3. Pregnancy & Fertility Testing
- 10.2.4. Infectious Disease Detection
- 10.2.5. Cholesterol Monitoring
- 10.2.6. Kidney Disease Monitoring
- 10.2.7. Liver Disease Monitoring
- 10.2.8. Respiratory Disease Detection
- 10.2.9. Cancer Screening
- 10.2.10. Drug & Alcohol Testing
- 10.2.11. Others
- 11. Global Home Diagnostics Market Analysis, by End User
- 11.1. Key Segment Analysis
- 11.2. Home Diagnostics Market Size (Value - US$ Bn), Analysis, and Forecasts, by End User, 2021-2035
- 11.2.1. Individual Consumers
- 11.2.2. Home Healthcare Providers
- 11.2.3. Elderly Population
- 11.2.4. Patients with Chronic Diseases
- 11.2.5. Caregivers
- 11.2.6. Others
- 12. Global Home Diagnostics Market Analysis, by Distribution Channel
- 12.1. Key Segment Analysis
- 12.2. Home Diagnostics Market Size (Value - US$ Bn), Analysis, and Forecasts, by Distribution Channel, 2021-2035
- 12.2.1. Retail Pharmacies
- 12.2.2. Hospital Pharmacies
- 12.2.3. Online Pharmacies
- 12.2.4. E-commerce Platforms
- 12.2.5. Supermarkets & Hypermarkets
- 12.2.6. Specialty Stores
- 12.2.7. Others
- 13. Global Home Diagnostics Market Analysis, by Region
- 13.1. Key Findings
- 13.2. Home Diagnostics Market Size (Value - US$ Bn), Analysis, and Forecasts, by Region, 2021-2035
- 13.2.1. North America
- 13.2.2. Europe
- 13.2.3. Asia Pacific
- 13.2.4. Middle East
- 13.2.5. Africa
- 13.2.6. South America
- 14. North America Home Diagnostics Market Analysis
- 14.1. Key Segment Analysis
- 14.2. Regional Snapshot
- 14.3. North America Home Diagnostics Market Size (Value - US$ Bn), Analysis, and Forecasts, 2021-2035
- 14.3.1. Product Type
- 14.3.2. Technology
- 14.3.3. Sample Type
- 14.3.4. Connectivity
- 14.3.5. Application
- 14.3.6. End User
- 14.3.7. Distribution Channel
- 14.3.8. Country
- 14.3.8.1. USA
- 14.3.8.2. Canada
- 14.3.8.3. Mexico
- 14.4. USA Home Diagnostics Market
- 14.4.1. Country Segmental Analysis
- 14.4.2. Product Type
- 14.4.3. Technology
- 14.4.4. Sample Type
- 14.4.5. Connectivity
- 14.4.6. Application
- 14.4.7. End User
- 14.4.8. Distribution Channel
- 14.5. Canada Home Diagnostics Market
- 14.5.1. Country Segmental Analysis
- 14.5.2. Product Type
- 14.5.3. Technology
- 14.5.4. Sample Type
- 14.5.5. Connectivity
- 14.5.6. Application
- 14.5.7. End User
- 14.5.8. Distribution Channel
- 14.6. Mexico Home Diagnostics Market
- 14.6.1. Country Segmental Analysis
- 14.6.2. Product Type
- 14.6.3. Technology
- 14.6.4. Sample Type
- 14.6.5. Connectivity
- 14.6.6. Application
- 14.6.7. End User
- 14.6.8. Distribution Channel
- 15. Europe Home Diagnostics Market Analysis
- 15.1. Key Segment Analysis
- 15.2. Regional Snapshot
- 15.3. Europe Home Diagnostics Market Size (Value - US$ Bn), Analysis, and Forecasts, 2021-2035
- 15.3.1. Product Type
- 15.3.2. Technology
- 15.3.3. Sample Type
- 15.3.4. Connectivity
- 15.3.5. Application
- 15.3.6. End User
- 15.3.7. Distribution Channel
- 15.3.8. Country
- 15.3.8.1. Germany
- 15.3.8.2. United Kingdom
- 15.3.8.3. France
- 15.3.8.4. Italy
- 15.3.8.5. Spain
- 15.3.8.6. Netherlands
- 15.3.8.7. Nordic Countries
- 15.3.8.8. Poland
- 15.3.8.9. Russia & CIS
- 15.3.8.10. Rest of Europe
- 15.4. Germany Home Diagnostics Market
- 15.4.1. Country Segmental Analysis
- 15.4.2. Product Type
- 15.4.3. Technology
- 15.4.4. Sample Type
- 15.4.5. Connectivity
- 15.4.6. Application
- 15.4.7. End User
- 15.4.8. Distribution Channel
- 15.5. United Kingdom Home Diagnostics Market
- 15.5.1. Country Segmental Analysis
- 15.5.2. Product Type
- 15.5.3. Technology
- 15.5.4. Sample Type
- 15.5.5. Connectivity
- 15.5.6. Application
- 15.5.7. End User
- 15.5.8. Distribution Channel
- 15.6. France Home Diagnostics Market
- 15.6.1. Country Segmental Analysis
- 15.6.2. Product Type
- 15.6.3. Technology
- 15.6.4. Sample Type
- 15.6.5. Connectivity
- 15.6.6. Application
- 15.6.7. End User
- 15.6.8. Distribution Channel
- 15.7. Italy Home Diagnostics Market
- 15.7.1. Country Segmental Analysis
- 15.7.2. Product Type
- 15.7.3. Technology
- 15.7.4. Sample Type
- 15.7.5. Connectivity
- 15.7.6. Application
- 15.7.7. End User
- 15.7.8. Distribution Channel
- 15.8. Spain Home Diagnostics Market
- 15.8.1. Country Segmental Analysis
- 15.8.2. Product Type
- 15.8.3. Technology
- 15.8.4. Sample Type
- 15.8.5. Connectivity
- 15.8.6. Application
- 15.8.7. End User
- 15.8.8. Distribution Channel
- 15.9. Netherlands Home Diagnostics Market
- 15.9.1. Country Segmental Analysis
- 15.9.2. Product Type
- 15.9.3. Technology
- 15.9.4. Sample Type
- 15.9.5. Connectivity
- 15.9.6. Application
- 15.9.7. End User
- 15.9.8. Distribution Channel
- 15.10. Nordic Countries Home Diagnostics Market
- 15.10.1. Country Segmental Analysis
- 15.10.2. Product Type
- 15.10.3. Technology
- 15.10.4. Sample Type
- 15.10.5. Connectivity
- 15.10.6. Application
- 15.10.7. End User
- 15.10.8. Distribution Channel
- 15.11. Poland Home Diagnostics Market
- 15.11.1. Country Segmental Analysis
- 15.11.2. Product Type
- 15.11.3. Technology
- 15.11.4. Sample Type
- 15.11.5. Connectivity
- 15.11.6. Application
- 15.11.7. End User
- 15.11.8. Distribution Channel
- 15.12. Russia & CIS Home Diagnostics Market
- 15.12.1. Country Segmental Analysis
- 15.12.2. Product Type
- 15.12.3. Technology
- 15.12.4. Sample Type
- 15.12.5. Connectivity
- 15.12.6. Application
- 15.12.7. End User
- 15.12.8. Distribution Channel
- 15.13. Rest of Europe Home Diagnostics Market
- 15.13.1. Country Segmental Analysis
- 15.13.2. Product Type
- 15.13.3. Technology
- 15.13.4. Sample Type
- 15.13.5. Connectivity
- 15.13.6. Application
- 15.13.7. End User
- 15.13.8. Distribution Channel
- 16. Asia Pacific Home Diagnostics Market Analysis
- 16.1. Key Segment Analysis
- 16.2. Regional Snapshot
- 16.3. Asia Pacific Home Diagnostics Market Size (Value - US$ Bn), Analysis, and Forecasts, 2021-2035
- 16.3.1. Product Type
- 16.3.2. Technology
- 16.3.3. Sample Type
- 16.3.4. Connectivity
- 16.3.5. Application
- 16.3.6. End User
- 16.3.7. Distribution Channel
- 16.3.8. Country
- 16.3.8.1. China
- 16.3.8.2. India
- 16.3.8.3. Japan
- 16.3.8.4. South Korea
- 16.3.8.5. Australia and New Zealand
- 16.3.8.6. Indonesia
- 16.3.8.7. Malaysia
- 16.3.8.8. Thailand
- 16.3.8.9. Vietnam
- 16.3.8.10. Rest of Asia Pacific
- 16.4. China Home Diagnostics Market
- 16.4.1. Country Segmental Analysis
- 16.4.2. Product Type
- 16.4.3. Technology
- 16.4.4. Sample Type
- 16.4.5. Connectivity
- 16.4.6. Application
- 16.4.7. End User
- 16.4.8. Distribution Channel
- 16.5. India Home Diagnostics Market
- 16.5.1. Country Segmental Analysis
- 16.5.2. Product Type
- 16.5.3. Technology
- 16.5.4. Sample Type
- 16.5.5. Connectivity
- 16.5.6. Application
- 16.5.7. End User
- 16.5.8. Distribution Channel
- 16.6. Japan Home Diagnostics Market
- 16.6.1. Country Segmental Analysis
- 16.6.2. Product Type
- 16.6.3. Technology
- 16.6.4. Sample Type
- 16.6.5. Connectivity
- 16.6.6. Application
- 16.6.7. End User
- 16.6.8. Distribution Channel
- 16.7. South Korea Home Diagnostics Market
- 16.7.1. Country Segmental Analysis
- 16.7.2. Product Type
- 16.7.3. Technology
- 16.7.4. Sample Type
- 16.7.5. Connectivity
- 16.7.6. Application
- 16.7.7. End User
- 16.7.8. Distribution Channel
- 16.8. Australia and New Zealand Home Diagnostics Market
- 16.8.1. Country Segmental Analysis
- 16.8.2. Product Type
- 16.8.3. Technology
- 16.8.4. Sample Type
- 16.8.5. Connectivity
- 16.8.6. Application
- 16.8.7. End User
- 16.8.8. Distribution Channel
- 16.9. End User Indonesia Home Diagnostics Market
- 16.9.1. Country Segmental Analysis
- 16.9.2. Product Type
- 16.9.3. Technology
- 16.9.4. Sample Type
- 16.9.5. Connectivity
- 16.9.6. Application
- 16.9.7. End User
- 16.9.8. Distribution Channel
- 16.10. Malaysia Home Diagnostics Market
- 16.10.1. Country Segmental Analysis
- 16.10.2. Product Type
- 16.10.3. Technology
- 16.10.4. Sample Type
- 16.10.5. Connectivity
- 16.10.6. Application
- 16.10.7. End User
- 16.10.8. Distribution Channel
- 16.11. Thailand Home Diagnostics Market
- 16.11.1. Country Segmental Analysis
- 16.11.2. Product Type
- 16.11.3. Technology
- 16.11.4. Sample Type
- 16.11.5. Connectivity
- 16.11.6. Application
- 16.11.7. End User
- 16.11.8. Distribution Channel
- 16.12. Vietnam Home Diagnostics Market
- 16.12.1. Country Segmental Analysis
- 16.12.2. Product Type
- 16.12.3. Technology
- 16.12.4. Sample Type
- 16.12.5. Connectivity
- 16.12.6. Application
- 16.12.7. End User
- 16.12.8. Distribution Channel
- 16.13. Rest of Asia Pacific Home Diagnostics Market
- 16.13.1. Country Segmental Analysis
- 16.13.2. Product Type
- 16.13.3. Technology
- 16.13.4. Sample Type
- 16.13.5. Connectivity
- 16.13.6. Application
- 16.13.7. End User
- 16.13.8. Distribution Channel
- 17. Middle East Home Diagnostics Market Analysis
- 17.1. Key Segment Analysis
- 17.2. Regional Snapshot
- 17.3. Middle East Home Diagnostics Market Size (Value - US$ Bn), Analysis, and Forecasts, 2021-2035
- 17.3.1. Product Type
- 17.3.2. Technology
- 17.3.3. Sample Type
- 17.3.4. Connectivity
- 17.3.5. Application
- 17.3.6. End User
- 17.3.7. Distribution Channel
- 17.3.8. Country
- 17.3.8.1. Turkey
- 17.3.8.2. UAE
- 17.3.8.3. Saudi Arabia
- 17.3.8.4. Israel
- 17.3.8.5. Rest of Middle East
- 17.4. Turkey Home Diagnostics Market
- 17.4.1. Country Segmental Analysis
- 17.4.2. Product Type
- 17.4.3. Technology
- 17.4.4. Sample Type
- 17.4.5. Connectivity
- 17.4.6. Application
- 17.4.7. End User
- 17.4.8. Distribution Channel
- 17.5. UAE Home Diagnostics Market
- 17.5.1. Country Segmental Analysis
- 17.5.2. Product Type
- 17.5.3. Technology
- 17.5.4. Sample Type
- 17.5.5. Connectivity
- 17.5.6. Application
- 17.5.7. End User
- 17.5.8. Distribution Channel
- 17.6. Saudi Arabia Home Diagnostics Market
- 17.6.1. Country Segmental Analysis
- 17.6.2. Product Type
- 17.6.3. Technology
- 17.6.4. Sample Type
- 17.6.5. Connectivity
- 17.6.6. Application
- 17.6.7. End User
- 17.6.8. Distribution Channel
- 17.7. Israel Home Diagnostics Market
- 17.7.1. Country Segmental Analysis
- 17.7.2. Product Type
- 17.7.3. Technology
- 17.7.4. Sample Type
- 17.7.5. Connectivity
- 17.7.6. Application
- 17.7.7. End User
- 17.7.8. Distribution Channel
- 17.8. Rest of Middle East Home Diagnostics Market
- 17.8.1. Country Segmental Analysis
- 17.8.2. Product Type
- 17.8.3. Technology
- 17.8.4. Sample Type
- 17.8.5. Connectivity
- 17.8.6. Application
- 17.8.7. End User
- 17.8.8. Distribution Channel
- 18. Africa Home Diagnostics Market Analysis
- 18.1. Key Segment Analysis
- 18.2. Regional Snapshot
- 18.3. Africa Home Diagnostics Market Size (Value - US$ Bn), Analysis, and Forecasts, 2021-2035
- 18.3.1. Product Type
- 18.3.2. Technology
- 18.3.3. Sample Type
- 18.3.4. Connectivity
- 18.3.5. Application
- 18.3.6. End User
- 18.3.7. Distribution Channel
- 18.3.8. Country
- 18.3.8.1. South Africa
- 18.3.8.2. Egypt
- 18.3.8.3. Nigeria
- 18.3.8.4. Algeria
- 18.3.8.5. Rest of Africa
- 18.4. South Africa Home Diagnostics Market
- 18.4.1. Country Segmental Analysis
- 18.4.2. Product Type
- 18.4.3. Technology
- 18.4.4. Sample Type
- 18.4.5. Connectivity
- 18.4.6. Application
- 18.4.7. End User
- 18.4.8. Distribution Channel
- 18.5. Egypt Home Diagnostics Market
- 18.5.1. Country Segmental Analysis
- 18.5.2. Product Type
- 18.5.3. Technology
- 18.5.4. Sample Type
- 18.5.5. Connectivity
- 18.5.6. Application
- 18.5.7. End User
- 18.5.8. Distribution Channel
- 18.6. Nigeria Home Diagnostics Market
- 18.6.1. Country Segmental Analysis
- 18.6.2. Product Type
- 18.6.3. Technology
- 18.6.4. Sample Type
- 18.6.5. Connectivity
- 18.6.6. Application
- 18.6.7. End User
- 18.6.8. Distribution Channel
- 18.7. Algeria Home Diagnostics Market
- 18.7.1. Country Segmental Analysis
- 18.7.2. Product Type
- 18.7.3. Technology
- 18.7.4. Sample Type
- 18.7.5. Connectivity
- 18.7.6. Application
- 18.7.7. End User
- 18.7.8. Distribution Channel
- 18.8. Rest of Africa Home Diagnostics Market
- 18.8.1. Country Segmental Analysis
- 18.8.2. Product Type
- 18.8.3. Technology
- 18.8.4. Sample Type
- 18.8.5. Connectivity
- 18.8.6. Application
- 18.8.7. End User
- 18.8.8. Distribution Channel
- 19. South America Home Diagnostics Market Analysis
- 19.1. Key Segment Analysis
- 19.2. Regional Snapshot
- 19.3. South America Home Diagnostics Market Size (Value - US$ Bn), Analysis, and Forecasts, 2021-2035
- 19.3.1. Product Type
- 19.3.2. Technology
- 19.3.3. Sample Type
- 19.3.4. Connectivity
- 19.3.5. Application
- 19.3.6. End User
- 19.3.7. Distribution Channel
- 19.3.8. Country
- 19.3.8.1. Brazil
- 19.3.8.2. Argentina
- 19.3.8.3. Rest of South America
- 19.4. Brazil Home Diagnostics Market
- 19.4.1. Country Segmental Analysis
- 19.4.2. Product Type
- 19.4.3. Technology
- 19.4.4. Sample Type
- 19.4.5. Connectivity
- 19.4.6. Application
- 19.4.7. End User
- 19.4.8. Distribution Channel
- 19.5. Argentina Home Diagnostics Market
- 19.5.1. Country Segmental Analysis
- 19.5.2. Product Type
- 19.5.3. Technology
- 19.5.4. Sample Type
- 19.5.5. Connectivity
- 19.5.6. Application
- 19.5.7. End User
- 19.5.8. Distribution Channel
- 19.6. Rest of South America Home Diagnostics Market
- 19.6.1. Country Segmental Analysis
- 19.6.2. Product Type
- 19.6.3. Technology
- 19.6.4. Sample Type
- 19.6.5. Connectivity
- 19.6.6. Application
- 19.6.7. End User
- 19.6.8. Distribution Channel
- 20. Key Players/ Company Profile
- 20.1. Abbott Laboratories.
- 20.1.1. Company Details/ Overview
- 20.1.2. Company Financials
- 20.1.3. Key Customers and Competitors
- 20.1.4. Business/ Industry Portfolio
- 20.1.5. Product Portfolio/ Specification Details
- 20.1.6. Pricing Data
- 20.1.7. Strategic Overview
- 20.1.8. Recent Developments
- 20.2. ACON Laboratories, Inc.
- 20.3. Becton, Dickinson and Company
- 20.4. bioMérieux SA
- 20.5. Danaher Corporation
- 20.6. EKF Diagnostics Holdings plc
- 20.7. Ellume Limited
- 20.8. F. Hoffmann-La Roche Ltd.
- 20.9. iHealth Labs Inc.
- 20.10. LetsGetChecked
- 20.11. Siemens Healthineers AG
- 20.12. Trinity Biotech plc
- 20.13. Other Key Players
- 20.1. Abbott Laboratories.
Note* - This is just tentative list of players. While providing the report, we will cover more number of players based on their revenue and share for each geography
Research Design
Our research design integrates both demand-side and supply-side analysis through a balanced combination of primary and secondary research methodologies. By utilizing both bottom-up and top-down approaches alongside rigorous data triangulation methods, we deliver robust market intelligence that supports strategic decision-making.
MarketGenics' comprehensive research design framework ensures the delivery of accurate, reliable, and actionable market intelligence. Through the integration of multiple research approaches, rigorous validation processes, and expert analysis, we provide our clients with the insights needed to make informed strategic decisions and capitalize on market opportunities.
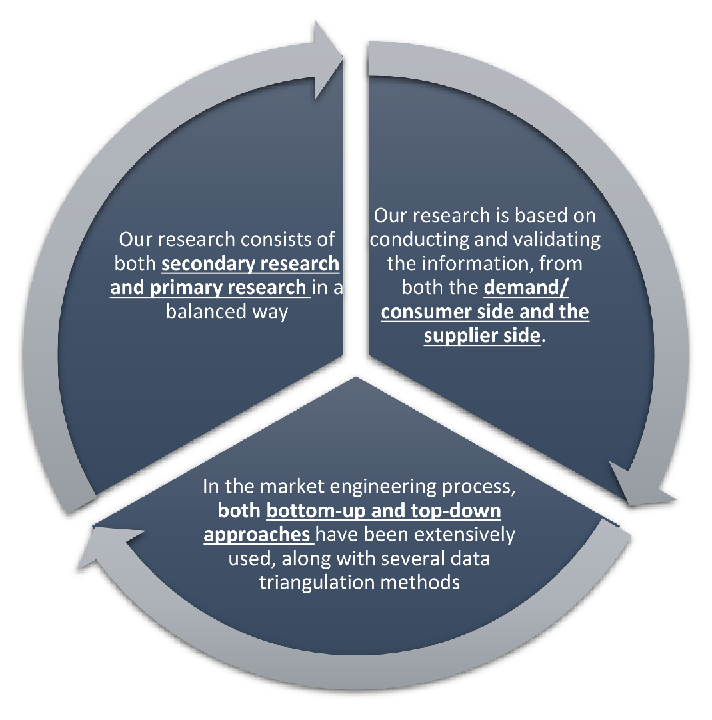
MarketGenics leverages a dedicated industry panel of experts and a comprehensive suite of paid databases to effectively collect, consolidate, and analyze market intelligence.
Our approach has consistently proven to be reliable and effective in generating accurate market insights, identifying key industry trends, and uncovering emerging business opportunities.
Through both primary and secondary research, we capture and analyze critical company-level data such as manufacturing footprints, including technical centers, R&D facilities, sales offices, and headquarters.
Our expert panel further enhances our ability to estimate market size for specific brands based on validated field-level intelligence.
Our data mining techniques incorporate both parametric and non-parametric methods, allowing for structured data collection, sorting, processing, and cleaning.
Demand projections are derived from large-scale data sets analyzed through proprietary algorithms, culminating in robust and reliable market sizing.
Research Approach
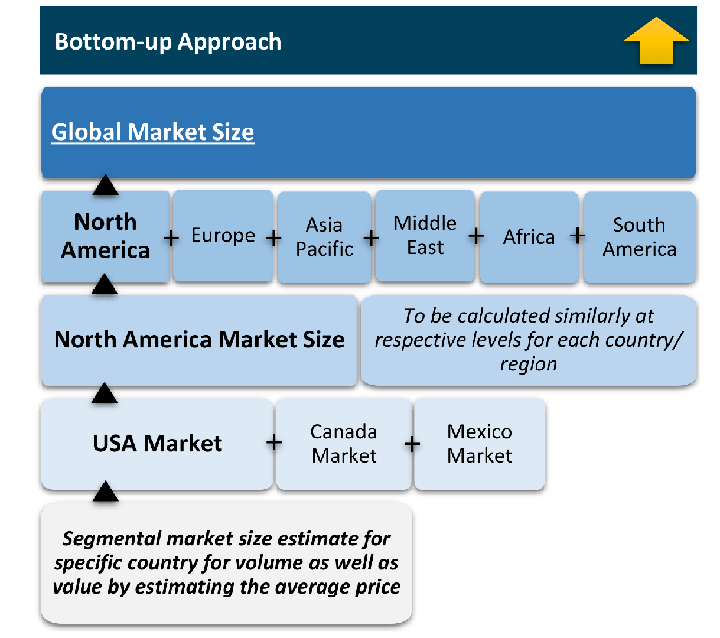
The bottom-up approach builds market estimates by starting with the smallest addressable market units and systematically aggregating them to create comprehensive market size projections.
This method begins with specific, granular data points and builds upward to create the complete market landscape.
Customer Analysis → Segmental Analysis → Geographical Analysis
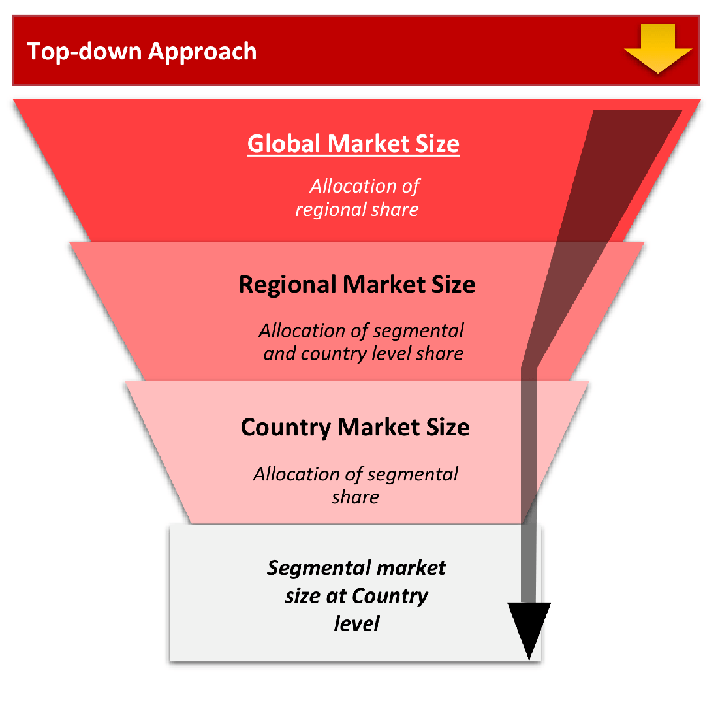
The top-down approach starts with the broadest possible market data and systematically narrows it down through a series of filters and assumptions to arrive at specific market segments or opportunities.
This method begins with the big picture and works downward to increasingly specific market slices.
TAM → SAM → SOM
Research Methods
Desk / Secondary Research
While analysing the market, we extensively study secondary sources, directories, and databases to identify and collect information useful for this technical, market-oriented, and commercial report. Secondary sources that we utilize are not only the public sources, but it is a combination of Open Source, Associations, Paid Databases, MG Repository & Knowledgebase, and others.
- Company websites, annual reports, financial reports, broker reports, and investor presentations
- National government documents, statistical databases and reports
- News articles, press releases and web-casts specific to the companies operating in the market, Magazines, reports, and others
- We gather information from commercial data sources for deriving company specific data such as segmental revenue, share for geography, product revenue, and others
- Internal and external proprietary databases (industry-specific), relevant patent, and regulatory databases
- Governing Bodies, Government Organizations
- Relevant Authorities, Country-specific Associations for Industries
We also employ the model mapping approach to estimate the product level market data through the players' product portfolio
Primary Research
Primary research/ interviews is vital in analyzing the market. Most of the cases involves paid primary interviews. Primary sources include primary interviews through e-mail interactions, telephonic interviews, surveys as well as face-to-face interviews with the different stakeholders across the value chain including several industry experts.
| Type of Respondents | Number of Primaries |
|---|---|
| Tier 2/3 Suppliers | ~20 |
| Tier 1 Suppliers | ~25 |
| End-users | ~25 |
| Industry Expert/ Panel/ Consultant | ~30 |
| Total | ~100 |
MG Knowledgebase
• Repository of industry blog, newsletter and case studies
• Online platform covering detailed market reports, and company profiles
Forecasting Factors and Models
Forecasting Factors
- Historical Trends – Past market patterns, cycles, and major events that shaped how markets behave over time. Understanding past trends helps predict future behavior.
- Industry Factors – Specific characteristics of the industry like structure, regulations, and innovation cycles that affect market dynamics.
- Macroeconomic Factors – Economic conditions like GDP growth, inflation, and employment rates that affect how much money people have to spend.
- Demographic Factors – Population characteristics like age, income, and location that determine who can buy your product.
- Technology Factors – How quickly people adopt new technology and how much technology infrastructure exists.
- Regulatory Factors – Government rules, laws, and policies that can help or restrict market growth.
- Competitive Factors – Analyzing competition structure such as degree of competition and bargaining power of buyers and suppliers.
Forecasting Models / Techniques
Multiple Regression Analysis
- Identify and quantify factors that drive market changes
- Statistical modeling to establish relationships between market drivers and outcomes
Time Series Analysis – Seasonal Patterns
- Understand regular cyclical patterns in market demand
- Advanced statistical techniques to separate trend, seasonal, and irregular components
Time Series Analysis – Trend Analysis
- Identify underlying market growth patterns and momentum
- Statistical analysis of historical data to project future trends
Expert Opinion – Expert Interviews
- Gather deep industry insights and contextual understanding
- In-depth interviews with key industry stakeholders
Multi-Scenario Development
- Prepare for uncertainty by modeling different possible futures
- Creating optimistic, pessimistic, and most likely scenarios
Time Series Analysis – Moving Averages
- Sophisticated forecasting for complex time series data
- Auto-regressive integrated moving average models with seasonal components
Econometric Models
- Apply economic theory to market forecasting
- Sophisticated economic models that account for market interactions
Expert Opinion – Delphi Method
- Harness collective wisdom of industry experts
- Structured, multi-round expert consultation process
Monte Carlo Simulation
- Quantify uncertainty and probability distributions
- Thousands of simulations with varying input parameters
Research Analysis
Our research framework is built upon the fundamental principle of validating market intelligence from both demand and supply perspectives. This dual-sided approach ensures comprehensive market understanding and reduces the risk of single-source bias.
Demand-Side Analysis: We understand end-user/application behavior, preferences, and market needs along with the penetration of the product for specific application.
Supply-Side Analysis: We estimate overall market revenue, analyze the segmental share along with industry capacity, competitive landscape, and market structure.
Validation & Evaluation
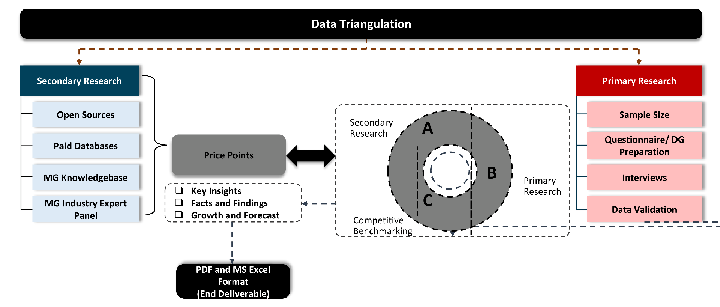
Data triangulation is a validation technique that uses multiple methods, sources, or perspectives to examine the same research question, thereby increasing the credibility and reliability of research findings. In market research, triangulation serves as a quality assurance mechanism that helps identify and minimize bias, validate assumptions, and ensure accuracy in market estimates.
- Data Source Triangulation – Using multiple data sources to examine the same phenomenon
- Methodological Triangulation – Using multiple research methods to study the same research question
- Investigator Triangulation – Using multiple researchers or analysts to examine the same data
- Theoretical Triangulation – Using multiple theoretical perspectives to interpret the same data
Custom Market Research Services
We will customise the research for you, in case the report listed above does not meet your requirements.
Get 10% Free Customisation