Smart Construction Equipment Market Size, Share & Trends Analysis Report by Equipment Type (Excavators, Loaders, Bulldozers, Cranes, Dump Trucks, Motor Graders, Compactors & Rollers, Concrete Equipment, Backhoe Loaders, Telehandlers, Others), Technology, Automation Level, Propulsion Type, Application, End-Use Industry and Geography (North America, Europe, Asia Pacific, Middle East, Africa and South America) – Global Industry Data, Trends and Forecasts, 2026–2035
|
|
|
Segmental Data Insights |
|
|
Demand Trends |
|
|
Competitive Landscape |
|
|
Strategic Development |
|
|
Future Outlook & Opportunities |
|
Smart-Construction-Equipment-Market Size, Share, and Growth
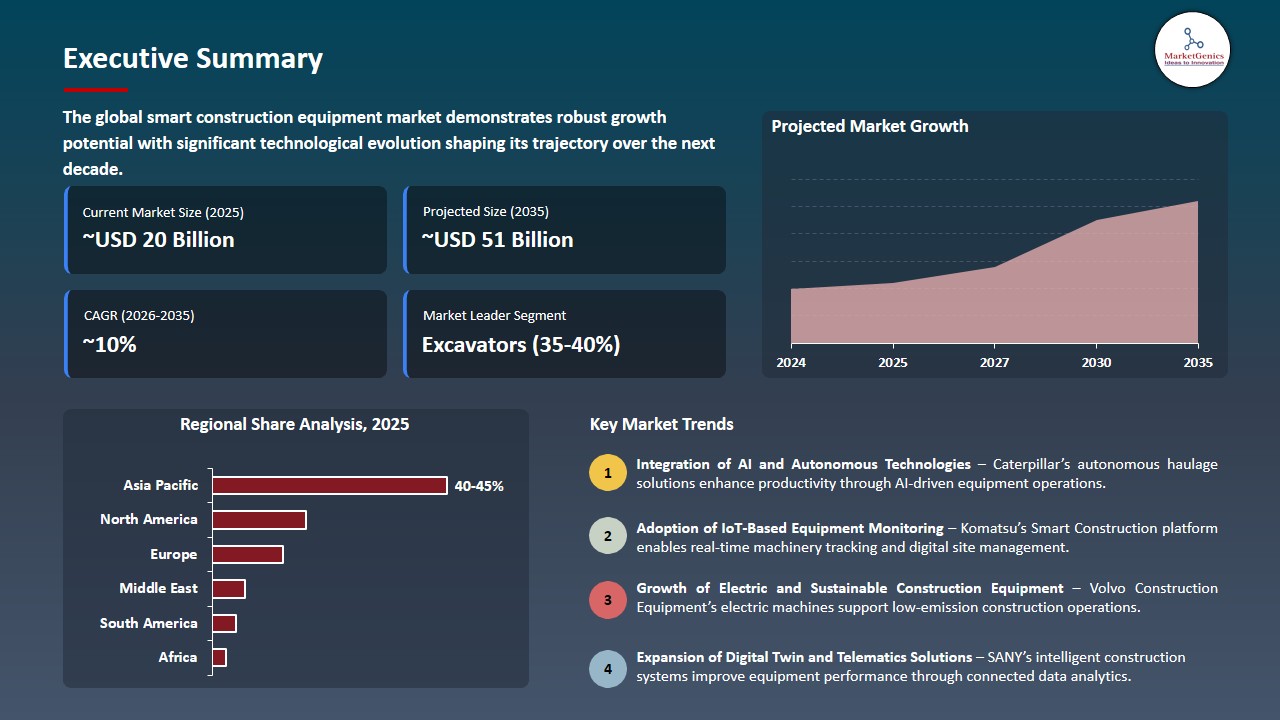
The global smart construction equipment market is exhibiting strong growth, with an estimated value of USD 20.4 billion in 2025 and USD 51.2 billion by 2035, achieving a CAGR of 9.6%, during the forecast period. North America is the fastest-growing smart construction equipment market due to rapid adoption of autonomous equipment, advanced telematics, infrastructure modernization projects, labor shortages, and strong investments by construction companies in digitalization and smart machinery solutions.
“By embedding autonomy into construction workflows, we’re reshaping the industry to achieve safer jobsites, better jobs and easy precision that redefines productivity for the modern jobsite,” said Caterpillar Chief Technology Officer Jaime Mineart.
Accelerating adoption of autonomous and AI-enabled smart construction equipment to address labor shortages and enhance productivity. Construction companies are increasingly investing in connected machines to boost safety and efficiency in the work. For instance, in January 2026, Caterpillar introduced next-generation autonomous construction machines and the Cat AI Assistant, bringing the power of AI and machine learning to all of Caterpillar's equipment fleets to improve jobsite productivity and decision-making. The smart construction equipment market is experiencing rapid growth due to the increasing use of autonomous and AI-powered equipment.
Moreover, the smart construction equipment market is expected to see a significant increase in the demand for sustainable and electrified construction equipment, which is driving the market expansion. For instance, in April 2026, Volvo Construction Equipment launched the A30 Electric and A40 Electric articulated haulers, which demonstrate the growing demand for emission-free construction machinery in the mining and quarry sector. The increasing use of electric equipment in construction is driving the trend of smart construction equipment with low emissions and promoting market growth in the long term.
Key adjacent opportunities for the global smart construction equipment market include autonomous construction technology platforms, construction telematics and fleet management software, electric and battery systems for heavy equipment, construction robotics and drone-based site monitoring, and predictive maintenance and equipment analytics solutions. The segments are leveraging digitalization, automation and sustainability trends within the construction industry. The adjacent markets are growing to open up new avenues of revenue and drive innovation in the global smart construction equipment market.
 Smart Construction Equipment Market Dynamics and Trends
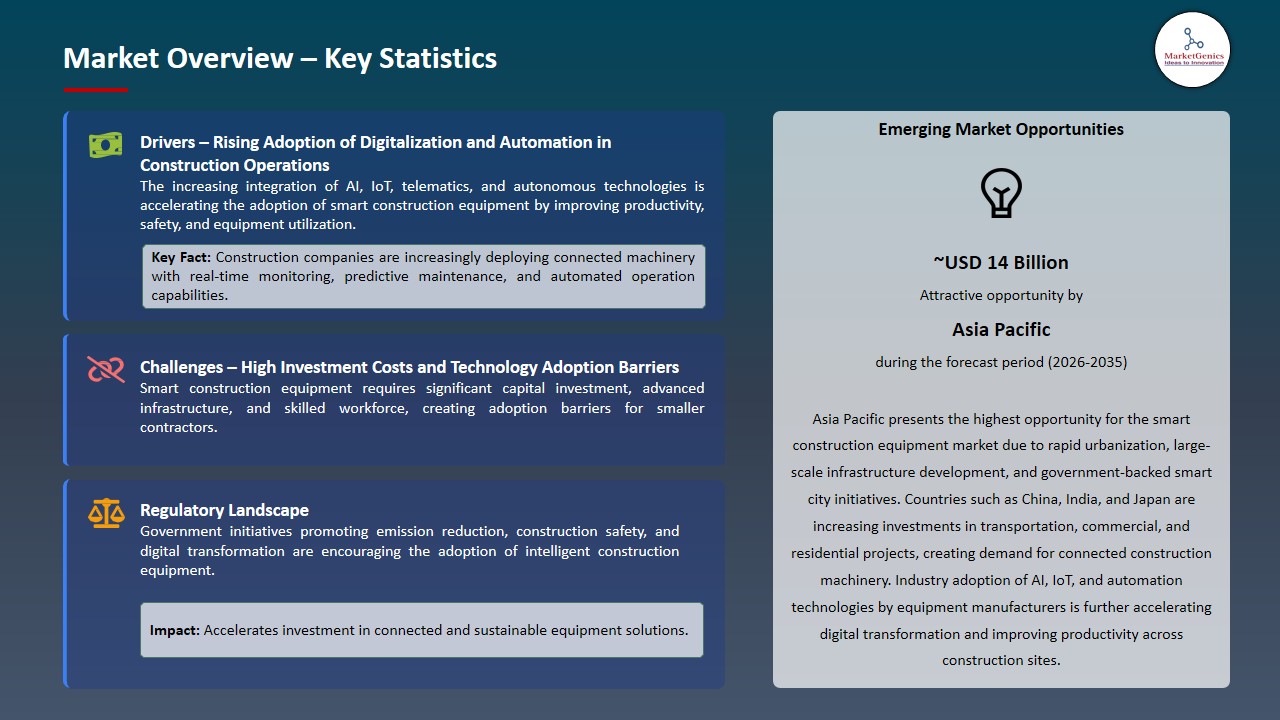
Driver: Expansion of Connected Construction Ecosystems Creates New Digital Revenue Opportunities
- Smart construction equipment manufacturers can leverage the development of connected construction ecosystems to diversify beyond equipment sales and build recurring revenues from data-driven services and software.
- Construction firms are increasingly turning to digital platforms, which combine machine data and site analytics to provide improved visibility and decision-making. For instance, in March 2026, Komatsu enhanced its Smart Construction solutions by integrating its machinery with office-based project management systems, allowing construction sites to monitor progress in real time, collaborate remotely, and optimize their workflows with data.
- The growth of connected construction platforms is creating new service-based business models and boosting longer-term market growth potential.
Restraint: High Capital Investment Requirements Limit Adoption Among Small Construction Contractors Worldwide
- The adoption of smart construction equipment necessitates a significant initial investment in sophisticated sensors, telematics platforms, machine guidance systems, autonomous technologies, and software integration services. Small and medium-sized contractors sometimes struggle to justify these expenses since project profits are still vulnerable to finance costs and unpredictable equipment utilization rates.
- The cost burden extends beyond equipment acquisition to include operator training, software subscriptions, cybersecurity management, and periodic technology upgrades, significantly increasing total ownership costs. This challenge is particularly pronounced in emerging economies, where contractors continue relying on conventional machinery due to lower purchase prices and abundant labor availability.
- Intelligent machinery offers productivity and efficiency gains, but its high cost of ownership and premium pricing prevent broad adoption, particularly among smaller construction enterprises with limited capital budgets.
Opportunity: Electrification and Remote Operations Create New Revenue Streams for Manufacturers
- The combination of electrification, 5G connectivity, and remote operation technologies is presenting great opportunity for smart construction equipment manufacturers. Machinery with reduced emissions and lower operating costs, as well as safer to operate in hazardous conditions, is increasingly being required by construction companies. Electric and remotely controlled equipment also helps to meet sustainability goals and ensure regulatory compliance.
- In May 2026, SANY also announced the commercialization of 5G remote-controlled excavators, unmanned paving-roller fleets, and the first 1000 electric excavators, highlighting the company's achievements in the field of intelligent and low-emission construction technology.
- The innovations are opening up new avenues in mining, infrastructure and urban construction, and offering manufacturers new revenue streams of digital services, remote fleet management, and autonomous equipment solutions.
Key Trend: Artificial Intelligence Integrated Jobsite Ecosystems Transform Equipment Productivity and Safety
- AI is becoming a key feature of the global smart construction equipment market with its ability to interpret operational data, support operators, and automate jobsite operations.
- Manufacturers are incorporating AI features into the gear to improve collision avoidance, predictive maintenance, diagnostics, and real-time operational decision-making. For instance, in January 2026, Doosan Bobcat unveiled Jobsite Companion, the first AI feature on machine for the industry, as part of its Service offering.AI and sophisticated operator awareness technologies.
- The industry is increasingly moving beyond connected machines toward intelligent ecosystems that combine software, sensors, automation, and digital twins into a unified operating environment. These innovations are enhancing fleet coordination, minimizing unexpected downtime, and reshaping productivity and safety metrics on construction sites.
- AI-powered ecosystems are bringing construction equipment to life as intelligent productivity platforms that make autonomous decisions and predictively operate.
Smart Construction Equipment Market Analysis and Segmental Data
Excavators Dominate Global Smart Construction Equipment Market
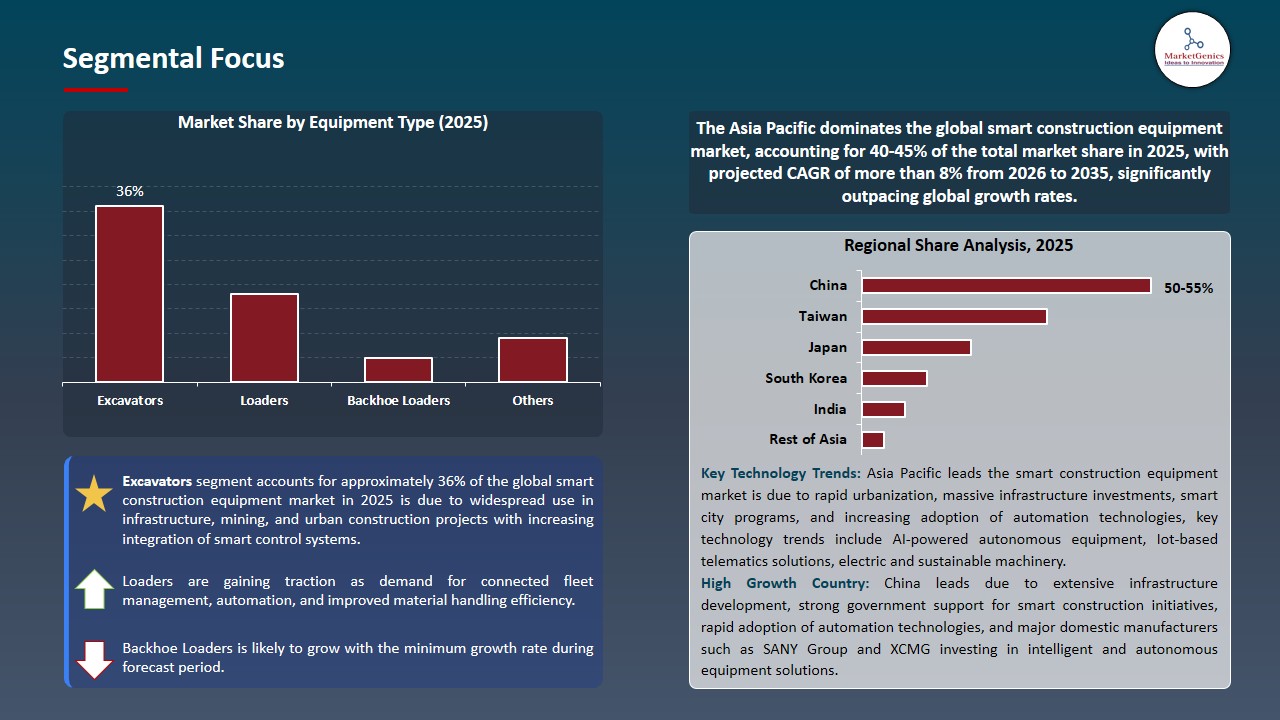
- The excavators segment dominates the global smart construction equipment market owing to its versatility in applications like earthmoving, trenching, demolition, mining, and road construction. They are widely deployed in infrastructure and urban development projects, and are the biggest equipment category that integrates telematics, machine control systems, automation and predictive maintenance.
- For instance, in March 2026 Caterpillar introduced a new Cat 319 hydraulic excavator built on its Next Generation platform that will enhance productivity, operating cost and machine efficiency.
- The use rate of excavators is high, and the application of their autonomy and digitalization keeps driving the growth of its share in the global smart construction equipment market.
Asia Pacific Leads Global Smart Construction Equipment Market Demand
- Asia Pacific leads the smart construction equipment market is expected to witness the highest growth, owing to the increasing adoption of electric and self-driving construction machinery in mining and infrastructure projects. The increasing demand for low-emission and intelligent equipment is driving Asia Pacific infrastructure developers and mining operators to improve their productivity, safety and operational efficiency.
- In addition, localized manufacturing and regional distribution networks of equipment are growing. Manufacturers are distributing smart equipment via a growing dealer network and localized products. For instance, in April 2026, Hitachi Construction Machinery introduced its WIXIM brand targeted at Southeast Asia to provide OEM products for Southeast Asia.
- The developments are driving the Asia Pacific market to become a key player in the global market for smart construction equipment, which is gradually becoming intelligent and low-emission.
Smart Construction Equipment Market Ecosystem
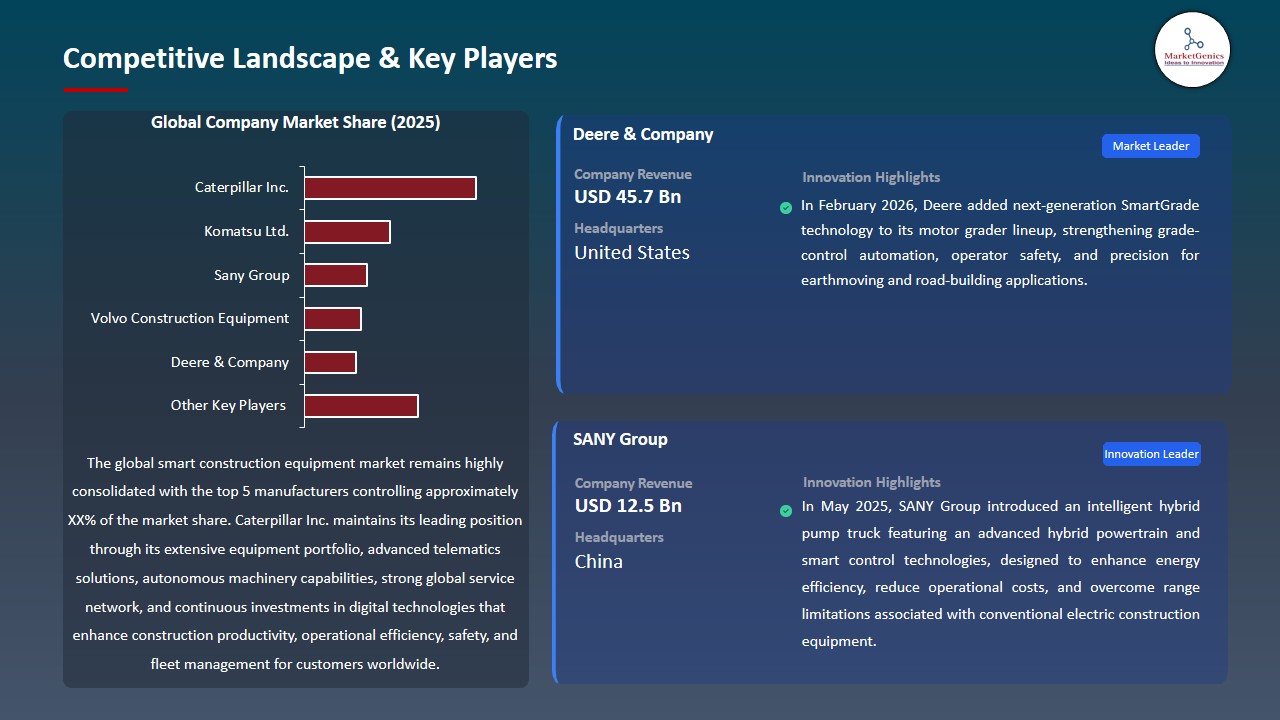
The global smart construction equipment market is highly consolidated, with leading manufacturers such as Caterpillar, Komatsu, SANY Group, Volvo Construction Equipment, and Deere & Company dominating through advanced telematics, autonomous operation systems, artificial intelligence, and connected fleet management platforms. These companies rely on digital solutions and far-reaching distribution networks to hold their ground in infrastructure, mining and urban construction applications.
Niche technologies like autonomy in haulage, e-Excavators, machine control, and AI-driven predictive maintenance platforms are gaining traction among key players. For instance, Caterpillar and Komatsu are developing autonomous machines, and SANY is developing 5G remote-controlled construction machinery, while Volvo Construction Equipment is progressing with the development of commercial electric compact machines and intelligent fleet connectivity solutions.
The global smart construction equipment market is witnessing a rapid surge in autonomous, connected, and electrified equipment investments, driving innovations and fortifying the competitive market.
 Recent Development and Strategic Overview:
- In April 2025, Komatsu Ltd. launched the PC220LCi-12 hydraulic excavator, incorporating advanced ICT, intelligent machine control, and Smart Construction technologies to enhance operational precision, productivity, automation capabilities, and workforce efficiency across construction applications.
- In January 2025, Caterpillar Inc. introduced next-generation telehandlers (TH0642, TH0842, TH1055, and TH1255) featuring Product Link Elite telematics, remote diagnostics, enhanced visibility systems, and advanced safety features to improve jobsite efficiency and equipment performance.
Report Scope
|
Detail |
|
|
Market Size in 2025 |
USD 20.4 Bn |
|
Market Forecast Value in 2035 |
USD 51.2 Bn |
|
Growth Rate (CAGR) |
9.6% |
|
Forecast Period |
2026 – 2035 |
|
Historical Data Available for |
2021 – 2024 |
|
Market Size Units |
US$ Billion for Value Thousand Units for Volume |
|
Report Format |
Electronic (PDF) + Excel |
|
North America |
Europe |
Asia Pacific |
Middle East |
Africa |
South America |
|
|
|
|
|
|
|
Companies Covered |
|||||
|
|||||
Smart Construction Equipment Market Segmentation and Highlights
|
Segment |
Sub-segment |
|
Smart Construction Equipment Market, By Equipment Type |
|
|
Smart Construction Equipment Market, By Technology |
|
|
Smart Construction Equipment Market, By Automation Level |
|
|
Smart Construction Equipment Market, By Propulsion Type |
|
|
Smart Construction Equipment Market, By Application |
|
|
Smart Construction Equipment Market, By End-Use Industry |
|
Frequently Asked Questions
Table of Contents
- 1. Research Methodology and Assumptions
- 1.1. Definitions
- 1.2. Research Design and Approach
- 1.3. Data Collection Methods
- 1.4. Base Estimates and Calculations
- 1.5. Forecasting Models
- 1.5.1. Key Forecast Factors & Impact Analysis
- 1.6. Secondary Research
- 1.6.1. Open Sources
- 1.6.2. Paid Databases
- 1.6.3. Associations
- 1.7. Primary Research
- 1.7.1. Primary Sources
- 1.7.2. Primary Interviews with Stakeholders across Ecosystem
- 2. Executive Summary
- 2.1. Global Smart Construction Equipment Market Outlook
- 2.1.1. Smart Construction Equipment Market Size (Volume - Thousand Units and Value - US$ Bn), and Forecasts, 2021-2035
- 2.1.2. Compounded Annual Growth Rate Analysis
- 2.1.3. Growth Opportunity Analysis
- 2.1.4. Segmental Share Analysis
- 2.1.5. Geographical Share Analysis
- 2.2. Market Analysis and Facts
- 2.3. Supply-Demand Analysis
- 2.4. Competitive Benchmarking
- 2.5. Go-to- Market Strategy
- 2.5.1. Customer/ End-use Industry Assessment
- 2.5.2. Growth Opportunity Data, 2026-2035
- 2.5.2.1. Regional Data
- 2.5.2.2. Country Data
- 2.5.2.3. Segmental Data
- 2.5.3. Identification of Potential Market Spaces
- 2.5.4. GAP Analysis
- 2.5.5. Potential Attractive Price Points
- 2.5.6. Prevailing Market Risks & Challenges
- 2.5.7. Preferred Sales & Marketing Strategies
- 2.5.8. Key Recommendations and Analysis
- 2.5.9. A Way Forward
- 2.1. Global Smart Construction Equipment Market Outlook
- 3. Industry Data and Premium Insights
- 3.1. Global Industrial Machinery Industry Overview, 2025
- 3.1.1. Industrial Machinery Ecosystem Analysis
- 3.1.2. Key Trends for Industrial Machinery Industry
- 3.1.3. Regional Distribution for Industrial Machinery Industry
- 3.2. Supplier Customer Data
- 3.3. Technology Roadmap and Developments
- 3.4. Trade Analysis
- 3.4.1. Import & Export Analysis, 2025
- 3.4.2. Top Importing Countries
- 3.4.3. Top Exporting Countries
- 3.5. Trump Tariff Impact Analysis
- 3.5.1. Manufacturer
- 3.5.1.1. Based on the component & Raw material
- 3.5.2. Supply Chain
- 3.5.3. End Consumer
- 3.5.1. Manufacturer
- 3.6. Raw Material Analysis
- 3.1. Global Industrial Machinery Industry Overview, 2025
- 4. Market Overview
- 4.1. Market Dynamics
- 4.1.1. Drivers
- 4.1.1.1. AI-enabled equipment adoption improves productivity and operational efficiency
- 4.1.1.2. Smart city projects increase demand for connected machinery
- 4.1.1.3. Automation reduces labor dependency and enhances construction safety
- 4.1.2. Restraints
- 4.1.2.1. High equipment costs limit adoption among smaller firms
- 4.1.2.2. Lack of skilled operators restricts technology implementation
- 4.1.1. Drivers
- 4.2. Key Trend Analysis
- 4.3. Regulatory Framework
- 4.3.1. Key Regulations, Norms, and Subsidies, by Key Countries
- 4.3.2. Tariffs and Standards
- 4.3.3. Impact Analysis of Regulations on the Market
- 4.4. Value Chain Analysis
- 4.4.1. Component Suppliers
- 4.4.2. Equipment Manufacturers
- 4.4.3. Technology Integrators
- 4.4.4. Dealers & Distributors
- 4.4.5. End-users
- 4.5. Cost Structure Analysis
- 4.5.1. Parameter’s Share for Cost Associated
- 4.5.2. COGP vs COGS
- 4.5.3. Profit Margin Analysis
- 4.6. Pricing Analysis
- 4.6.1. Regional Pricing Analysis
- 4.6.2. Segmental Pricing Trends
- 4.6.3. Factors Influencing Pricing
- 4.7. Porter’s Five Forces Analysis
- 4.8. PESTEL Analysis
- 4.9. Global Smart Construction Equipment Market Demand
- 4.9.1. Historical Market Size – in Volume (Thousand Units) & Value (US$ Bn), 2020-2024
- 4.9.2. Current and Future Market Size – in Volume (Thousand Units) & Value (US$ Bn), 2026–2035
- 4.9.2.1. Y-o-Y Growth Trends
- 4.9.2.2. Absolute $ Opportunity Assessment
- 4.1. Market Dynamics
- 5. Competition Landscape
- 5.1. Competition structure
- 5.1.1. Fragmented v/s consolidated
- 5.2. Company Share Analysis, 2025
- 5.2.1. Global Company Market Share
- 5.2.2. By Region
- 5.2.2.1. North America
- 5.2.2.2. Europe
- 5.2.2.3. Asia Pacific
- 5.2.2.4. Middle East
- 5.2.2.5. Africa
- 5.2.2.6. South America
- 5.3. Product Comparison Matrix
- 5.3.1. Specifications
- 5.3.2. Market Positioning
- 5.3.3. Pricing
- 5.1. Competition structure
- 6. Global Smart Construction Equipment Market Analysis, by Equipment Type
- 6.1. Key Segment Analysis
- 6.2. Smart Construction Equipment Market Size (Volume - Thousand Units and Value - US$ Bn), Analysis, and Forecasts, by Equipment Type, 2021-2035
- 6.2.1. Excavators
- 6.2.2. Loaders
- 6.2.3. Bulldozers
- 6.2.4. Cranes
- 6.2.5. Dump Trucks
- 6.2.6. Motor Graders
- 6.2.7. Compactors & Rollers
- 6.2.8. Concrete Equipment
- 6.2.9. Backhoe Loaders
- 6.2.10. Telehandlers
- 6.2.11. Others
- 7. Global Smart Construction Equipment Market Analysis, by Technology
- 7.1. Key Segment Analysis
- 7.2. Smart Construction Equipment Market Size (Volume - Thousand Units and Value - US$ Bn), Analysis, and Forecasts, by Technology, 2021-2035
- 7.2.1. Internet of Things (IoT)
- 7.2.2. Artificial Intelligence (AI)
- 7.2.3. Machine Learning (ML)
- 7.2.4. Telematics
- 7.2.5. GPS/GNSS Systems
- 7.2.6. Computer Vision
- 7.2.7. Autonomous Navigation Systems
- 7.2.8. Digital Twin Technology
- 7.2.9. Others
- 8. Global Smart Construction Equipment Market Analysis, by Automation Level
- 8.1. Key Segment Analysis
- 8.2. Smart Construction Equipment Market Size (Volume - Thousand Units and Value - US$ Bn), Analysis, and Forecasts, by Automation Level, 2021-2035
- 8.2.1. Semi-Autonomous Equipment
- 8.2.2. Fully Autonomous Equipment
- 9. Global Smart Construction Equipment Market Analysis, by Propulsion Type
- 9.1. Key Segment Analysis
- 9.2. Smart Construction Equipment Market Size (Volume - Thousand Units and Value - US$ Bn), Analysis, and Forecasts, by Propulsion Type, 2021-2035
- 9.2.1. Diesel-Powered Equipment
- 9.2.2. Electric Equipment
- 10. Global Smart Construction Equipment Market Analysis, by Application
- 10.1. Key Segment Analysis
- 10.2. Smart Construction Equipment Market Size (Volume - Thousand Units and Value - US$ Bn), Analysis, and Forecasts, by Application, 2021-2035
- 10.2.1. Earthmoving
- 10.2.2. Material Handling
- 10.2.3. Road Construction
- 10.2.4. Demolition
- 10.2.5. Excavation & Mining
- 10.2.6. Lifting & Hoisting
- 10.2.7. Site Preparation
- 10.2.8. Concrete Handling
- 10.2.9. Others
- 11. Global Smart Construction Equipment Market Analysis, by End-Use Industry
- 11.1. Key Segment Analysis
- 11.2. Smart Construction Equipment Market Size (Volume - Thousand Units and Value - US$ Bn), Analysis, and Forecasts, by End-Use Industry, 2021-2035
- 11.2.1. Residential Construction
- 11.2.2. Commercial Construction
- 11.2.3. Industrial Construction
- 11.2.4. Infrastructure Development
- 11.2.5. Mining
- 11.2.6. Oil & Gas
- 11.2.7. Utilities
- 11.2.8. Others
- 12. Global Smart Construction Equipment Market Analysis, by Region
- 12.1. Key Findings
- 12.2. Smart Construction Equipment Market Size (Volume - Thousand Units and Value - US$ Bn), Analysis, and Forecasts, by Region, 2021-2035
- 12.2.1. North America
- 12.2.2. Europe
- 12.2.3. Asia Pacific
- 12.2.4. Middle East
- 12.2.5. Africa
- 12.2.6. South America
- 13. North America Smart Construction Equipment Market Analysis
- 13.1. Key Segment Analysis
- 13.2. Regional Snapshot
- 13.3. North America Smart Construction Equipment Market Size (Volume - Thousand Units and Value - US$ Bn), Analysis, and Forecasts, 2021-2035
- 13.3.1. Equipment Type
- 13.3.2. Technology
- 13.3.3. Automation Level
- 13.3.4. Propulsion Type
- 13.3.5. Application
- 13.3.6. End-Use Industry
- 13.3.7. Country
- 13.3.7.1. USA
- 13.3.7.2. Canada
- 13.3.7.3. Mexico
- 13.4. USA Smart Construction Equipment Market
- 13.4.1. Country Segmental Analysis
- 13.4.2. Equipment Type
- 13.4.3. Technology
- 13.4.4. Automation Level
- 13.4.5. Propulsion Type
- 13.4.6. Application
- 13.4.7. End-Use Industry
- 13.5. Canada Smart Construction Equipment Market
- 13.5.1. Country Segmental Analysis
- 13.5.2. Equipment Type
- 13.5.3. Technology
- 13.5.4. Automation Level
- 13.5.5. Propulsion Type
- 13.5.6. Application
- 13.5.7. End-Use Industry
- 13.6. Mexico Smart Construction Equipment Market
- 13.6.1. Country Segmental Analysis
- 13.6.2. Equipment Type
- 13.6.3. Technology
- 13.6.4. Automation Level
- 13.6.5. Propulsion Type
- 13.6.6. Application
- 13.6.7. End-Use Industry
- 14. Europe Smart Construction Equipment Market Analysis
- 14.1. Key Segment Analysis
- 14.2. Regional Snapshot
- 14.3. Europe Smart Construction Equipment Market Size (Volume - Thousand Units and Value - US$ Bn), Analysis, and Forecasts, 2021-2035
- 14.3.1. Equipment Type
- 14.3.2. Technology
- 14.3.3. Automation Level
- 14.3.4. Propulsion Type
- 14.3.5. Application
- 14.3.6. End-Use Industry
- 14.3.7. Country
- 14.3.7.1. Germany
- 14.3.7.2. United Kingdom
- 14.3.7.3. France
- 14.3.7.4. Italy
- 14.3.7.5. Spain
- 14.3.7.6. Netherlands
- 14.3.7.7. Nordic Countries
- 14.3.7.8. Poland
- 14.3.7.9. Russia & CIS
- 14.3.7.10. Rest of Europe
- 14.4. Germany Smart Construction Equipment Market
- 14.4.1. Country Segmental Analysis
- 14.4.2. Equipment Type
- 14.4.3. Technology
- 14.4.4. Automation Level
- 14.4.5. Propulsion Type
- 14.4.6. Application
- 14.4.7. End-Use Industry
- 14.5. United Kingdom Smart Construction Equipment Market
- 14.5.1. Country Segmental Analysis
- 14.5.2. Equipment Type
- 14.5.3. Technology
- 14.5.4. Automation Level
- 14.5.5. Propulsion Type
- 14.5.6. Application
- 14.5.7. End-Use Industry
- 14.6. France Smart Construction Equipment Market
- 14.6.1. Country Segmental Analysis
- 14.6.2. Equipment Type
- 14.6.3. Technology
- 14.6.4. Automation Level
- 14.6.5. Propulsion Type
- 14.6.6. Application
- 14.6.7. End-Use Industry
- 14.7. Italy Smart Construction Equipment Market
- 14.7.1. Country Segmental Analysis
- 14.7.2. Equipment Type
- 14.7.3. Technology
- 14.7.4. Automation Level
- 14.7.5. Propulsion Type
- 14.7.6. Application
- 14.7.7. End-Use Industry
- 14.8. Spain Smart Construction Equipment Market
- 14.8.1. Country Segmental Analysis
- 14.8.2. Equipment Type
- 14.8.3. Technology
- 14.8.4. Automation Level
- 14.8.5. Propulsion Type
- 14.8.6. Application
- 14.8.7. End-Use Industry
- 14.9. Netherlands Smart Construction Equipment Market
- 14.9.1. Country Segmental Analysis
- 14.9.2. Equipment Type
- 14.9.3. Technology
- 14.9.4. Automation Level
- 14.9.5. Propulsion Type
- 14.9.6. Application
- 14.9.7. End-Use Industry
- 14.10. Nordic Countries Smart Construction Equipment Market
- 14.10.1. Country Segmental Analysis
- 14.10.2. Equipment Type
- 14.10.3. Technology
- 14.10.4. Automation Level
- 14.10.5. Propulsion Type
- 14.10.6. Application
- 14.10.7. End-Use Industry
- 14.11. Poland Smart Construction Equipment Market
- 14.11.1. Country Segmental Analysis
- 14.11.2. Equipment Type
- 14.11.3. Technology
- 14.11.4. Automation Level
- 14.11.5. Propulsion Type
- 14.11.6. Application
- 14.11.7. End-Use Industry
- 14.12. Russia & CIS Smart Construction Equipment Market
- 14.12.1. Country Segmental Analysis
- 14.12.2. Equipment Type
- 14.12.3. Technology
- 14.12.4. Automation Level
- 14.12.5. Propulsion Type
- 14.12.6. Application
- 14.12.7. End-Use Industry
- 14.13. Rest of Europe Smart Construction Equipment Market
- 14.13.1. Country Segmental Analysis
- 14.13.2. Equipment Type
- 14.13.3. Technology
- 14.13.4. Automation Level
- 14.13.5. Propulsion Type
- 14.13.6. Application
- 14.13.7. End-Use Industry
- 15. Asia Pacific Smart Construction Equipment Market Analysis
- 15.1. Key Segment Analysis
- 15.2. Regional Snapshot
- 15.3. Asia Pacific Smart Construction Equipment Market Size (Volume - Thousand Units and Value - US$ Bn), Analysis, and Forecasts, 2021-2035
- 15.3.1. Equipment Type
- 15.3.2. Technology
- 15.3.3. Automation Level
- 15.3.4. Propulsion Type
- 15.3.5. Application
- 15.3.6. End-Use Industry
- 15.3.7. Country
- 15.3.7.1. China
- 15.3.7.2. India
- 15.3.7.3. Japan
- 15.3.7.4. South Korea
- 15.3.7.5. Australia and New Zealand
- 15.3.7.6. Indonesia
- 15.3.7.7. Malaysia
- 15.3.7.8. Thailand
- 15.3.7.9. Vietnam
- 15.3.7.10. Rest of Asia Pacific
- 15.4. China Smart Construction Equipment Market
- 15.4.1. Country Segmental Analysis
- 15.4.2. Equipment Type
- 15.4.3. Technology
- 15.4.4. Automation Level
- 15.4.5. Propulsion Type
- 15.4.6. Application
- 15.4.7. End-Use Industry
- 15.5. India Smart Construction Equipment Market
- 15.5.1. Country Segmental Analysis
- 15.5.2. Equipment Type
- 15.5.3. Technology
- 15.5.4. Automation Level
- 15.5.5. Propulsion Type
- 15.5.6. Application
- 15.5.7. End-Use Industry
- 15.6. Japan Smart Construction Equipment Market
- 15.6.1. Country Segmental Analysis
- 15.6.2. Equipment Type
- 15.6.3. Technology
- 15.6.4. Automation Level
- 15.6.5. Propulsion Type
- 15.6.6. Application
- 15.6.7. End-Use Industry
- 15.7. South Korea Smart Construction Equipment Market
- 15.7.1. Country Segmental Analysis
- 15.7.2. Equipment Type
- 15.7.3. Technology
- 15.7.4. Automation Level
- 15.7.5. Propulsion Type
- 15.7.6. Application
- 15.7.7. End-Use Industry
- 15.8. Australia and New Zealand Smart Construction Equipment Market
- 15.8.1. Country Segmental Analysis
- 15.8.2. Equipment Type
- 15.8.3. Technology
- 15.8.4. Automation Level
- 15.8.5. Propulsion Type
- 15.8.6. Application
- 15.8.7. End-Use Industry
- 15.9. Indonesia Smart Construction Equipment Market
- 15.9.1. Country Segmental Analysis
- 15.9.2. Equipment Type
- 15.9.3. Technology
- 15.9.4. Automation Level
- 15.9.5. Propulsion Type
- 15.9.6. Application
- 15.9.7. End-Use Industry
- 15.10. Malaysia Smart Construction Equipment Market
- 15.10.1. Country Segmental Analysis
- 15.10.2. Equipment Type
- 15.10.3. Technology
- 15.10.4. Automation Level
- 15.10.5. Propulsion Type
- 15.10.6. Application
- 15.10.7. End-Use Industry
- 15.11. Thailand Smart Construction Equipment Market
- 15.11.1. Country Segmental Analysis
- 15.11.2. Equipment Type
- 15.11.3. Technology
- 15.11.4. Automation Level
- 15.11.5. Propulsion Type
- 15.11.6. Application
- 15.11.7. End-Use Industry
- 15.12. Vietnam Smart Construction Equipment Market
- 15.12.1. Country Segmental Analysis
- 15.12.2. Equipment Type
- 15.12.3. Technology
- 15.12.4. Automation Level
- 15.12.5. Propulsion Type
- 15.12.6. Application
- 15.12.7. End-Use Industry
- 15.13. Rest of Asia Pacific Smart Construction Equipment Market
- 15.13.1. Country Segmental Analysis
- 15.13.2. Equipment Type
- 15.13.3. Technology
- 15.13.4. Automation Level
- 15.13.5. Propulsion Type
- 15.13.6. Application
- 15.13.7. End-Use Industry
- 16. Middle East Smart Construction Equipment Market Analysis
- 16.1. Key Segment Analysis
- 16.2. Regional Snapshot
- 16.3. Middle East Smart Construction Equipment Market Size (Volume - Thousand Units and Value - US$ Bn), Analysis, and Forecasts, 2021-2035
- 16.3.1. Equipment Type
- 16.3.2. Technology
- 16.3.3. Automation Level
- 16.3.4. Propulsion Type
- 16.3.5. Application
- 16.3.6. End-Use Industry
- 16.3.7. Country
- 16.3.7.1. Turkey
- 16.3.7.2. UAE
- 16.3.7.3. Saudi Arabia
- 16.3.7.4. Israel
- 16.3.7.5. Rest of Middle East
- 16.4. Turkey Smart Construction Equipment Market
- 16.4.1. Country Segmental Analysis
- 16.4.2. Equipment Type
- 16.4.3. Technology
- 16.4.4. Automation Level
- 16.4.5. Propulsion Type
- 16.4.6. Application
- 16.4.7. End-Use Industry
- 16.5. UAE Smart Construction Equipment Market
- 16.5.1. Country Segmental Analysis
- 16.5.2. Equipment Type
- 16.5.3. Technology
- 16.5.4. Automation Level
- 16.5.5. Propulsion Type
- 16.5.6. Application
- 16.5.7. End-Use Industry
- 16.6. Saudi Arabia Smart Construction Equipment Market
- 16.6.1. Country Segmental Analysis
- 16.6.2. Equipment Type
- 16.6.3. Technology
- 16.6.4. Automation Level
- 16.6.5. Propulsion Type
- 16.6.6. Application
- 16.6.7. End-Use Industry
- 16.7. Israel Smart Construction Equipment Market
- 16.7.1. Country Segmental Analysis
- 16.7.2. Equipment Type
- 16.7.3. Technology
- 16.7.4. Automation Level
- 16.7.5. Propulsion Type
- 16.7.6. Application
- 16.7.7. End-Use Industry
- 16.8. Rest of Middle East Smart Construction Equipment Market
- 16.8.1. Country Segmental Analysis
- 16.8.2. Equipment Type
- 16.8.3. Technology
- 16.8.4. Automation Level
- 16.8.5. Propulsion Type
- 16.8.6. Application
- 16.8.7. End-Use Industry
- 17. Africa Smart Construction Equipment Market Analysis
- 17.1. Key Segment Analysis
- 17.2. Regional Snapshot
- 17.3. Africa Smart Construction Equipment Market Size (Volume - Thousand Units and Value - US$ Bn), Analysis, and Forecasts, 2021-2035
- 17.3.1. Equipment Type
- 17.3.2. Technology
- 17.3.3. Automation Level
- 17.3.4. Propulsion Type
- 17.3.5. Application
- 17.3.6. End-Use Industry
- 17.3.7. Country
- 17.3.7.1. South Africa
- 17.3.7.2. Egypt
- 17.3.7.3. Nigeria
- 17.3.7.4. Algeria
- 17.3.7.5. Rest of Africa
- 17.4. South Africa Smart Construction Equipment Market
- 17.4.1. Country Segmental Analysis
- 17.4.2. Equipment Type
- 17.4.3. Technology
- 17.4.4. Automation Level
- 17.4.5. Propulsion Type
- 17.4.6. Application
- 17.4.7. End-Use Industry
- 17.5. Egypt Smart Construction Equipment Market
- 17.5.1. Country Segmental Analysis
- 17.5.2. Equipment Type
- 17.5.3. Technology
- 17.5.4. Automation Level
- 17.5.5. Propulsion Type
- 17.5.6. Application
- 17.5.7. End-Use Industry
- 17.6. Nigeria Smart Construction Equipment Market
- 17.6.1. Country Segmental Analysis
- 17.6.2. Equipment Type
- 17.6.3. Technology
- 17.6.4. Automation Level
- 17.6.5. Propulsion Type
- 17.6.6. Application
- 17.6.7. End-Use Industry
- 17.7. Algeria Smart Construction Equipment Market
- 17.7.1. Country Segmental Analysis
- 17.7.2. Equipment Type
- 17.7.3. Technology
- 17.7.4. Automation Level
- 17.7.5. Propulsion Type
- 17.7.6. Application
- 17.7.7. End-Use Industry
- 17.8. Rest of Africa Smart Construction Equipment Market
- 17.8.1. Country Segmental Analysis
- 17.8.2. Equipment Type
- 17.8.3. Technology
- 17.8.4. Automation Level
- 17.8.5. Propulsion Type
- 17.8.6. Application
- 17.8.7. End-Use Industry
- 18. South America Smart Construction Equipment Market Analysis
- 18.1. Key Segment Analysis
- 18.2. Regional Snapshot
- 18.3. South America Smart Construction Equipment Market Size (Volume - Thousand Units and Value - US$ Bn), Analysis, and Forecasts, 2021-2035
- 18.3.1. Equipment Type
- 18.3.2. Technology
- 18.3.3. Automation Level
- 18.3.4. Propulsion Type
- 18.3.5. Application
- 18.3.6. End-Use Industry
- 18.3.7. Country
- 18.3.7.1. Brazil
- 18.3.7.2. Argentina
- 18.3.7.3. Rest of South America
- 18.4. Brazil Smart Construction Equipment Market
- 18.4.1. Country Segmental Analysis
- 18.4.2. Equipment Type
- 18.4.3. Technology
- 18.4.4. Automation Level
- 18.4.5. Propulsion Type
- 18.4.6. Application
- 18.4.7. End-Use Industry
- 18.5. Argentina Smart Construction Equipment Market
- 18.5.1. Country Segmental Analysis
- 18.5.2. Equipment Type
- 18.5.3. Technology
- 18.5.4. Automation Level
- 18.5.5. Propulsion Type
- 18.5.6. Application
- 18.5.7. End-Use Industry
- 18.6. Rest of South America Smart Construction Equipment Market
- 18.6.1. Country Segmental Analysis
- 18.6.2. Equipment Type
- 18.6.3. Technology
- 18.6.4. Automation Level
- 18.6.5. Propulsion Type
- 18.6.6. Application
- 18.6.7. End-Use Industry
- 19. Key Players/ Company Profile
- 19.1. CASE Construction Equipment
- 19.1.1. Company Details/ Overview
- 19.1.2. Company Financials
- 19.1.3. Key Customers and Competitors
- 19.1.4. Business/ Industry Portfolio
- 19.1.5. Product Portfolio/ Specification Details
- 19.1.6. Pricing Data
- 19.1.7. Strategic Overview
- 19.1.8. Recent Developments
- 19.2. Caterpillar Inc.
- 19.3. Deere & Company
- 19.4. Doosan Bobcat Inc.
- 19.5. Hitachi Construction Machinery Co., Ltd.
- 19.6. JCB
- 19.7. Komatsu Ltd.
- 19.8. Kubota Corporation
- 19.9. Liebherr Group
- 19.10. Manitou Group
- 19.11. Sany Group
- 19.12. Volvo Construction Equipment
- 19.13. Wirtgen Group
- 19.14. Zoomlion Heavy Industry Science & Technology Co., Ltd.
- 19.15. Other Key Players
- 19.1. CASE Construction Equipment
Note* - This is just tentative list of players. While providing the report, we will cover more number of players based on their revenue and share for each geography
Research Design
Our research design integrates both demand-side and supply-side analysis through a balanced combination of primary and secondary research methodologies. By utilizing both bottom-up and top-down approaches alongside rigorous data triangulation methods, we deliver robust market intelligence that supports strategic decision-making.
MarketGenics' comprehensive research design framework ensures the delivery of accurate, reliable, and actionable market intelligence. Through the integration of multiple research approaches, rigorous validation processes, and expert analysis, we provide our clients with the insights needed to make informed strategic decisions and capitalize on market opportunities.
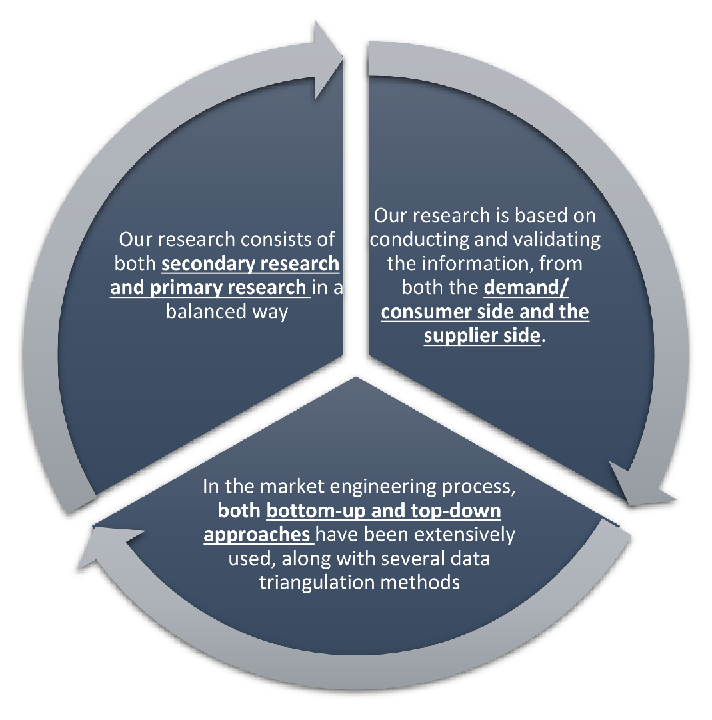
MarketGenics leverages a dedicated industry panel of experts and a comprehensive suite of paid databases to effectively collect, consolidate, and analyze market intelligence.
Our approach has consistently proven to be reliable and effective in generating accurate market insights, identifying key industry trends, and uncovering emerging business opportunities.
Through both primary and secondary research, we capture and analyze critical company-level data such as manufacturing footprints, including technical centers, R&D facilities, sales offices, and headquarters.
Our expert panel further enhances our ability to estimate market size for specific brands based on validated field-level intelligence.
Our data mining techniques incorporate both parametric and non-parametric methods, allowing for structured data collection, sorting, processing, and cleaning.
Demand projections are derived from large-scale data sets analyzed through proprietary algorithms, culminating in robust and reliable market sizing.
Research Approach
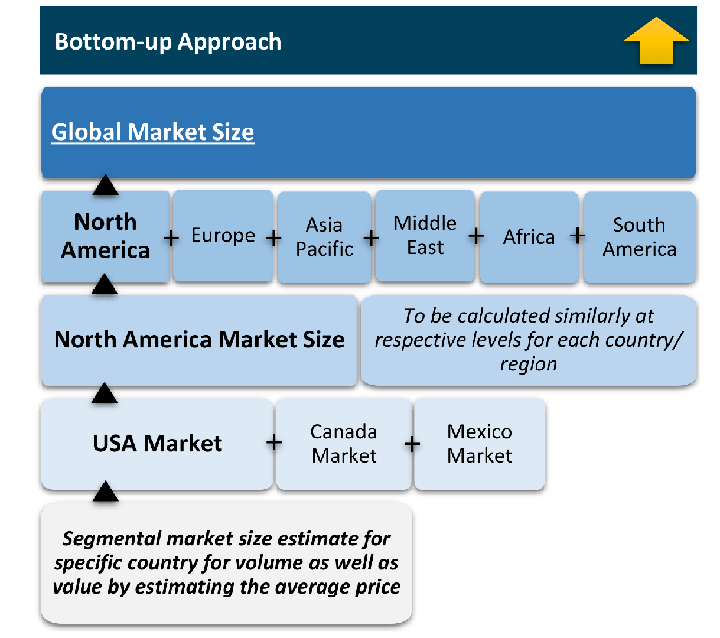
The bottom-up approach builds market estimates by starting with the smallest addressable market units and systematically aggregating them to create comprehensive market size projections.
This method begins with specific, granular data points and builds upward to create the complete market landscape.
Customer Analysis → Segmental Analysis → Geographical Analysis
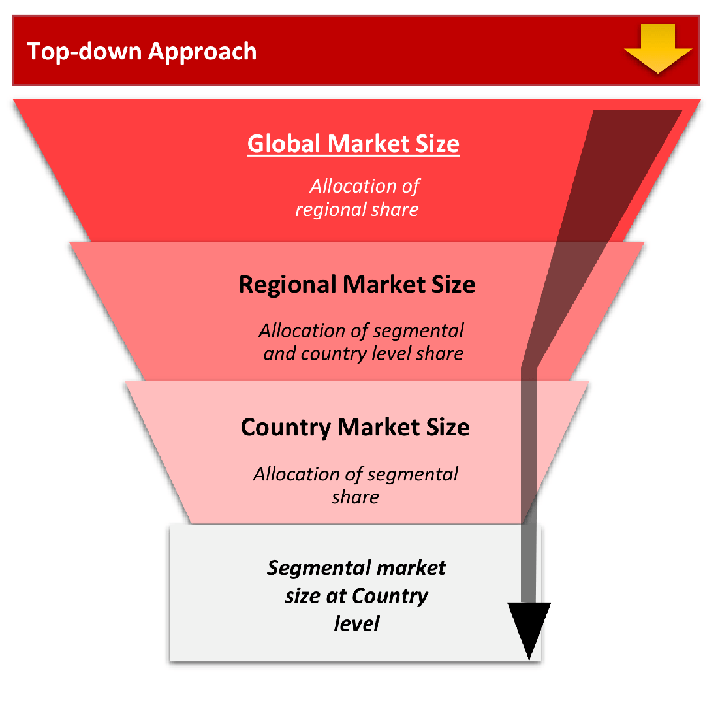
The top-down approach starts with the broadest possible market data and systematically narrows it down through a series of filters and assumptions to arrive at specific market segments or opportunities.
This method begins with the big picture and works downward to increasingly specific market slices.
TAM → SAM → SOM
Research Methods
Desk / Secondary Research
While analysing the market, we extensively study secondary sources, directories, and databases to identify and collect information useful for this technical, market-oriented, and commercial report. Secondary sources that we utilize are not only the public sources, but it is a combination of Open Source, Associations, Paid Databases, MG Repository & Knowledgebase, and others.
- Company websites, annual reports, financial reports, broker reports, and investor presentations
- National government documents, statistical databases and reports
- News articles, press releases and web-casts specific to the companies operating in the market, Magazines, reports, and others
- We gather information from commercial data sources for deriving company specific data such as segmental revenue, share for geography, product revenue, and others
- Internal and external proprietary databases (industry-specific), relevant patent, and regulatory databases
- Governing Bodies, Government Organizations
- Relevant Authorities, Country-specific Associations for Industries
We also employ the model mapping approach to estimate the product level market data through the players' product portfolio
Primary Research
Primary research/ interviews is vital in analyzing the market. Most of the cases involves paid primary interviews. Primary sources include primary interviews through e-mail interactions, telephonic interviews, surveys as well as face-to-face interviews with the different stakeholders across the value chain including several industry experts.
| Type of Respondents | Number of Primaries |
|---|---|
| Tier 2/3 Suppliers | ~20 |
| Tier 1 Suppliers | ~25 |
| End-users | ~25 |
| Industry Expert/ Panel/ Consultant | ~30 |
| Total | ~100 |
MG Knowledgebase
• Repository of industry blog, newsletter and case studies
• Online platform covering detailed market reports, and company profiles
Forecasting Factors and Models
Forecasting Factors
- Historical Trends – Past market patterns, cycles, and major events that shaped how markets behave over time. Understanding past trends helps predict future behavior.
- Industry Factors – Specific characteristics of the industry like structure, regulations, and innovation cycles that affect market dynamics.
- Macroeconomic Factors – Economic conditions like GDP growth, inflation, and employment rates that affect how much money people have to spend.
- Demographic Factors – Population characteristics like age, income, and location that determine who can buy your product.
- Technology Factors – How quickly people adopt new technology and how much technology infrastructure exists.
- Regulatory Factors – Government rules, laws, and policies that can help or restrict market growth.
- Competitive Factors – Analyzing competition structure such as degree of competition and bargaining power of buyers and suppliers.
Forecasting Models / Techniques
Multiple Regression Analysis
- Identify and quantify factors that drive market changes
- Statistical modeling to establish relationships between market drivers and outcomes
Time Series Analysis – Seasonal Patterns
- Understand regular cyclical patterns in market demand
- Advanced statistical techniques to separate trend, seasonal, and irregular components
Time Series Analysis – Trend Analysis
- Identify underlying market growth patterns and momentum
- Statistical analysis of historical data to project future trends
Expert Opinion – Expert Interviews
- Gather deep industry insights and contextual understanding
- In-depth interviews with key industry stakeholders
Multi-Scenario Development
- Prepare for uncertainty by modeling different possible futures
- Creating optimistic, pessimistic, and most likely scenarios
Time Series Analysis – Moving Averages
- Sophisticated forecasting for complex time series data
- Auto-regressive integrated moving average models with seasonal components
Econometric Models
- Apply economic theory to market forecasting
- Sophisticated economic models that account for market interactions
Expert Opinion – Delphi Method
- Harness collective wisdom of industry experts
- Structured, multi-round expert consultation process
Monte Carlo Simulation
- Quantify uncertainty and probability distributions
- Thousands of simulations with varying input parameters
Research Analysis
Our research framework is built upon the fundamental principle of validating market intelligence from both demand and supply perspectives. This dual-sided approach ensures comprehensive market understanding and reduces the risk of single-source bias.
Demand-Side Analysis: We understand end-user/application behavior, preferences, and market needs along with the penetration of the product for specific application.
Supply-Side Analysis: We estimate overall market revenue, analyze the segmental share along with industry capacity, competitive landscape, and market structure.
Validation & Evaluation
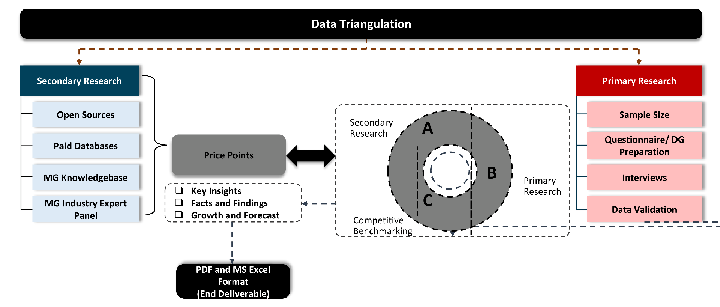
Data triangulation is a validation technique that uses multiple methods, sources, or perspectives to examine the same research question, thereby increasing the credibility and reliability of research findings. In market research, triangulation serves as a quality assurance mechanism that helps identify and minimize bias, validate assumptions, and ensure accuracy in market estimates.
- Data Source Triangulation – Using multiple data sources to examine the same phenomenon
- Methodological Triangulation – Using multiple research methods to study the same research question
- Investigator Triangulation – Using multiple researchers or analysts to examine the same data
- Theoretical Triangulation – Using multiple theoretical perspectives to interpret the same data
Custom Market Research Services
We will customise the research for you, in case the report listed above does not meet your requirements.
Get 10% Free Customisation