Digital Adoption Platforms Market Size, Share & Trends Analysis Report by Offering (Platform/Software, Services), Application Type, End-User Interface, Adoption Layer/Functionality, Integration Type, Deployment Mode, Organization Size, Industry Vertical and Geography (North America, Europe, Asia Pacific, Middle East, Africa and South America) – Global Industry Data, Trends and Forecasts, 2026–2035
|
|
|
Segmental Data Insights |
|
|
Demand Trends |
|
|
Competitive Landscape |
|
|
Strategic Development |
|
|
Future Outlook & Opportunities |
|
Digital-Adoption-Platforms-Market Size, Share, and Growth
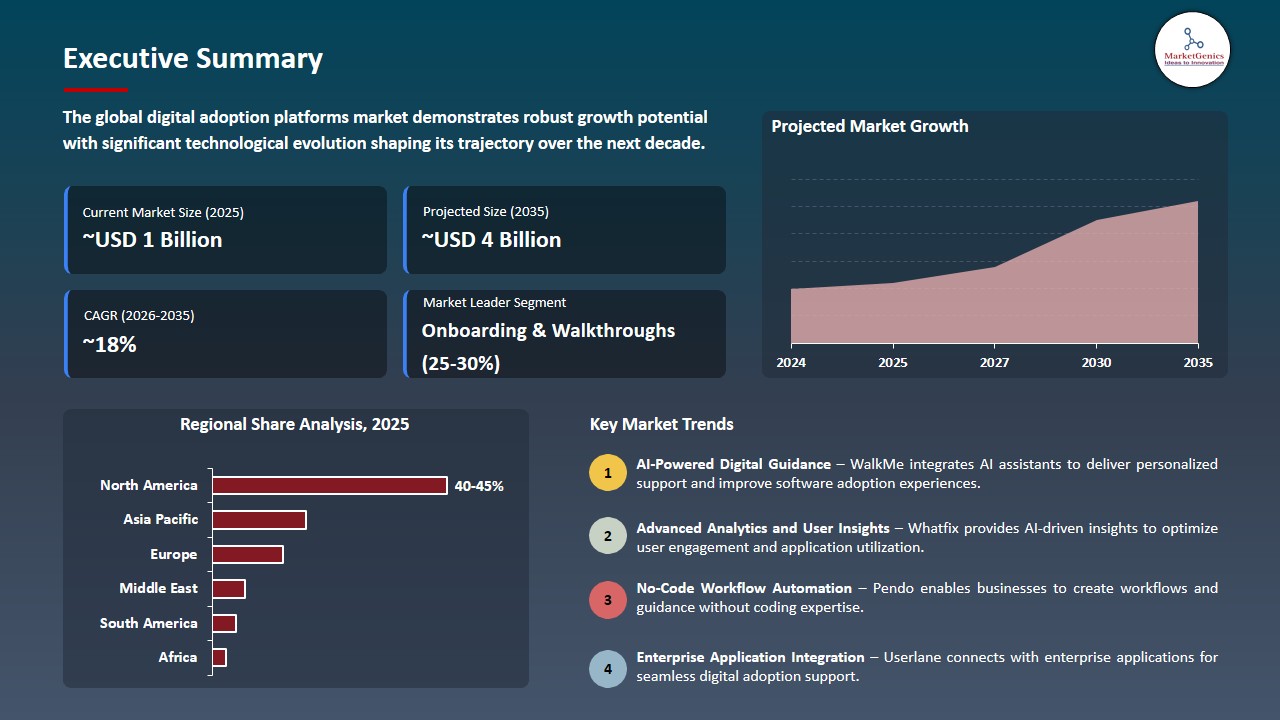
The global digital adoption platforms market is exhibiting strong growth, with an estimated value of USD 0.7 billion in 2025 and USD 3.8 billion by 2035, achieving a CAGR of 18.3%, during the forecast period.
“Enterprises are buying and building AI faster than ever, but adoption is not keeping pace,” said Khadim Batti, Co-founder and CEO of Whatfix. “The real challenge is operationalizing intelligence inside real workflows with governance and measurable outcomes. Digital adoption maturity is no longer optional, it has become the difference between AI ambition and AI outcomes.”
The use of AI-powered workflows and digital transformation projects is driving a surge in demand for digital adoption platforms to boost user productivity, software adoption, and adoption rates. For instance, in March 2026, Whatfix enhanced this trend by launching new enhancements to its AI-native enterprise technology adoption platform that added new AI-powered features to utilize and optimize the value of enterprise applications and AI investments.
Furthermore, the complexity of enterprise software ecosystems creates a demand for contextual guidance, in-app support, and adoption analytics across several applications. For instance, SAP (WalkMe) continues to support this demand through its WalkMe Digital Adoption Platform, which provides AI-powered guidance and automation within SAP workflows to accelerate user proficiency and digital transformation adoption. The increasing complexity of software will drive the digital adoption platforms, as it will provide an increase in user productivity and an improvement in the efficiency of digital transformation.
Adjacent opportunities for the global digital adoption platforms market include AI-powered employee enablement, integration with enterprise SaaS applications, personalized learning platforms, automation-driven workflow optimization, and industry-specific adoption solutions. Growing demand for seamless digital experiences across remote and hybrid workplaces is creating new avenues for digital adoption platform providers to expand capabilities and address diverse enterprise transformation needs. Expansion into adjacent digital experience markets will strengthen digital adoption platform and accelerate enterprise software value realization.
Digital Adoption Platforms Market Dynamics and Trends
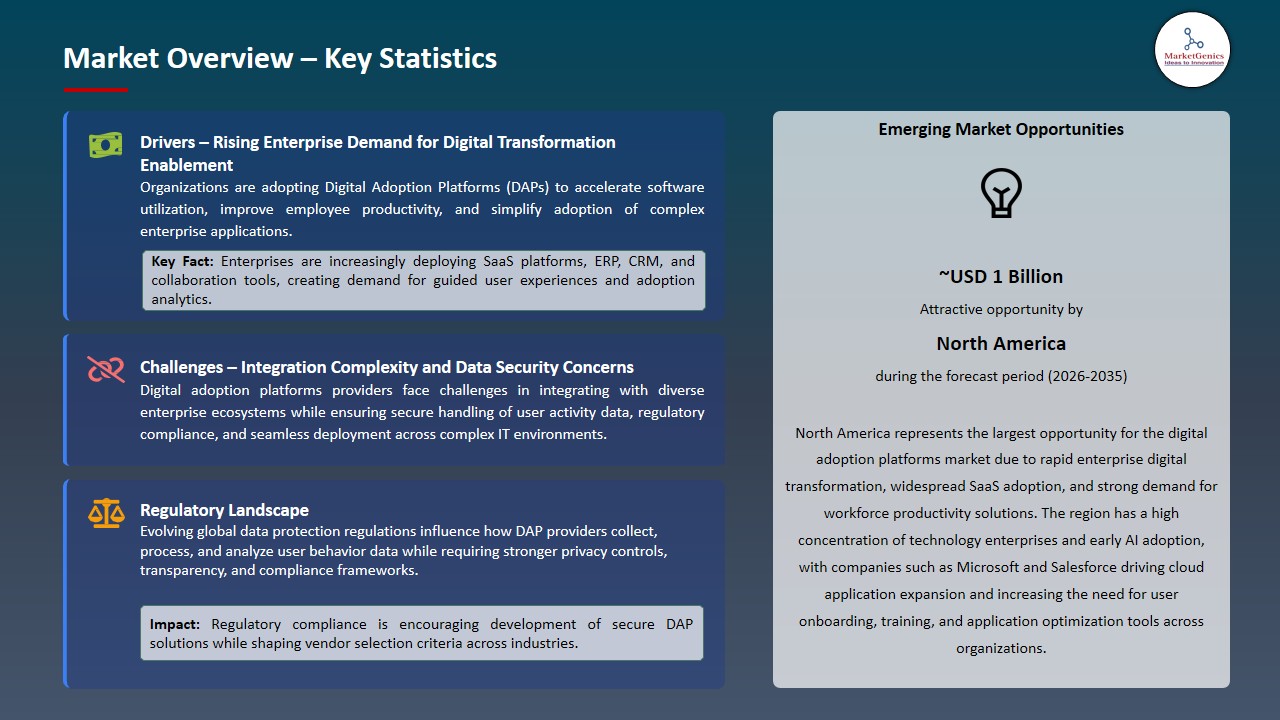
Driver: Accelerating Enterprise AI Integration Increasing Demand for Intelligent Digital Adoption Solutions
- The digital adoption platforms market is growing rapidly as enterprises incorporate AI, cloud-based applications, and intricate digital workflows, and the need for contextual guidance, automation, and real-time user support is rising. In large deployments of new technology, organizations are turning to digital adoption platform solutions to boost employee productivity, increase software utilization and lessen reliance on conventional training approaches.
- The increased convergence of AI-powered analytics and adoption technologies, helping organizations maximize application utilization and speed up transformation efforts across functions. For instances, in April 2026, Pendo announced AI-powered new product features to help organizations optimize user engagement and digital product adoption by enriching their intelligent insights and guidance capabilities.
- The increasing integration of AI-driven capabilities within enterprise software ecosystems is expected to further strengthen demand for intelligent adoption solutions that support continuous learning, workflow optimization, and improved technology utilization.
Restraint: Data Security Concerns and Integration Challenges Across Enterprise Application Ecosystems
- Digital adoption platforms frequently demand access to corporate apps, user activity data, and workflows, raising worries about data privacy, cybersecurity, and integration complexity. For large organizations that have multiple software environments, it can be challenging to integrate digital adoption platform solutions with legacy systems, custom applications and regulated data infrastructures.
- Regulatory requirements and the increasing complexity of governance are challenges to wide-spread digital adoption platform, particularly in regulated industries. For instance, WalkMe enhanced its security and governance capabilities in its Digital Adoption Platform to meet enterprise needs for Access Control, Compliance Management and Secure Digital Adoption for business applications.
- The security and integration challenges could impact enterprise deployments, potentially necessitating digital adoption platform providers to enhance their compliance frameworks, interoperability and data protection capabilities to encourage wider adoption.
Opportunity: Expanding Adoption of Industry-Specific Digital Experience Platforms Across Enterprises
- The increased need for customized digital transformation solutions allows digital adoption platform providers to construct industry-specific platforms targeted to areas such as healthcare, finance, manufacturing, and retail. Businesses need more and more one-to-one direction, workflow automation, and analytics tools that are specific to their operations, not blanket solutions.
- Advancements allow digital adoption platform vendors to provide customized solutions that enhance operational efficiency and technology uptake. For instance, Userlane added more AI-powered assistance functions to extend enterprise digital adoption, tailored to employee-specific guidance and workflow optimization for various business applications.
- The growth in demand for customized digital experiences will spur more vertical-specific solutions on the digital adoption platform market, which will help organizations ramp up software adoption and efficiency in specialized workflows.
Key Trend: AI-Powered Personalization and Autonomous Guidance Transforming Digital Adoption Experiences
- The digital adoption platforms market is moving toward more personalization, predictions, and autonomous support to create an adaptive user experience. Instead of providing simple in-app advice, enterprises are now turning to smart platforms which can study consumer actions, determine gaps in adoption and supply automated help as customers use the application.
- The shift toward “adoption ecosystems” in the industry that leverage AI to continuously evolve and improve engagement strategies based on user interactions. For instance, in September 2025, Whatfix added intelligent automation features to its AI functionality to make personalized digital guidance and boost enterprise application adoption more effective.
- The convergence of generative AI analytics, and automation will be reimagining software adoption and employee enablement in organizations, offering the promise of more responsive, efficient, and personalized digital experiences.
Digital Adoption Platforms Market Analysis and Segmental Data
Onboarding & Walkthroughs Dominate Global Digital Adoption Platforms Market
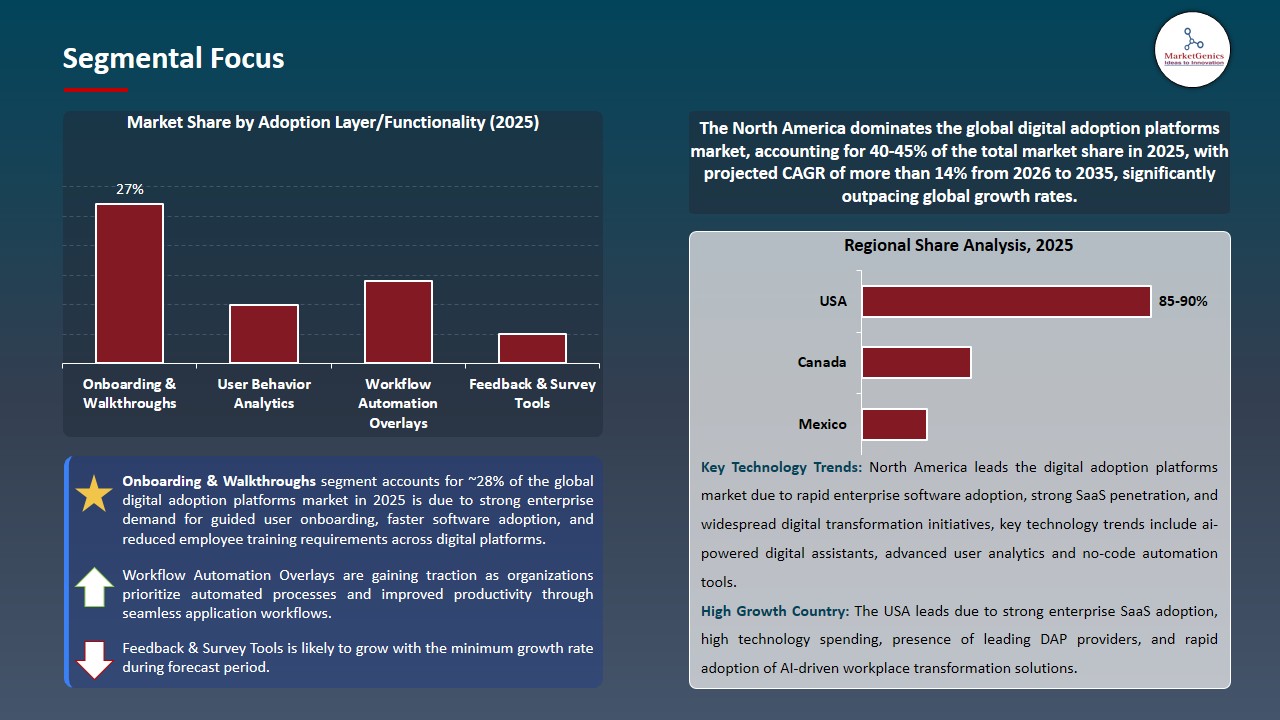
- The onboarding & walkthroughs segment dominates the global digital adoption platforms market because they deliver immediate value for enterprises implementing new software applications. These capabilities enable employees to learn applications directly within their workflow, reduce dependency on traditional training programs, minimize user errors, and improve adoption rates during software deployments.
- For instance, Whatfix's digital adoption platforms provides step-by-step in-app guidance and workflow assistance that helps accelerate employee onboarding and enhance application proficiency. The capabilities as part of its platform offerings, demonstrating the continued importance of guided user experiences in enterprise software adoption.
- Onboarding and walkthrough features will continue to be the leading factors in driving digital adoption platforms adoption as organizations continue to adopt complex digital tools to increase user engagement and software utilization.
North America Leads Global Digital Adoption Platforms Market Demand
- North America leads the digital adoption platforms market is due to its high adoption rate of digital transformation in AI, cloud, and enterprise. The demand to increase software utilization and workforce productivity is driving the growth of the digital adoption platforms market, with North America being the biggest market for this solution. For instance, In March 2026, Whatfix launched AI Roleplay Training in Mirror to enhance interactive learning and personalized digital adoption.
- Furthermore, as enterprise software ecosystems continue to grow more intricate, there's a rising need for digital adoption platforms solutions that offer contextual support, user analytics, and workflow optimization. For instance, Pendo's platform provides user insights, in-app guidance and analytics that help drive application adoption and engagement.
- The digital adoption platforms market will further bolster North America's leading position with advanced digital transformation projects and AI adoption solutions.
Digital Adoption Platforms Market Ecosystem
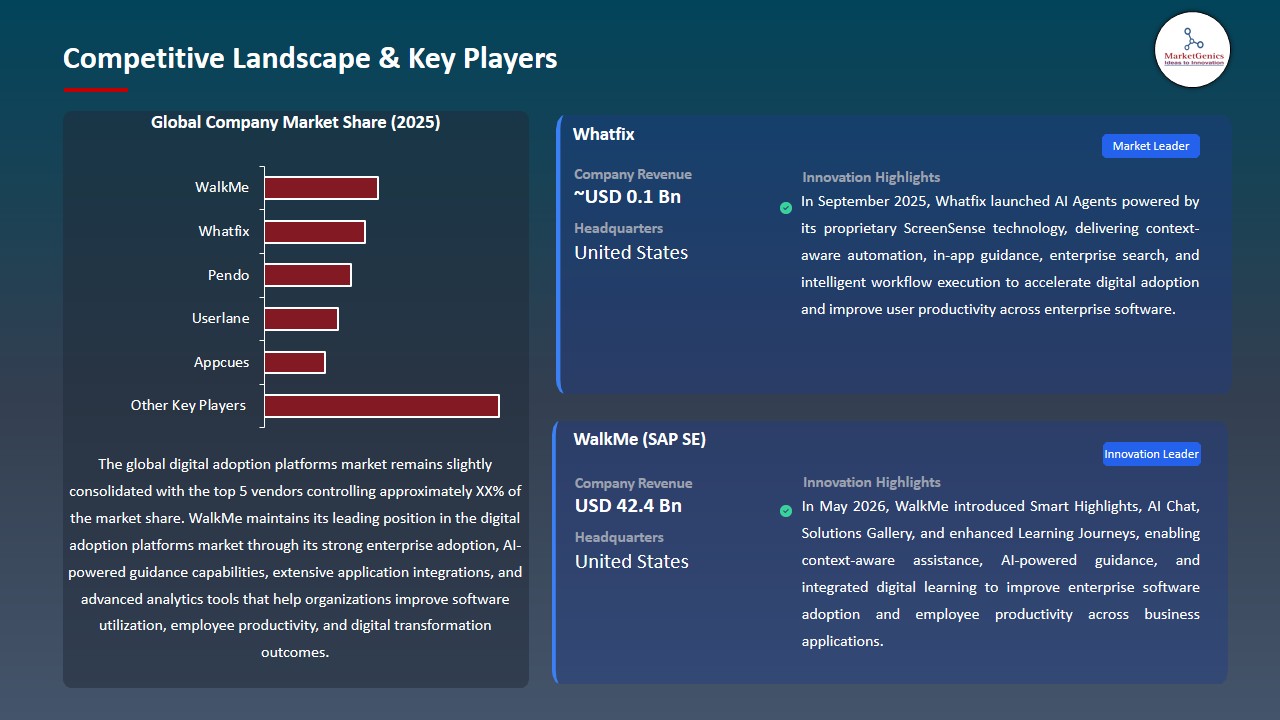
The global digital adoption platforms market is slightly consolidated, with leading companies such as WalkMe, Whatfix, Pendo, Userlane, and Appcues dominating through advanced technologies including artificial intelligence, automation, analytics, and in-app guidance solutions. These companies are strengthening their market position by enabling enterprises to improve software adoption, enhance employee productivity, and optimize digital transformation initiatives across complex application environments.
Key players are developing specialized solutions to address enterprise needs. For instance, WalkMe focuses on AI-powered adoption and workflow automation, Whatfix on AI-driven guidance and training, Pendo on product analytics, and Userlane and Appcues on personalized onboarding and no-code adoption solutions. Continuous innovation in AI, analytics, and automation will strengthen market competitiveness and accelerate enterprise adoption of digital adoption platforms.
 Recent Development and Strategic Overview:
- In December 2025, WalkMe launched Learning Arc, expanded SAP GUI desktop guidance, redesigned editor capabilities, and enhanced contextual AI assistance, strengthening enterprise onboarding, workflow guidance, and digital learning within the flow of work.
- In October 2025, Pendo introduced an Agent Mode interface with AI-powered recommendations, natural language interactions, automation, and enhanced product analytics, enabling organizations to optimize software adoption, user engagement, and digital experiences through intelligent guidance.
Report Scope
|
Detail |
|
|
Market Size in 2025 |
USD 0.7 Bn |
|
Market Forecast Value in 2035 |
USD 3.8 Bn |
|
Growth Rate (CAGR) |
18.3% |
|
Forecast Period |
2026 – 2035 |
|
Historical Data Available for |
2021 – 2024 |
|
Market Size Units |
US$ Billion for Value |
|
Report Format |
Electronic (PDF) + Excel |
|
North America |
Europe |
Asia Pacific |
Middle East |
Africa |
South America |
|
|
|
|
|
|
|
Companies Covered |
|||||
|
|||||
Digital Adoption Platforms Market Segmentation and Highlights
|
Segment |
Sub-segment |
|
Digital Adoption Platforms Market, By Offering |
|
|
Digital Adoption Platforms Market, By Application Type |
|
|
Digital Adoption Platforms Market, By End-User Interface |
|
|
Digital Adoption Platforms Market, By Adoption Layer/Functionality |
|
|
Digital Adoption Platforms Market, By Integration Type |
|
|
Digital Adoption Platforms Market, By Deployment Mode |
|
|
Digital Adoption Platforms Market, By Organization Size |
|
|
Digital Adoption Platforms Market, By Industry Vertical |
|
Frequently Asked Questions
Table of Contents
- 1. Research Methodology and Assumptions
- 1.1. Definitions
- 1.2. Research Design and Approach
- 1.3. Data Collection Methods
- 1.4. Base Estimates and Calculations
- 1.5. Forecasting Models
- 1.5.1. Key Forecast Factors & Impact Analysis
- 1.6. Secondary Research
- 1.6.1. Open Sources
- 1.6.2. Paid Databases
- 1.6.3. Associations
- 1.7. Primary Research
- 1.7.1. Primary Sources
- 1.7.2. Primary Interviews with Stakeholders across Ecosystem
- 2. Executive Summary
- 2.1. Global Digital Adoption Platforms Market Outlook
- 2.1.1. Digital Adoption Platforms Market Size (Value - US$ Bn), and Forecasts, 2021-2035
- 2.1.2. Compounded Annual Growth Rate Analysis
- 2.1.3. Growth Opportunity Analysis
- 2.1.4. Segmental Share Analysis
- 2.1.5. Geographical Share Analysis
- 2.2. Market Analysis and Facts
- 2.3. Supply-Demand Analysis
- 2.4. Competitive Benchmarking
- 2.5. Go-to- Market Strategy
- 2.5.1. Customer/ End-use Industry Assessment
- 2.5.2. Growth Opportunity Data, 2026-2035
- 2.5.2.1. Regional Data
- 2.5.2.2. Country Data
- 2.5.2.3. Segmental Data
- 2.5.3. Identification of Potential Market Spaces
- 2.5.4. GAP Analysis
- 2.5.5. Potential Attractive Price Points
- 2.5.6. Prevailing Market Risks & Challenges
- 2.5.7. Preferred Sales & Marketing Strategies
- 2.5.8. Key Recommendations and Analysis
- 2.5.9. A Way Forward
- 2.1. Global Digital Adoption Platforms Market Outlook
- 3. Industry Data and Premium Insights
- 3.1. Global Information Technology & Media Industry Overview, 2025
- 3.1.1. Information Technology & Media Ecosystem Analysis
- 3.1.2. Key Trends for Information Technology & Media Industry
- 3.1.3. Regional Distribution for Information Technology & Media Industry
- 3.2. Supplier Customer Data
- 3.3. Technology Roadmap and Developments
- 3.1. Global Information Technology & Media Industry Overview, 2025
- 4. Market Overview
- 4.1. Market Dynamics
- 4.1.1. Drivers
- 4.1.1.1. Accelerating digital transformation and software adoption
- 4.1.1.2. Growing demand for AI-driven user guidance
- 4.1.1.3. Increasing need for workforce productivity enhancement
- 4.1.2. Restraints
- 4.1.2.1. High implementation and integration complexities
- 4.1.2.2. Data privacy and security concerns
- 4.1.1. Drivers
- 4.2. Key Trend Analysis
- 4.3. Regulatory Framework
- 4.3.1. Key Regulations, Norms, and Subsidies, by Key Countries
- 4.3.2. Tariffs and Standards
- 4.3.3. Impact Analysis of Regulations on the Market
- 4.4. Ecosystem Analysis
- 4.5. Porter’s Five Forces Analysis
- 4.6. PESTEL Analysis
- 4.7. Global Digital Adoption Platforms Market Demand
- 4.7.1. Historical Market Size – in Value (US$ Bn), 2020-2024
- 4.7.2. Current and Future Market Size – in Value (US$ Bn), 2026–2035
- 4.7.2.1. Y-o-Y Growth Trends
- 4.7.2.2. Absolute $ Opportunity Assessment
- 4.1. Market Dynamics
- 5. Competition Landscape
- 5.1. Competition structure
- 5.1.1. Fragmented v/s consolidated
- 5.2. Company Share Analysis, 2025
- 5.2.1. Global Company Market Share
- 5.2.2. By Region
- 5.2.2.1. North America
- 5.2.2.2. Europe
- 5.2.2.3. Asia Pacific
- 5.2.2.4. Middle East
- 5.2.2.5. Africa
- 5.2.2.6. South America
- 5.3. Product Comparison Matrix
- 5.3.1. Specifications
- 5.3.2. Market Positioning
- 5.3.3. Pricing
- 5.1. Competition structure
- 6. Global Digital Adoption Platforms Market Analysis, by Offering
- 6.1. Key Segment Analysis
- 6.2. Digital Adoption Platforms Market Size (Value - US$ Bn), Analysis, and Forecasts, by Offering, 2021-2035
- 6.2.1. Platform/Software
- 6.2.1.1. No-Code/Low-Code DAP Builders
- 6.2.1.2. In-App Guidance Engines
- 6.2.1.3. Analytics & Reporting Modules
- 6.2.1.4. Content Authoring Tools
- 6.2.2. Services
- 6.2.2.1. Implementation & Integration
- 6.2.2.2. Consulting & Advisory
- 6.2.2.3. Training & Support
- 6.2.2.4. Managed Services
- 6.2.1. Platform/Software
- 7. Global Digital Adoption Platforms Market Analysis, by Application Type
- 7.1. Key Segment Analysis
- 7.2. Digital Adoption Platforms Market Size (Value - US$ Bn), Analysis, and Forecasts, by Application Type, 2021-2035
- 7.2.1. Employee Onboarding & Training
- 7.2.2. Software Adoption & Change Management
- 7.2.3. Customer Onboarding
- 7.2.4. Compliance Training & Certification
- 7.2.5. Sales Enablement
- 7.2.6. IT Help Desk Deflection
- 7.2.7. Data Migration Support
- 7.2.8. Process Standardization
- 8. Global Digital Adoption Platforms Market Analysis, by End-User Interface
- 8.1. Key Segment Analysis
- 8.2. Digital Adoption Platforms Market Size (Value - US$ Bn), Analysis, and Forecasts, by End-User Interface, 2021-2035
- 8.2.1. Web-Based Applications
- 8.2.2. Desktop/Windows Applications
- 8.2.3. Mobile Applications
- 9. Global Digital Adoption Platforms Market Analysis, by Adoption Layer/Functionality
- 9.1. Key Segment Analysis
- 9.2. Digital Adoption Platforms Market Size (Value - US$ Bn), Analysis, and Forecasts, by Adoption Layer/Functionality, 2021-2035
- 9.2.1. Onboarding & Walkthroughs
- 9.2.2. Contextual Guidance/Tooltips
- 9.2.3. In-App Messaging & Announcements
- 9.2.4. Self-Help/Knowledge Base Widgets
- 9.2.5. User Behavior Analytics
- 9.2.6. Workflow Automation Overlays
- 9.2.7. Feedback & Survey Tools
- 10. Global Digital Adoption Platforms Market Analysis, by Integration Type
- 10.1. Key Segment Analysis
- 10.2. Digital Adoption Platforms Market Size (Value - US$ Bn), Analysis, and Forecasts, by Integration Type, 2021-2035
- 10.2.1. CRM Integration
- 10.2.2. ERP Integration
- 10.2.3. HCM/HRIS Integration
- 10.2.4. Proprietary Integration
- 11. Global Digital Adoption Platforms Market Analysis, by Deployment Mode
- 11.1. Key Segment Analysis
- 11.2. Digital Adoption Platforms Market Size (Value - US$ Bn), Analysis, and Forecasts, by Deployment Mode, 2021-2035
- 11.2.1. Cloud/SaaS
- 11.2.1.1. Public Cloud
- 11.2.1.2. Private Cloud
- 11.2.2. On-Premise
- 11.2.1. Cloud/SaaS
- 12. Global Digital Adoption Platforms Market Analysis, by Organization Size
- 12.1. Key Segment Analysis
- 12.2. Digital Adoption Platforms Market Size (Value - US$ Bn), Analysis, and Forecasts, by Organization Size, 2021-2035
- 12.2.1. Large Enterprises
- 12.2.2. Small & Medium Enterprises (SMEs)
- 13. Global Digital Adoption Platforms Market Analysis, by Industry Vertical
- 13.1. Key Segment Analysis
- 13.2. Digital Adoption Platforms Market Size (Value - US$ Bn), Analysis, and Forecasts, by Industry Vertical, 2021-2035
- 13.2.1. BFSI
- 13.2.2. IT & Telecommunications
- 13.2.3. Healthcare & Life Sciences
- 13.2.4. Retail & E-commerce
- 13.2.5. Manufacturing
- 13.2.6. Government & Public Sector
- 13.2.7. Education
- 13.2.8. Energy & Utilities
- 13.2.9. Media & Entertainment
- 13.2.10. Transportation & Logistics
- 13.2.11. Professional Services
- 13.2.12. Real Estate
- 13.2.13. Others
- 14. Global Digital Adoption Platforms Market Analysis, by Region
- 14.1. Key Findings
- 14.2. Digital Adoption Platforms Market Size (Value - US$ Bn), Analysis, and Forecasts, by Region, 2021-2035
- 14.2.1. North America
- 14.2.2. Europe
- 14.2.3. Asia Pacific
- 14.2.4. Middle East
- 14.2.5. Africa
- 14.2.6. South America
- 15. North America Digital Adoption Platforms Market Analysis
- 15.1. Key Segment Analysis
- 15.2. Regional Snapshot
- 15.3. North America Digital Adoption Platforms Market Size (Value - US$ Bn), Analysis, and Forecasts, 2021-2035
- 15.3.1. Offering
- 15.3.2. Application Type
- 15.3.3. End-User Interface
- 15.3.4. Adoption Layer/Functionality
- 15.3.5. Integration Type
- 15.3.6. Deployment Mode
- 15.3.7. Organization Size
- 15.3.8. Industry Vertical
- 15.3.9. Country
- 15.3.9.1. USA
- 15.3.9.2. Canada
- 15.3.9.3. Mexico
- 15.4. USA Digital Adoption Platforms Market
- 15.4.1. Country Segmental Analysis
- 15.4.2. Offering
- 15.4.3. Application Type
- 15.4.4. End-User Interface
- 15.4.5. Adoption Layer/Functionality
- 15.4.6. Integration Type
- 15.4.7. Deployment Mode
- 15.4.8. Organization Size
- 15.4.9. Industry Vertical
- 15.5. Canada Digital Adoption Platforms Market
- 15.5.1. Country Segmental Analysis
- 15.5.2. Offering
- 15.5.3. Application Type
- 15.5.4. End-User Interface
- 15.5.5. Adoption Layer/Functionality
- 15.5.6. Integration Type
- 15.5.7. Deployment Mode
- 15.5.8. Organization Size
- 15.5.9. Industry Vertical
- 15.6. Mexico Digital Adoption Platforms Market
- 15.6.1. Country Segmental Analysis
- 15.6.2. Offering
- 15.6.3. Application Type
- 15.6.4. End-User Interface
- 15.6.5. Adoption Layer/Functionality
- 15.6.6. Integration Type
- 15.6.7. Deployment Mode
- 15.6.8. Organization Size
- 15.6.9. Industry Vertical
- 16. Europe Digital Adoption Platforms Market Analysis
- 16.1. Key Segment Analysis
- 16.2. Regional Snapshot
- 16.3. Europe Digital Adoption Platforms Market Size (Value - US$ Bn), Analysis, and Forecasts, 2021-2035
- 16.3.1. Offering
- 16.3.2. Application Type
- 16.3.3. End-User Interface
- 16.3.4. Adoption Layer/Functionality
- 16.3.5. Integration Type
- 16.3.6. Deployment Mode
- 16.3.7. Organization Size
- 16.3.8. Industry Vertical
- 16.3.9. Country
- 16.3.9.1. Germany
- 16.3.9.2. United Kingdom
- 16.3.9.3. France
- 16.3.9.4. Italy
- 16.3.9.5. Spain
- 16.3.9.6. Netherlands
- 16.3.9.7. Nordic Countries
- 16.3.9.8. Poland
- 16.3.9.9. Russia & CIS
- 16.3.9.10. Rest of Europe
- 16.4. Germany Digital Adoption Platforms Market
- 16.4.1. Country Segmental Analysis
- 16.4.2. Offering
- 16.4.3. Application Type
- 16.4.4. End-User Interface
- 16.4.5. Adoption Layer/Functionality
- 16.4.6. Integration Type
- 16.4.7. Deployment Mode
- 16.4.8. Organization Size
- 16.4.9. Industry Vertical
- 16.5. United Kingdom Digital Adoption Platforms Market
- 16.5.1. Country Segmental Analysis
- 16.5.2. Offering
- 16.5.3. Application Type
- 16.5.4. End-User Interface
- 16.5.5. Adoption Layer/Functionality
- 16.5.6. Integration Type
- 16.5.7. Deployment Mode
- 16.5.8. Organization Size
- 16.5.9. Industry Vertical
- 16.6. France Digital Adoption Platforms Market
- 16.6.1. Country Segmental Analysis
- 16.6.2. Offering
- 16.6.3. Application Type
- 16.6.4. End-User Interface
- 16.6.5. Adoption Layer/Functionality
- 16.6.6. Integration Type
- 16.6.7. Deployment Mode
- 16.6.8. Organization Size
- 16.6.9. Industry Vertical
- 16.7. Italy Digital Adoption Platforms Market
- 16.7.1. Country Segmental Analysis
- 16.7.2. Offering
- 16.7.3. Application Type
- 16.7.4. End-User Interface
- 16.7.5. Adoption Layer/Functionality
- 16.7.6. Integration Type
- 16.7.7. Deployment Mode
- 16.7.8. Organization Size
- 16.7.9. Industry Vertical
- 16.8. Spain Digital Adoption Platforms Market
- 16.8.1. Country Segmental Analysis
- 16.8.2. Offering
- 16.8.3. Application Type
- 16.8.4. End-User Interface
- 16.8.5. Adoption Layer/Functionality
- 16.8.6. Integration Type
- 16.8.7. Deployment Mode
- 16.8.8. Organization Size
- 16.8.9. Industry Vertical
- 16.9. Netherlands Digital Adoption Platforms Market
- 16.9.1. Country Segmental Analysis
- 16.9.2. Offering
- 16.9.3. Application Type
- 16.9.4. End-User Interface
- 16.9.5. Adoption Layer/Functionality
- 16.9.6. Integration Type
- 16.9.7. Deployment Mode
- 16.9.8. Organization Size
- 16.9.9. Industry Vertical
- 16.10. Nordic Countries Digital Adoption Platforms Market
- 16.10.1. Country Segmental Analysis
- 16.10.2. Offering
- 16.10.3. Application Type
- 16.10.4. End-User Interface
- 16.10.5. Adoption Layer/Functionality
- 16.10.6. Integration Type
- 16.10.7. Deployment Mode
- 16.10.8. Organization Size
- 16.10.9. Industry Vertical
- 16.11. Poland Digital Adoption Platforms Market
- 16.11.1. Country Segmental Analysis
- 16.11.2. Offering
- 16.11.3. Application Type
- 16.11.4. End-User Interface
- 16.11.5. Adoption Layer/Functionality
- 16.11.6. Integration Type
- 16.11.7. Deployment Mode
- 16.11.8. Organization Size
- 16.11.9. Industry Vertical
- 16.12. Russia & CIS Digital Adoption Platforms Market
- 16.12.1. Country Segmental Analysis
- 16.12.2. Offering
- 16.12.3. Application Type
- 16.12.4. End-User Interface
- 16.12.5. Adoption Layer/Functionality
- 16.12.6. Integration Type
- 16.12.7. Deployment Mode
- 16.12.8. Organization Size
- 16.12.9. Industry Vertical
- 16.13. Rest of Europe Digital Adoption Platforms Market
- 16.13.1. Country Segmental Analysis
- 16.13.2. Offering
- 16.13.3. Application Type
- 16.13.4. End-User Interface
- 16.13.5. Adoption Layer/Functionality
- 16.13.6. Integration Type
- 16.13.7. Deployment Mode
- 16.13.8. Organization Size
- 16.13.9. Industry Vertical
- 17. Asia Pacific Digital Adoption Platforms Market Analysis
- 17.1. Key Segment Analysis
- 17.2. Regional Snapshot
- 17.3. Asia Pacific Digital Adoption Platforms Market Size (Value - US$ Bn), Analysis, and Forecasts, 2021-2035
- 17.3.1. Offering
- 17.3.2. Application Type
- 17.3.3. End-User Interface
- 17.3.4. Adoption Layer/Functionality
- 17.3.5. Integration Type
- 17.3.6. Deployment Mode
- 17.3.7. Organization Size
- 17.3.8. Industry Vertical
- 17.3.9. Country
- 17.3.9.1. China
- 17.3.9.2. India
- 17.3.9.3. Japan
- 17.3.9.4. South Korea
- 17.3.9.5. Australia and New Zealand
- 17.3.9.6. Indonesia
- 17.3.9.7. Malaysia
- 17.3.9.8. Thailand
- 17.3.9.9. Vietnam
- 17.3.9.10. Rest of Asia Pacific
- 17.4. China Digital Adoption Platforms Market
- 17.4.1. Country Segmental Analysis
- 17.4.2. Offering
- 17.4.3. Application Type
- 17.4.4. End-User Interface
- 17.4.5. Adoption Layer/Functionality
- 17.4.6. Integration Type
- 17.4.7. Deployment Mode
- 17.4.8. Organization Size
- 17.4.9. Industry Vertical
- 17.5. India Digital Adoption Platforms Market
- 17.5.1. Country Segmental Analysis
- 17.5.2. Offering
- 17.5.3. Application Type
- 17.5.4. End-User Interface
- 17.5.5. Adoption Layer/Functionality
- 17.5.6. Integration Type
- 17.5.7. Deployment Mode
- 17.5.8. Organization Size
- 17.5.9. Industry Vertical
- 17.6. Japan Digital Adoption Platforms Market
- 17.6.1. Country Segmental Analysis
- 17.6.2. Offering
- 17.6.3. Application Type
- 17.6.4. End-User Interface
- 17.6.5. Adoption Layer/Functionality
- 17.6.6. Integration Type
- 17.6.7. Deployment Mode
- 17.6.8. Organization Size
- 17.6.9. Industry Vertical
- 17.7. South Korea Digital Adoption Platforms Market
- 17.7.1. Country Segmental Analysis
- 17.7.2. Offering
- 17.7.3. Application Type
- 17.7.4. End-User Interface
- 17.7.5. Adoption Layer/Functionality
- 17.7.6. Integration Type
- 17.7.7. Deployment Mode
- 17.7.8. Organization Size
- 17.7.9. Industry Vertical
- 17.8. Australia and New Zealand Digital Adoption Platforms Market
- 17.8.1. Country Segmental Analysis
- 17.8.2. Offering
- 17.8.3. Application Type
- 17.8.4. End-User Interface
- 17.8.5. Adoption Layer/Functionality
- 17.8.6. Integration Type
- 17.8.7. Deployment Mode
- 17.8.8. Organization Size
- 17.8.9. Industry Vertical
- 17.9. Indonesia Digital Adoption Platforms Market
- 17.9.1. Country Segmental Analysis
- 17.9.2. Offering
- 17.9.3. Application Type
- 17.9.4. End-User Interface
- 17.9.5. Adoption Layer/Functionality
- 17.9.6. Integration Type
- 17.9.7. Deployment Mode
- 17.9.8. Organization Size
- 17.9.9. Industry Vertical
- 17.10. Malaysia Digital Adoption Platforms Market
- 17.10.1. Country Segmental Analysis
- 17.10.2. Offering
- 17.10.3. Application Type
- 17.10.4. End-User Interface
- 17.10.5. Adoption Layer/Functionality
- 17.10.6. Integration Type
- 17.10.7. Deployment Mode
- 17.10.8. Organization Size
- 17.10.9. Industry Vertical
- 17.11. Thailand Digital Adoption Platforms Market
- 17.11.1. Country Segmental Analysis
- 17.11.2. Offering
- 17.11.3. Application Type
- 17.11.4. End-User Interface
- 17.11.5. Adoption Layer/Functionality
- 17.11.6. Integration Type
- 17.11.7. Deployment Mode
- 17.11.8. Organization Size
- 17.11.9. Industry Vertical
- 17.12. Vietnam Digital Adoption Platforms Market
- 17.12.1. Country Segmental Analysis
- 17.12.2. Offering
- 17.12.3. Application Type
- 17.12.4. End-User Interface
- 17.12.5. Adoption Layer/Functionality
- 17.12.6. Integration Type
- 17.12.7. Deployment Mode
- 17.12.8. Organization Size
- 17.12.9. Industry Vertical
- 17.13. Rest of Asia Pacific Digital Adoption Platforms Market
- 17.13.1. Country Segmental Analysis
- 17.13.2. Offering
- 17.13.3. Application Type
- 17.13.4. End-User Interface
- 17.13.5. Adoption Layer/Functionality
- 17.13.6. Integration Type
- 17.13.7. Deployment Mode
- 17.13.8. Organization Size
- 17.13.9. Industry Vertical
- 18. Middle East Digital Adoption Platforms Market Analysis
- 18.1. Key Segment Analysis
- 18.2. Regional Snapshot
- 18.3. Middle East Digital Adoption Platforms Market Size (Value - US$ Bn), Analysis, and Forecasts, 2021-2035
- 18.3.1. Offering
- 18.3.2. Application Type
- 18.3.3. End-User Interface
- 18.3.4. Adoption Layer/Functionality
- 18.3.5. Integration Type
- 18.3.6. Deployment Mode
- 18.3.7. Organization Size
- 18.3.8. Industry Vertical
- 18.3.9. Country
- 18.3.9.1. Turkey
- 18.3.9.2. UAE
- 18.3.9.3. Saudi Arabia
- 18.3.9.4. Israel
- 18.3.9.5. Rest of Middle East
- 18.4. Turkey Digital Adoption Platforms Market
- 18.4.1. Country Segmental Analysis
- 18.4.2. Offering
- 18.4.3. Application Type
- 18.4.4. End-User Interface
- 18.4.5. Adoption Layer/Functionality
- 18.4.6. Integration Type
- 18.4.7. Deployment Mode
- 18.4.8. Organization Size
- 18.4.9. Industry Vertical
- 18.5. UAE Digital Adoption Platforms Market
- 18.5.1. Country Segmental Analysis
- 18.5.2. Offering
- 18.5.3. Application Type
- 18.5.4. End-User Interface
- 18.5.5. Adoption Layer/Functionality
- 18.5.6. Integration Type
- 18.5.7. Deployment Mode
- 18.5.8. Organization Size
- 18.5.9. Industry Vertical
- 18.6. Saudi Arabia Digital Adoption Platforms Market
- 18.6.1. Country Segmental Analysis
- 18.6.2. Offering
- 18.6.3. Application Type
- 18.6.4. End-User Interface
- 18.6.5. Adoption Layer/Functionality
- 18.6.6. Integration Type
- 18.6.7. Deployment Mode
- 18.6.8. Organization Size
- 18.6.9. Industry Vertical
- 18.7. Israel Digital Adoption Platforms Market
- 18.7.1. Country Segmental Analysis
- 18.7.2. Offering
- 18.7.3. Application Type
- 18.7.4. End-User Interface
- 18.7.5. Adoption Layer/Functionality
- 18.7.6. Integration Type
- 18.7.7. Deployment Mode
- 18.7.8. Organization Size
- 18.7.9. Industry Vertical
- 18.8. Rest of Middle East Digital Adoption Platforms Market
- 18.8.1. Country Segmental Analysis
- 18.8.2. Offering
- 18.8.3. Application Type
- 18.8.4. End-User Interface
- 18.8.5. Adoption Layer/Functionality
- 18.8.6. Integration Type
- 18.8.7. Deployment Mode
- 18.8.8. Organization Size
- 18.8.9. Industry Vertical
- 19. Africa Digital Adoption Platforms Market Analysis
- 19.1. Key Segment Analysis
- 19.2. Regional Snapshot
- 19.3. Africa Digital Adoption Platforms Market Size (Value - US$ Bn), Analysis, and Forecasts, 2021-2035
- 19.3.1. Offering
- 19.3.2. Application Type
- 19.3.3. End-User Interface
- 19.3.4. Adoption Layer/Functionality
- 19.3.5. Integration Type
- 19.3.6. Deployment Mode
- 19.3.7. Organization Size
- 19.3.8. Industry Vertical
- 19.3.9. Country
- 19.3.9.1. South Africa
- 19.3.9.2. Egypt
- 19.3.9.3. Nigeria
- 19.3.9.4. Algeria
- 19.3.9.5. Rest of Africa
- 19.4. South Africa Digital Adoption Platforms Market
- 19.4.1. Country Segmental Analysis
- 19.4.2. Offering
- 19.4.3. Application Type
- 19.4.4. End-User Interface
- 19.4.5. Adoption Layer/Functionality
- 19.4.6. Integration Type
- 19.4.7. Deployment Mode
- 19.4.8. Organization Size
- 19.4.9. Industry Vertical
- 19.5. Egypt Digital Adoption Platforms Market
- 19.5.1. Country Segmental Analysis
- 19.5.2. Offering
- 19.5.3. Application Type
- 19.5.4. End-User Interface
- 19.5.5. Adoption Layer/Functionality
- 19.5.6. Integration Type
- 19.5.7. Deployment Mode
- 19.5.8. Organization Size
- 19.5.9. Industry Vertical
- 19.6. Nigeria Digital Adoption Platforms Market
- 19.6.1. Country Segmental Analysis
- 19.6.2. Offering
- 19.6.3. Application Type
- 19.6.4. End-User Interface
- 19.6.5. Adoption Layer/Functionality
- 19.6.6. Integration Type
- 19.6.7. Deployment Mode
- 19.6.8. Organization Size
- 19.6.9. Industry Vertical
- 19.7. Algeria Digital Adoption Platforms Market
- 19.7.1. Country Segmental Analysis
- 19.7.2. Offering
- 19.7.3. Application Type
- 19.7.4. End-User Interface
- 19.7.5. Adoption Layer/Functionality
- 19.7.6. Integration Type
- 19.7.7. Deployment Mode
- 19.7.8. Organization Size
- 19.7.9. Industry Vertical
- 19.8. Rest of Africa Digital Adoption Platforms Market
- 19.8.1. Country Segmental Analysis
- 19.8.2. Offering
- 19.8.3. Application Type
- 19.8.4. End-User Interface
- 19.8.5. Adoption Layer/Functionality
- 19.8.6. Integration Type
- 19.8.7. Deployment Mode
- 19.8.8. Organization Size
- 19.8.9. Industry Vertical
- 20. South America Digital Adoption Platforms Market Analysis
- 20.1. Key Segment Analysis
- 20.2. Regional Snapshot
- 20.3. South America Digital Adoption Platforms Market Size (Value - US$ Bn), Analysis, and Forecasts, 2021-2035
- 20.3.1. Offering
- 20.3.2. Application Type
- 20.3.3. End-User Interface
- 20.3.4. Adoption Layer/Functionality
- 20.3.5. Integration Type
- 20.3.6. Deployment Mode
- 20.3.7. Organization Size
- 20.3.8. Industry Vertical
- 20.3.9. Country
- 20.3.9.1. Brazil
- 20.3.9.2. Argentina
- 20.3.9.3. Rest of South America
- 20.4. Brazil Digital Adoption Platforms Market
- 20.4.1. Country Segmental Analysis
- 20.4.2. Offering
- 20.4.3. Application Type
- 20.4.4. End-User Interface
- 20.4.5. Adoption Layer/Functionality
- 20.4.6. Integration Type
- 20.4.7. Deployment Mode
- 20.4.8. Organization Size
- 20.4.9. Industry Vertical
- 20.5. Argentina Digital Adoption Platforms Market
- 20.5.1. Country Segmental Analysis
- 20.5.2. Offering
- 20.5.3. Application Type
- 20.5.4. End-User Interface
- 20.5.5. Adoption Layer/Functionality
- 20.5.6. Integration Type
- 20.5.7. Deployment Mode
- 20.5.8. Organization Size
- 20.5.9. Industry Vertical
- 20.6. Rest of South America Digital Adoption Platforms Market
- 20.6.1. Country Segmental Analysis
- 20.6.2. Offering
- 20.6.3. Application Type
- 20.6.4. End-User Interface
- 20.6.5. Adoption Layer/Functionality
- 20.6.6. Integration Type
- 20.6.7. Deployment Mode
- 20.6.8. Organization Size
- 20.6.9. Industry Vertical
- 21. Key Players/ Company Profile
- 21.1. Appcues
- 21.1.1. Company Details/ Overview
- 21.1.2. Company Financials
- 21.1.3. Key Customers and Competitors
- 21.1.4. Business/ Industry Portfolio
- 21.1.5. Product Portfolio/ Specification Details
- 21.1.6. Pricing Data
- 21.1.7. Strategic Overview
- 21.1.8. Recent Developments
- 21.2. Apty
- 21.3. Chameleon
- 21.4. Gainsight (PX)
- 21.5. Inline Manual
- 21.6. iorad
- 21.7. Nickelled
- 21.8. Pendo
- 21.9. Spekit
- 21.10. Toonimo
- 21.11. UserGuiding
- 21.12. Userlane
- 21.13. Userpilot
- 21.14. WalkMe
- 21.15. Whatfix
- 21.16. Other Key Players
- 21.1. Appcues
Note* - This is just tentative list of players. While providing the report, we will cover more number of players based on their revenue and share for each geography
Research Design
Our research design integrates both demand-side and supply-side analysis through a balanced combination of primary and secondary research methodologies. By utilizing both bottom-up and top-down approaches alongside rigorous data triangulation methods, we deliver robust market intelligence that supports strategic decision-making.
MarketGenics' comprehensive research design framework ensures the delivery of accurate, reliable, and actionable market intelligence. Through the integration of multiple research approaches, rigorous validation processes, and expert analysis, we provide our clients with the insights needed to make informed strategic decisions and capitalize on market opportunities.
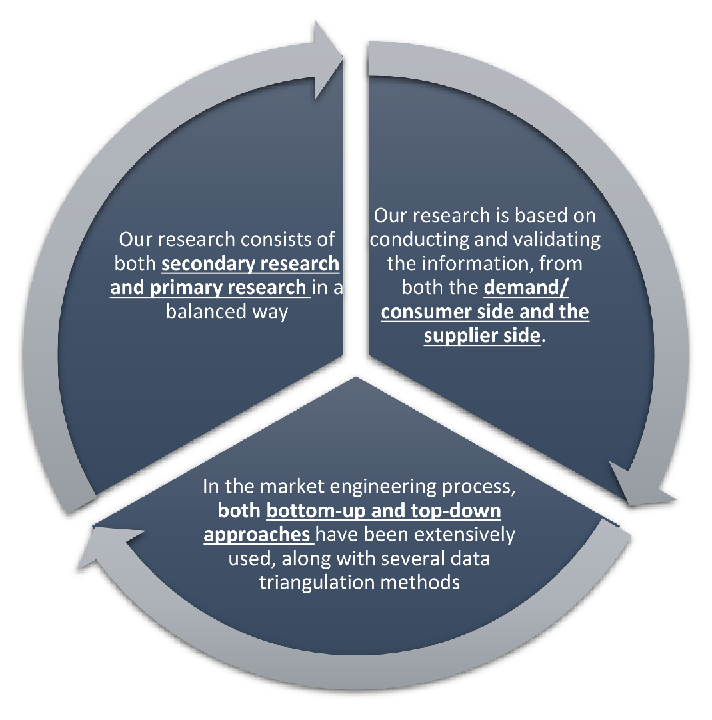
MarketGenics leverages a dedicated industry panel of experts and a comprehensive suite of paid databases to effectively collect, consolidate, and analyze market intelligence.
Our approach has consistently proven to be reliable and effective in generating accurate market insights, identifying key industry trends, and uncovering emerging business opportunities.
Through both primary and secondary research, we capture and analyze critical company-level data such as manufacturing footprints, including technical centers, R&D facilities, sales offices, and headquarters.
Our expert panel further enhances our ability to estimate market size for specific brands based on validated field-level intelligence.
Our data mining techniques incorporate both parametric and non-parametric methods, allowing for structured data collection, sorting, processing, and cleaning.
Demand projections are derived from large-scale data sets analyzed through proprietary algorithms, culminating in robust and reliable market sizing.
Research Approach
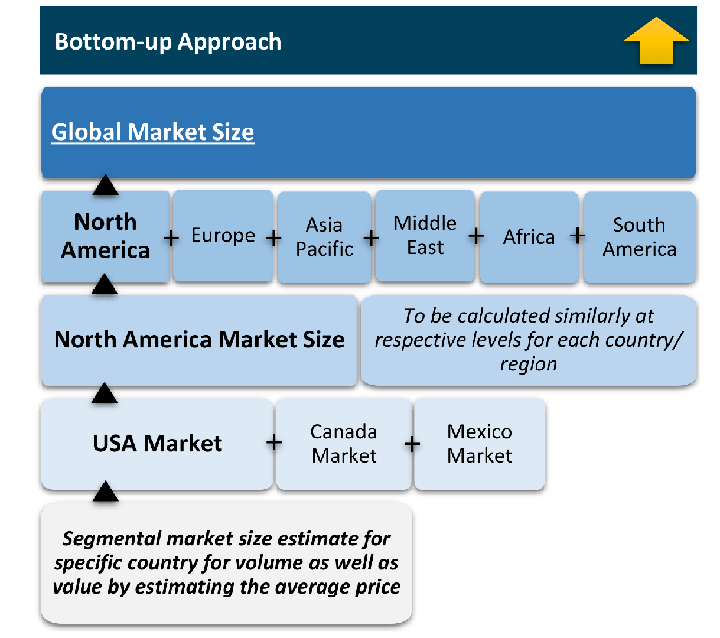
The bottom-up approach builds market estimates by starting with the smallest addressable market units and systematically aggregating them to create comprehensive market size projections.
This method begins with specific, granular data points and builds upward to create the complete market landscape.
Customer Analysis → Segmental Analysis → Geographical Analysis
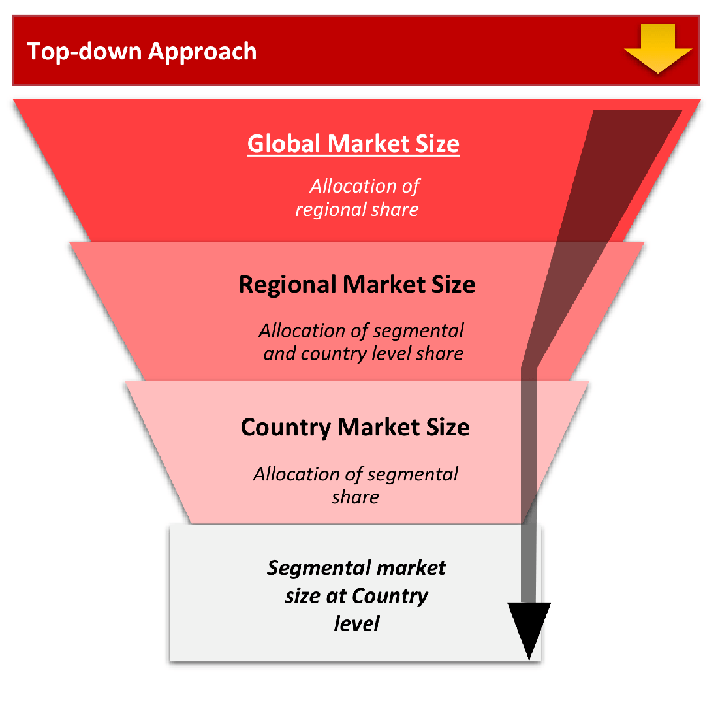
The top-down approach starts with the broadest possible market data and systematically narrows it down through a series of filters and assumptions to arrive at specific market segments or opportunities.
This method begins with the big picture and works downward to increasingly specific market slices.
TAM → SAM → SOM
Research Methods
Desk / Secondary Research
While analysing the market, we extensively study secondary sources, directories, and databases to identify and collect information useful for this technical, market-oriented, and commercial report. Secondary sources that we utilize are not only the public sources, but it is a combination of Open Source, Associations, Paid Databases, MG Repository & Knowledgebase, and others.
- Company websites, annual reports, financial reports, broker reports, and investor presentations
- National government documents, statistical databases and reports
- News articles, press releases and web-casts specific to the companies operating in the market, Magazines, reports, and others
- We gather information from commercial data sources for deriving company specific data such as segmental revenue, share for geography, product revenue, and others
- Internal and external proprietary databases (industry-specific), relevant patent, and regulatory databases
- Governing Bodies, Government Organizations
- Relevant Authorities, Country-specific Associations for Industries
We also employ the model mapping approach to estimate the product level market data through the players' product portfolio
Primary Research
Primary research/ interviews is vital in analyzing the market. Most of the cases involves paid primary interviews. Primary sources include primary interviews through e-mail interactions, telephonic interviews, surveys as well as face-to-face interviews with the different stakeholders across the value chain including several industry experts.
| Type of Respondents | Number of Primaries |
|---|---|
| Tier 2/3 Suppliers | ~20 |
| Tier 1 Suppliers | ~25 |
| End-users | ~25 |
| Industry Expert/ Panel/ Consultant | ~30 |
| Total | ~100 |
MG Knowledgebase
• Repository of industry blog, newsletter and case studies
• Online platform covering detailed market reports, and company profiles
Forecasting Factors and Models
Forecasting Factors
- Historical Trends – Past market patterns, cycles, and major events that shaped how markets behave over time. Understanding past trends helps predict future behavior.
- Industry Factors – Specific characteristics of the industry like structure, regulations, and innovation cycles that affect market dynamics.
- Macroeconomic Factors – Economic conditions like GDP growth, inflation, and employment rates that affect how much money people have to spend.
- Demographic Factors – Population characteristics like age, income, and location that determine who can buy your product.
- Technology Factors – How quickly people adopt new technology and how much technology infrastructure exists.
- Regulatory Factors – Government rules, laws, and policies that can help or restrict market growth.
- Competitive Factors – Analyzing competition structure such as degree of competition and bargaining power of buyers and suppliers.
Forecasting Models / Techniques
Multiple Regression Analysis
- Identify and quantify factors that drive market changes
- Statistical modeling to establish relationships between market drivers and outcomes
Time Series Analysis – Seasonal Patterns
- Understand regular cyclical patterns in market demand
- Advanced statistical techniques to separate trend, seasonal, and irregular components
Time Series Analysis – Trend Analysis
- Identify underlying market growth patterns and momentum
- Statistical analysis of historical data to project future trends
Expert Opinion – Expert Interviews
- Gather deep industry insights and contextual understanding
- In-depth interviews with key industry stakeholders
Multi-Scenario Development
- Prepare for uncertainty by modeling different possible futures
- Creating optimistic, pessimistic, and most likely scenarios
Time Series Analysis – Moving Averages
- Sophisticated forecasting for complex time series data
- Auto-regressive integrated moving average models with seasonal components
Econometric Models
- Apply economic theory to market forecasting
- Sophisticated economic models that account for market interactions
Expert Opinion – Delphi Method
- Harness collective wisdom of industry experts
- Structured, multi-round expert consultation process
Monte Carlo Simulation
- Quantify uncertainty and probability distributions
- Thousands of simulations with varying input parameters
Research Analysis
Our research framework is built upon the fundamental principle of validating market intelligence from both demand and supply perspectives. This dual-sided approach ensures comprehensive market understanding and reduces the risk of single-source bias.
Demand-Side Analysis: We understand end-user/application behavior, preferences, and market needs along with the penetration of the product for specific application.
Supply-Side Analysis: We estimate overall market revenue, analyze the segmental share along with industry capacity, competitive landscape, and market structure.
Validation & Evaluation
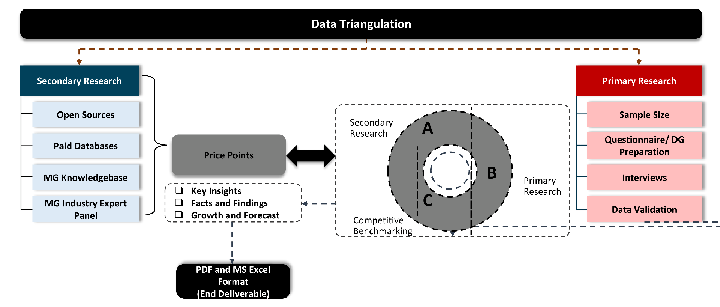
Data triangulation is a validation technique that uses multiple methods, sources, or perspectives to examine the same research question, thereby increasing the credibility and reliability of research findings. In market research, triangulation serves as a quality assurance mechanism that helps identify and minimize bias, validate assumptions, and ensure accuracy in market estimates.
- Data Source Triangulation – Using multiple data sources to examine the same phenomenon
- Methodological Triangulation – Using multiple research methods to study the same research question
- Investigator Triangulation – Using multiple researchers or analysts to examine the same data
- Theoretical Triangulation – Using multiple theoretical perspectives to interpret the same data
Custom Market Research Services
We will customise the research for you, in case the report listed above does not meet your requirements.
Get 10% Free Customisation